Desten kaybolmadan önce kaydet
Bu kartlar henüz kaydedilmedi — sayfayı terk ettiğinde silinecekler. Saklamak ve aşağıdakilerin tümünün kilidini açmak için ücretsiz bir hesap oluştur.
- Bu desteyi hesabına kaydet
- Aralıklı tekrar ile çalış
- Anki (.apkg) olarak dışa aktar veya PDF yap
- 100 sayfaya kadar olan belgeleri işle
- PDF'lerinden çıkarılan görseller
- Daha net metin çıkarma ve daha gelişmiş bir yapay zeka modeli
What are the two types of events defined after the reporting period?
Events occurring after the reporting period are classified as either _______ or _______ events.
What is the stated purpose of disclosure notes in financial reporting?
Financial reporting requires companies to _______ the purpose of disclosure notes.
Which financial statements are specifically mentioned as being prepared from given information?
One learning objective is to prepare a _______ and a _______ from provided information.
What is one performance objective related to financial statements under PER (PO7)?
The PER performance objective PO7 requires the ability to prepare and review _______ in accordance with _______.
What is the starting point in the process of preparing basic financial statements as shown in the flowchart? 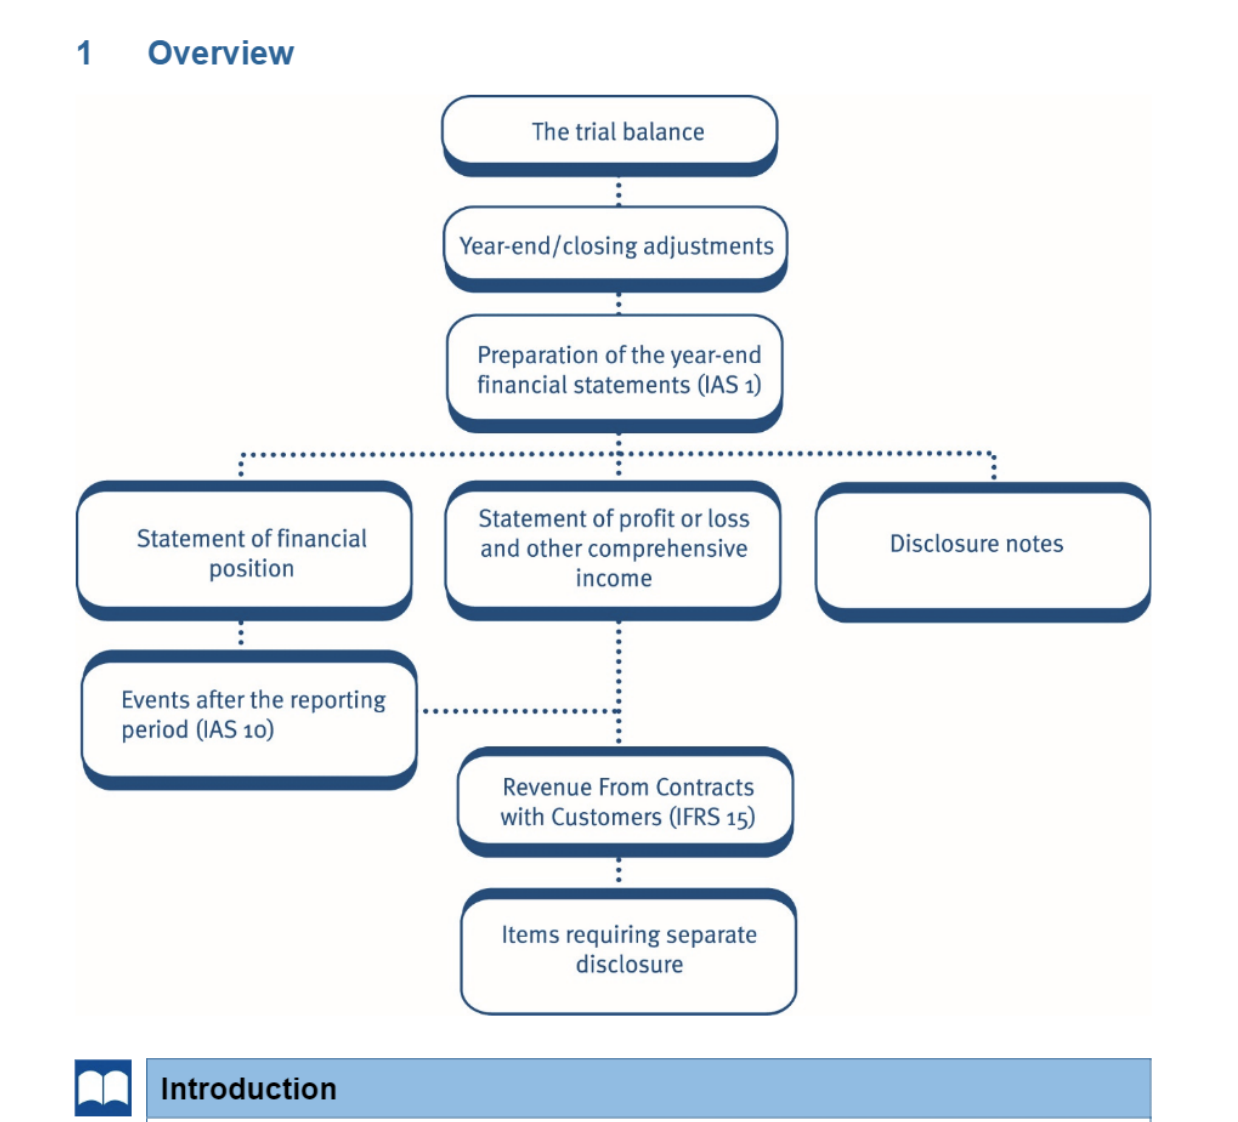
What is the second step in the preparation of financial statements after the trial balance?
Which accounting standard governs the preparation of year-end financial statements?
Which accounting standard deals with events occurring after the reporting period?
Which accounting standard addresses revenue from contracts with customers?
The process of preparing financial statements involves entities such as: - _______ - _______ - _______
The preparation of financial statements applies to both a _______ or a _______.
For which two reporting levels is the preparation of financial statements for a limited liability company a key syllabus element? - _______ - _______
What is the first step in the process of preparing financial statements as shown in the flowchart? 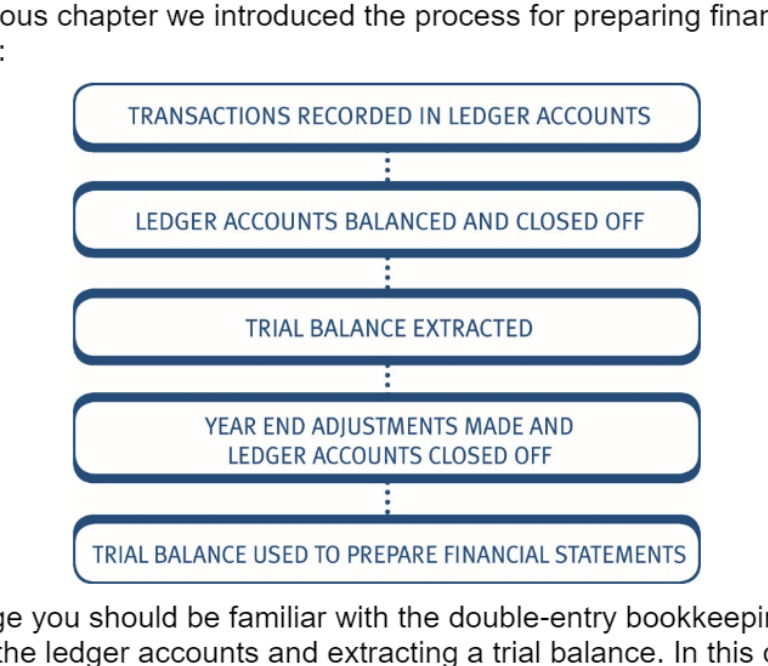
The standard process for preparing financial statements follows these steps: 1. Transactions recorded in ledger accounts 2. Ledger accounts balanced and closed off 3. _______ 4. Year end adjustments made and ledger accounts closed off 5. Trial balance used to prepare financial statements
What must be done to the trial balance figures before financial statements are created?
Common end-of-period adjustments include: - Closing _______ - _______ charge for the year - _______ and _______ - _______ and allowances for receivables - Provisions and contingent _______ - Income tax - Events after the reporting period
What is the accounting entry to record closing inventory?
What is the accounting entry for the annual depreciation charge?
What is the accounting entry for accruals?
What is the accounting entry for prepayments?
What is the accounting entry for irrecoverable debts?
What is the accounting entry for an increase in the allowance for receivables?
What is the accounting entry for a decrease in the allowance for receivables?
What is the accounting entry for the tax estimate for the year?
What is the accounting entry to record an overprovision of tax from a prior year?
What is the accounting entry to record an underprovision of tax from a prior year?
The accounting entry for _______ involves debiting Inventory (SFP) and crediting _______.
The accounting entry for an _______ in the allowance for receivables is debiting _______ and crediting _______.
Which accounting standard governs the presentation of published company financial statements?
Name the components that are required to be presented in a set of financial statements according to IAS 1.
What does a statement of financial position summarize?
IAS 1 requires that assets and liabilities in the statement of financial position must be classified as either _______ or _______.
List the categories included under 'Non-current assets' in the standardized statement of financial position.
List the categories included under 'Current assets' in the standardized statement of financial position.
What standard format is shown in the statement of financial position for XYZ Co at 31 December 20XX?
Name the five categories included under 'Equity' in the statement of financial position.
What items are typically listed under 'Current liabilities' in a statement of financial position?
An asset is classified as a _______ if it is held primarily for trading purposes, expected to be realised within _______ of the statement of financial position date, or is _______.
How should assets that do not meet the definition of a current asset be classified?
Can inventory or receivables be classified as current assets even if they are not expected to be realised within twelve months?
Which accounting standard provides the rules for distinguishing between current and non-current assets and liabilities?
What is the primary function of the statement of profit or loss?
A liability is classified as a _______ if it is expected to be settled in the normal course of the enterprise's operating cycle.
A liability should be classified as a current liability if it is held primarily for the purpose of being _______.
A liability is a current liability if it is due to be settled within _______ of the statement of financial position date.
How are liabilities that do not meet the criteria for current liabilities classified?
In the statement of profit or loss, what is the sequence after calculating gross profit?
The statement of profit or loss formula is: Revenue - _______ = Gross profit.
What is the order of items deducted from 'Profit from operations' to arrive at 'Profit before tax'?
The final step in the statement of profit or loss is: Profit before tax - _______ = Net profit for the period.
What is the primary reason that the 'statement of profit or loss and other comprehensive income' extends the traditional 'statement of profit or loss'?
A common example of an unrealised gain that is reported in other comprehensive income is the _______.
Why are unrealised gains, such as those from asset revaluation, excluded from net profit for the period?
Where are unrealised gains added in the financial reporting structure presented in this chapter?
They are added to the _______ of the statement of profit or loss.
An entity has the option to present 'other comprehensive income' information in which two ways?
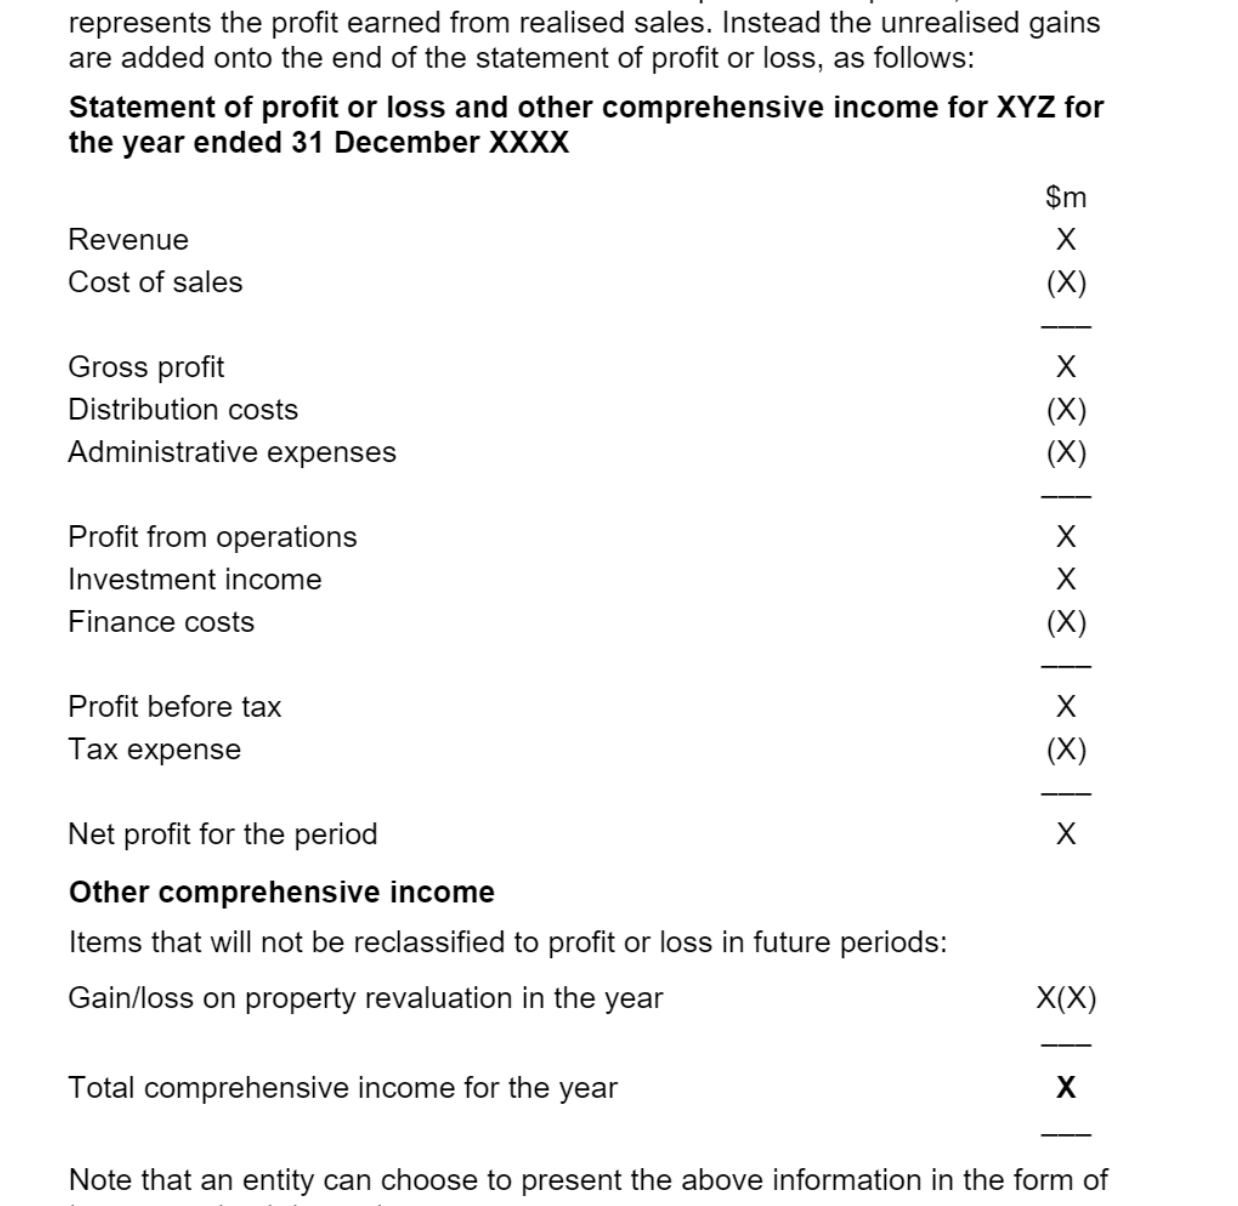
In the provided statement format, _______ is calculated by adding the gain or loss on property revaluation to the net profit for the period.
Why must certain items be disclosed separately on the face of the financial statements or in the notes?
Items requiring separate disclosure are typically _______ that are not part of the _______ of the business.
What are three examples of items that require separate disclosure in the statement of profit or loss?
How should items requiring separate disclosure be presented in the statement of profit or loss?
Based on the provided flowchart, what two components link the statement of financial position at the start and end of a period? 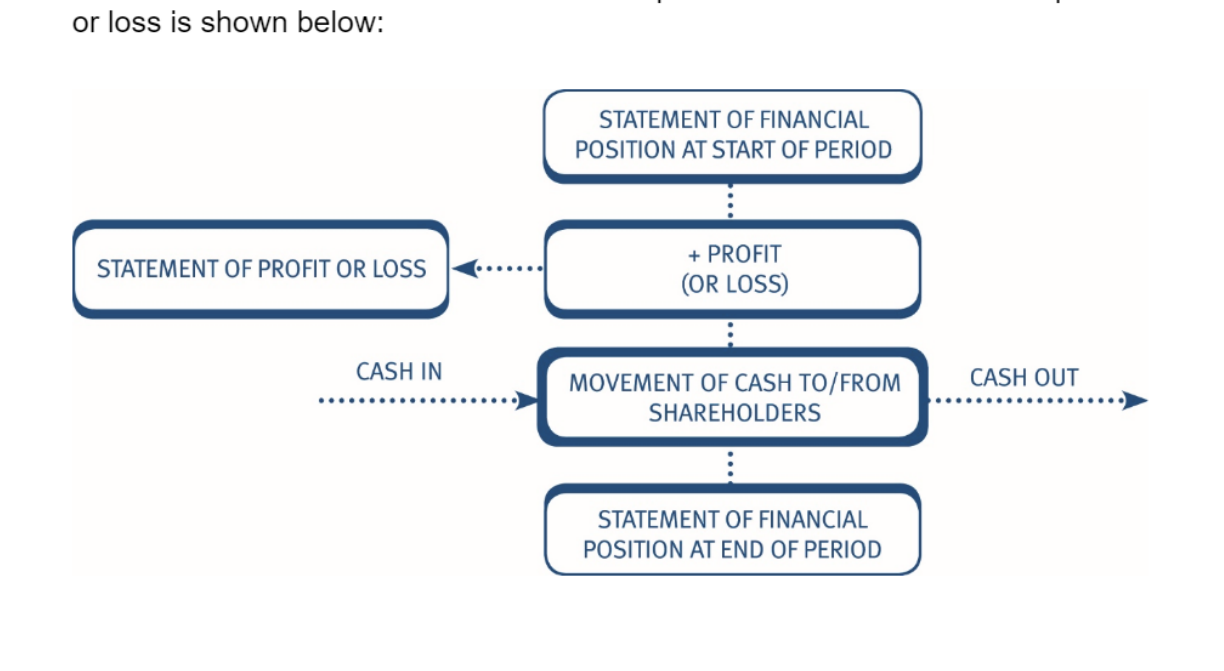
The movement of cash between a business and its shareholders interacts with the _______ to reflect changes between the start and end of a period.
What does equity represent in a company?
The components of equity include share capital, share premium, and _______.
What is the function of the revaluation surplus?
Why can the revaluation surplus not be included in retained earnings?
What are retained earnings?
What is the purpose of the statement of changes in equity?
In the statement of changes in equity, dividends paid are represented by _______.
Based on the provided statement of changes in equity for XYZ Co, how are equity shares issued recorded?
Based on the statement of changes in equity for XYZ Co, where is net profit added?
The main reserves in a company are the _______ and _______.
What is the primary purpose of disclosure notes in financial statements?
The _______ are required to explain the accounting policies used when preparing the accounts.
Disclosure notes are used to explain the movement between the _______ and _______ balances of major statement of financial position items.
According to the requirements, disclosure notes are provided to offer further _______ or _______ to users to ensure the financial statements are understandable.
Which specific chapter covers disclosure notes related to inventory?
Which chapters cover disclosure notes for non-current tangible and intangible assets?
Which chapter covers disclosure notes for provisions?
Which chapter covers disclosure notes for events after the reporting period?
What is the primary objective of the exercise shown in the illustration?
In the trial balance for Crown Co, the ordinary share capital of $100,000 is recorded as a _______ balance. 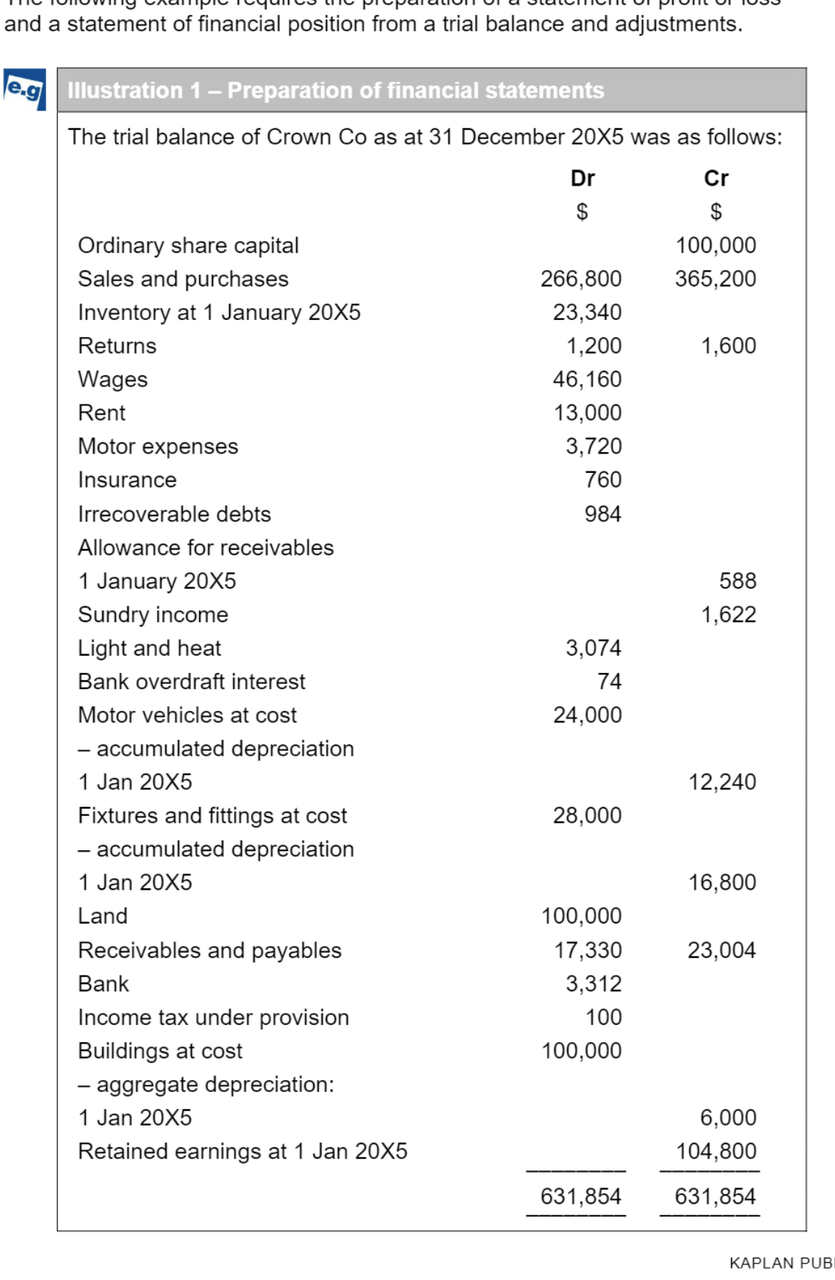
In the provided trial balance, are 'Sales' and 'Purchases' separate accounts or a combined entry?
The inventory value at the start of the period for Crown Co on 1 January 20X5 is _______.
What is the total value of 'Land' listed in the Crown Co trial balance?
The accumulated depreciation for motor vehicles as of 1 January 20X5 is a credit balance of _______.
What are the recorded amounts for 'Receivables and payables' in the trial balance?
The retained earnings as of 1 January 20X5 for Crown Co are _______ and are recorded as a _______ balance.
What is the total of the debit and credit columns in the trial balance?
What is the inventory valuation for Crown Co. as of 31 December 20X5?
How are rent, and light and heat adjustments handled for Crown Co. at 31 December 20X5?
What is the revalued amount for land at 31 December 20X5?
How are receivables adjusted for Crown Co. at 31 December 20X5?
What is the estimated income tax charge for the year for Crown Co.?
What is the annual depreciation rate and method for buildings?
How are fixtures and fittings depreciated?
What is the depreciation rate and method for motor vehicles?
What is the policy for charging depreciation in the year of acquisition and year of disposal?
The annual depreciation for buildings is _______ using the _______ method.
The annual depreciation for motor vehicles is _______ on a _______ basis.
What is the formula used to calculate gross profit as shown in the statement of profit or loss?
Total comprehensive income is the sum of Profit for the year and _______.
List the components classified under Current assets in the statement of financial position.
In the statement of financial position, Property, plant and equipment is classified as a _______.
Calculate the total value of current assets based on the figures provided.
The statement of profit or loss for the year ended 31 December 20X5 shows a revenue of $_______ after deducting the adjustment.
The income tax charge deducted from Profit before tax to reach the Profit for the year is $_______.
What is the total comprehensive income for the year ended 31 December 20X5?
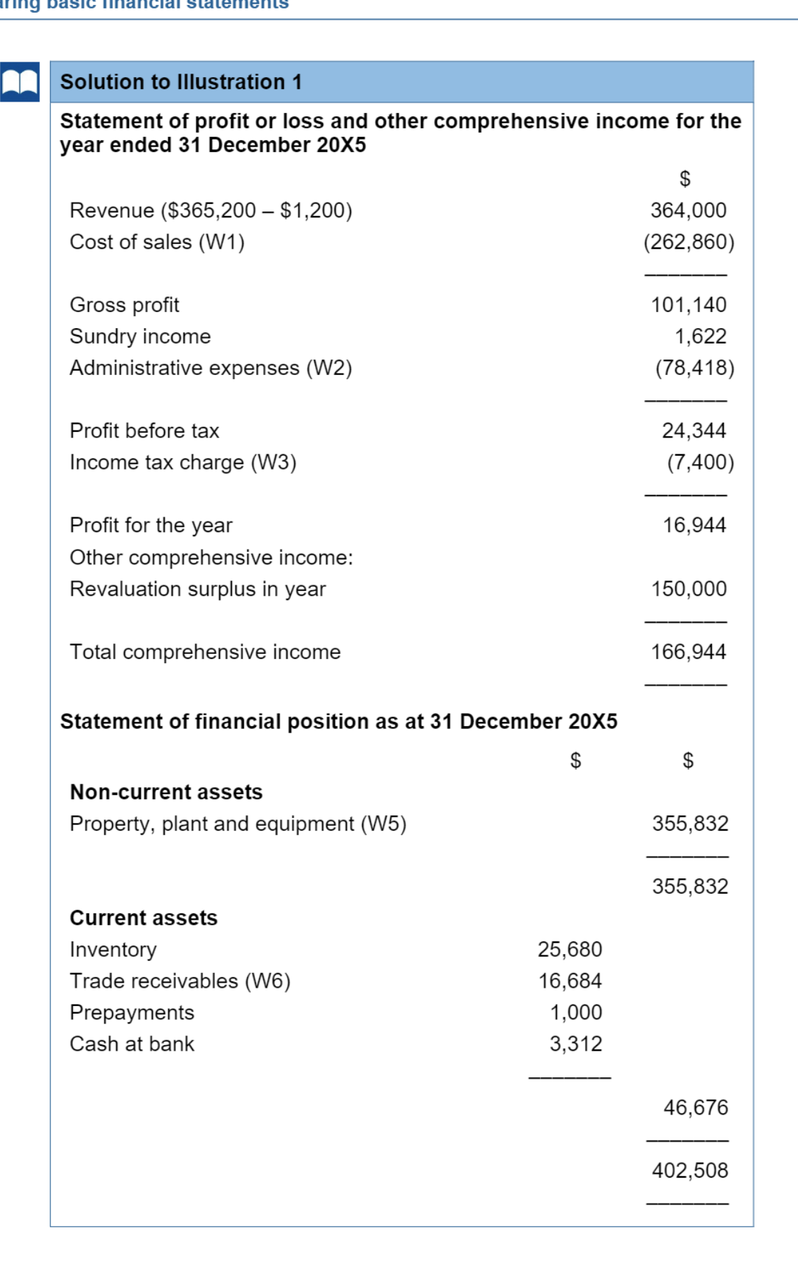 Based on the statement of financial position, the total assets amount to $_______.
What is the total value of equity based on the provided financial data?
What are the components of current liabilities?
How is the cost of sales calculated (W1)?
The calculation for cost of sales (W1) starts with opening inventory of $_______ and adds purchases of _______.
What is the final calculated cost of sales (W1)?
In the administrative expenses (W2), the total expense amount is _______.
List the three largest administrative expenses shown in (W2).
The formula used to calculate Revaluation surplus in the provided data is _______.
The total of all current liabilities is _______.
The total equity and current liabilities combined equals _______.
What is the calculation for Retained earnings in the provided data?
The total administrative expenses include irrecoverable debts calculated as _______.
What is the total income tax expense for the year, based on the income tax schedule?
How is the depreciation charge for buildings calculated?
How is the depreciation charge for fixtures calculated?
How is the depreciation charge for vehicles calculated?
The total depreciation charge for the year is \(_______.
What is the carrying amount (CA) for buildings after accumulated depreciation?
What is the carrying amount (CA) for fixtures and fittings after accumulated depreciation?
What is the carrying amount (CA) for motor vehicles after accumulated depreciation?
The total cost or valuation of non-current assets is \(_______.
How is the net trade receivables balance calculated after allowance?
What is the impact of the movement in the allowance for receivables on the P&L?
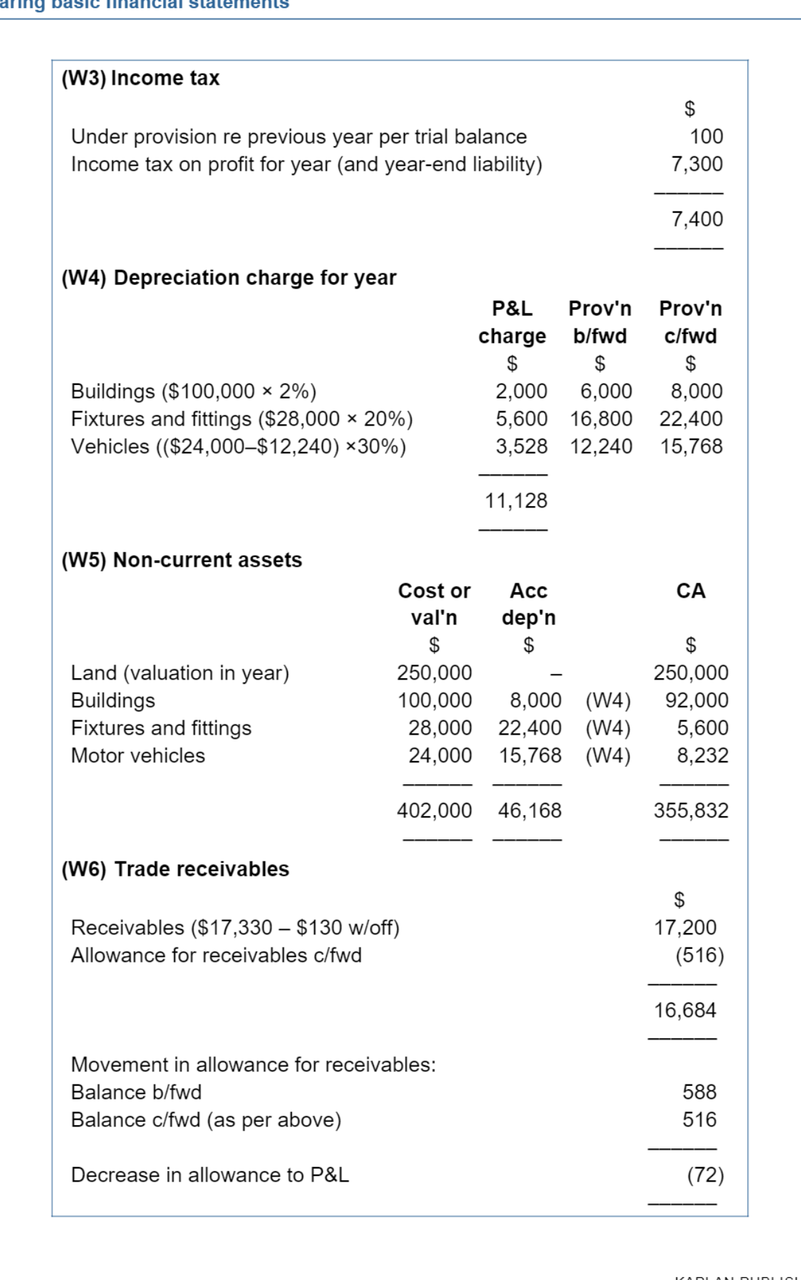 The movement in the allowance for receivables is calculated as the difference between the balance b/fwd of \(_______ and the balance c/fwd of \(_______.
What is the new carrying amount for the building as per adjustment 1 for Penguin Co?
What is the proposed final ordinary dividend per share as per adjustment 2?
What is the estimated current year tax charge as per adjustment 3?
What is the closing inventory value for Penguin Co as per adjustment 4?
What does the suspense account balance of $8,000 represent according to adjustment 5?
The trial balance of Penguin Co shows a tax account balance of $500, which represents an _______ of tax from the previous year.
The three financial statements to be prepared for Penguin Co are the _______, the _______, and the _______.
What is the inventory valuation for Ali Page as at 30 June 20X7?
How should the write-off of an irrecoverable debt of $1,000 be classified?
How should the wages cost of $15,000 be split?
Where should the $5,000 depreciation charge for the year be classified?
The trial balance shows a bank balance of _______.
The interest rate on the bank loan shown in the trial balance is _______.
What is the total value of purchases listed in the trial balance?
What is the total value of sales listed in the trial balance?
What is the balance of drawings listed in the trial balance?
What is the value of the suspense account listed in the trial balance?
The inventory value at the start of the period (1 July 20X6) was _______.
The capital account at the start of the period (1 July 20X6) was _______.
What is the definition of events after the reporting period according to IAS 10?
IAS 10 classifies events after the reporting period into two categories: _______ events and _______ events. 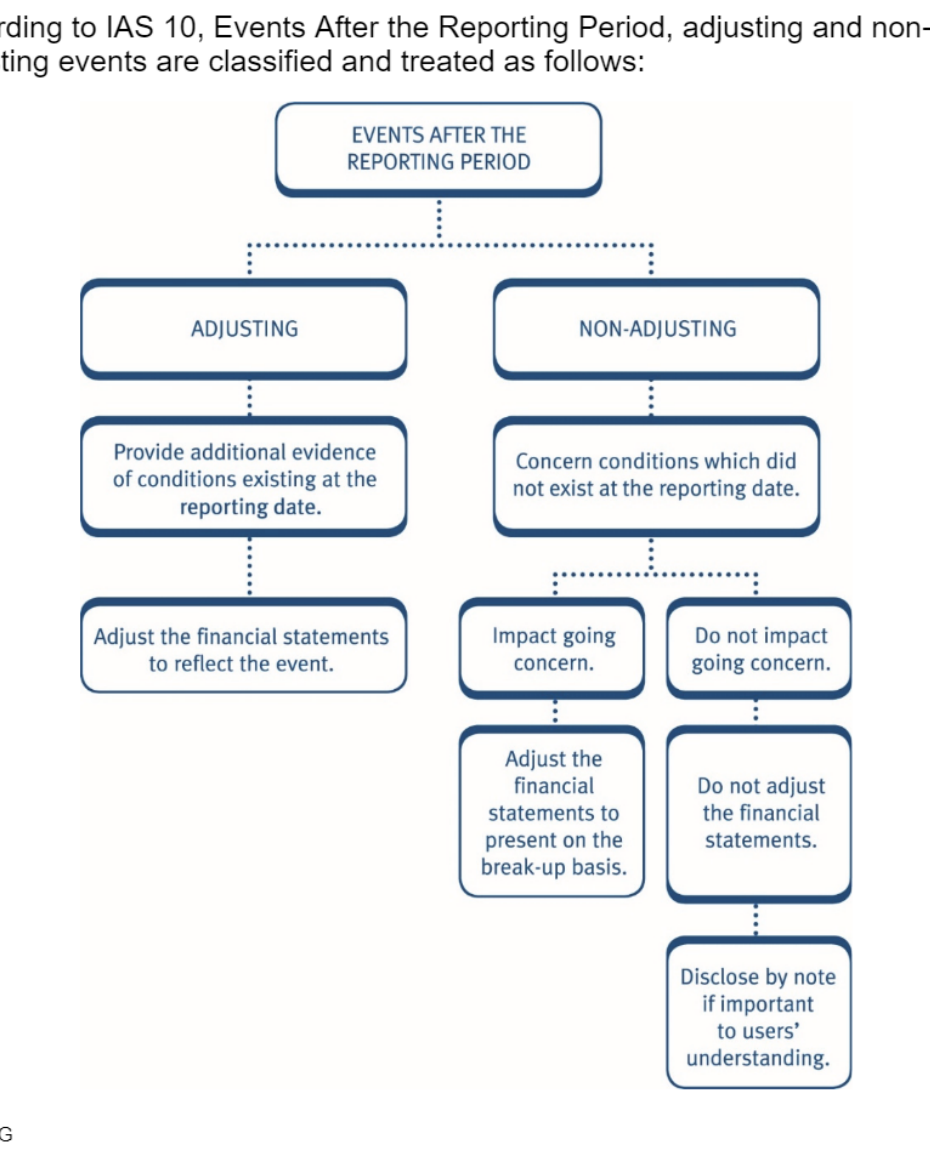
How are adjusting events treated according to IAS 10?
What defines a non-adjusting event under IAS 10?
If a non-adjusting event impacts the going concern status, how should it be treated?
How are non-adjusting events that do not impact going concern treated?
For the disposal of an item of property, plant and equipment, the gain or loss is determined by comparing the proceeds to the _______ net carrying amount.
What is the primary characteristic of adjusting events in financial reporting?
If a material _______ is identified, the financial statements must be amended to reflect the relevant condition.
Examples of adjusting events include: - The settlement after the reporting date of a court case which confirms a _______ - The receipt of information after the reporting date that indicates that an _______ at the reporting date
Examples of adjusting events include: - The _______ of a customer after the reporting date that confirms that a year-end debt is irrecoverable - The _______ after the reporting period at a price lower than cost
What must be done if non-adjusting events are material?
Non-adjusting events arise after the reporting date but do not concern _______.
Examples of non-adjusting events include: - Announcing a plan to _______ - _______
Examples of non-adjusting events include: - Entering into _______ or _______ - Commencing a _______ arising out of events after the reporting date
What information must be disclosed in a note for a material non-adjusting event according to IAS 10?
For material non-adjusting events, IAS 10 requires disclosure of the _______ of the event and an estimate of the _______ or a statement that such an estimate cannot be made.
What standard governs revenue recognition from contracts with customers?
When stating revenue in financial statements, how should sales tax and amounts collected on behalf of others be treated?
Revenue should be stated in financial statements excluding _______ and any amounts collected on _______.
According to IFRS 15, how is revenue defined?
The five-step approach for revenue recognition under IFRS 15 begins by: 1. _______
The second step in the five-step revenue recognition approach is to: 2. _______
The third step in the five-step revenue recognition approach is to: 3. _______
The fourth step in the five-step revenue recognition approach is to: 4. _______
The final step in the five-step revenue recognition approach is to: 5. _______
In the example of the travel agent receiving a $3,000 booking with a 10% commission, what amount should the agent recognise as revenue?
In the example of the travel agent receiving a $3,000 booking with a 10% commission, how is the balance of $2,700 accounted for?
In the case study provided, how many performance obligations did Wad Co identify for the customer purchase?
What is the primary factor that makes revenue recognition variable for credit customers?
When is revenue recognized?
Revenue is recognized over time if the entity's performance creates or enhances an asset that the _______ controls as the asset is created or enhanced.
An entity recognizes revenue over time if the customer simultaneously _______ the benefits provided by the entity's performance as the entity performs its obligations.
What are the two components of the total transaction price of $420 mentioned for the computer and technical support sale?
What is the amount of deferred income as at 31 March 20X2 for the technical support contract?
Revenue is recognized _______ if the entity's performance does not create an asset with an alternative use to the entity and the entity has an enforceable right to payment for performance completed to date.
In the example provided, why is the computer sale revenue recognized on 1 December 20X1?
According to IFRS 15, when must revenue be recognised if it is not recognised over time?
What is the primary condition for an entity to recognise revenue at a point in time under IFRS 15?
Control of an asset refers to the ability to direct the use of, and obtain substantially all of the remaining _______ (inflows or savings in outflows) from the asset.
What does control of an asset include besides the ability to direct its use and obtain benefits?
Indicators of the transfer of control include: - The entity has a present right to _______ for the asset. - The customer has legal _______ to the asset. - The entity has transferred physical _______ of the asset.
Additional indicators of the transfer of control include: - The customer has the significant _______ of ownership of the asset. - The customer has _______ the asset.
When is the transfer of control criteria more likely to apply?
What are the three key disclosure requirements relating to revenue recognition under IFRS 15? 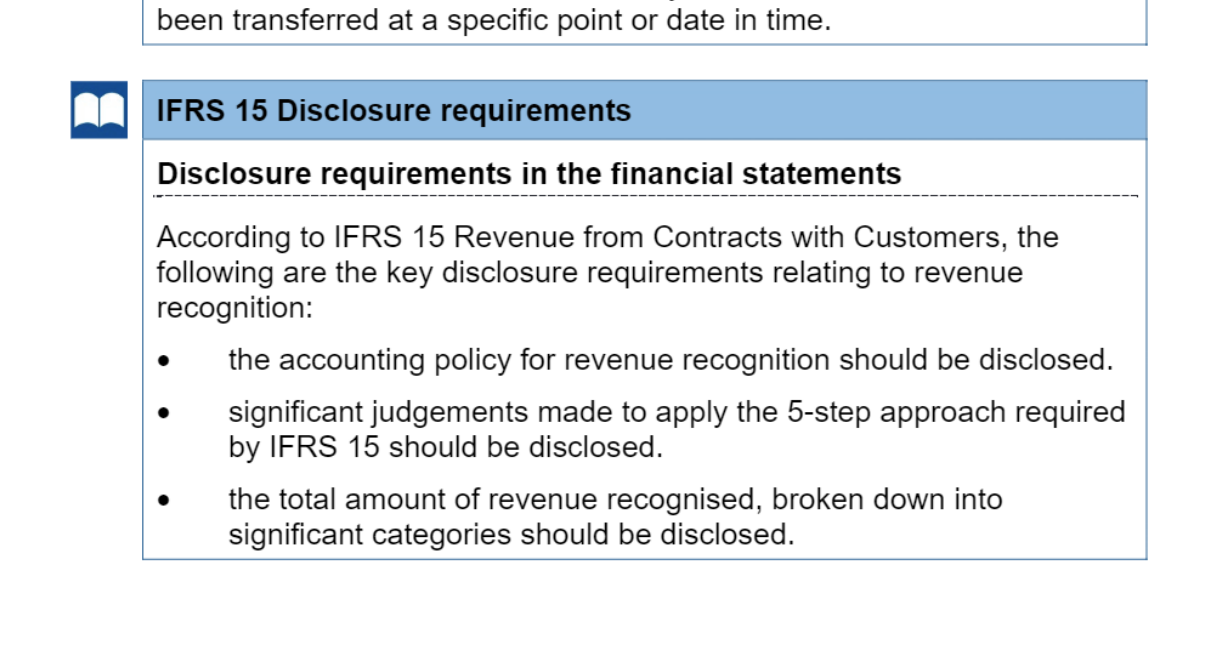
For the transaction with Customer A, how much revenue can AMS Co recognize in its financial statements for the year ended 30 June 20X4? 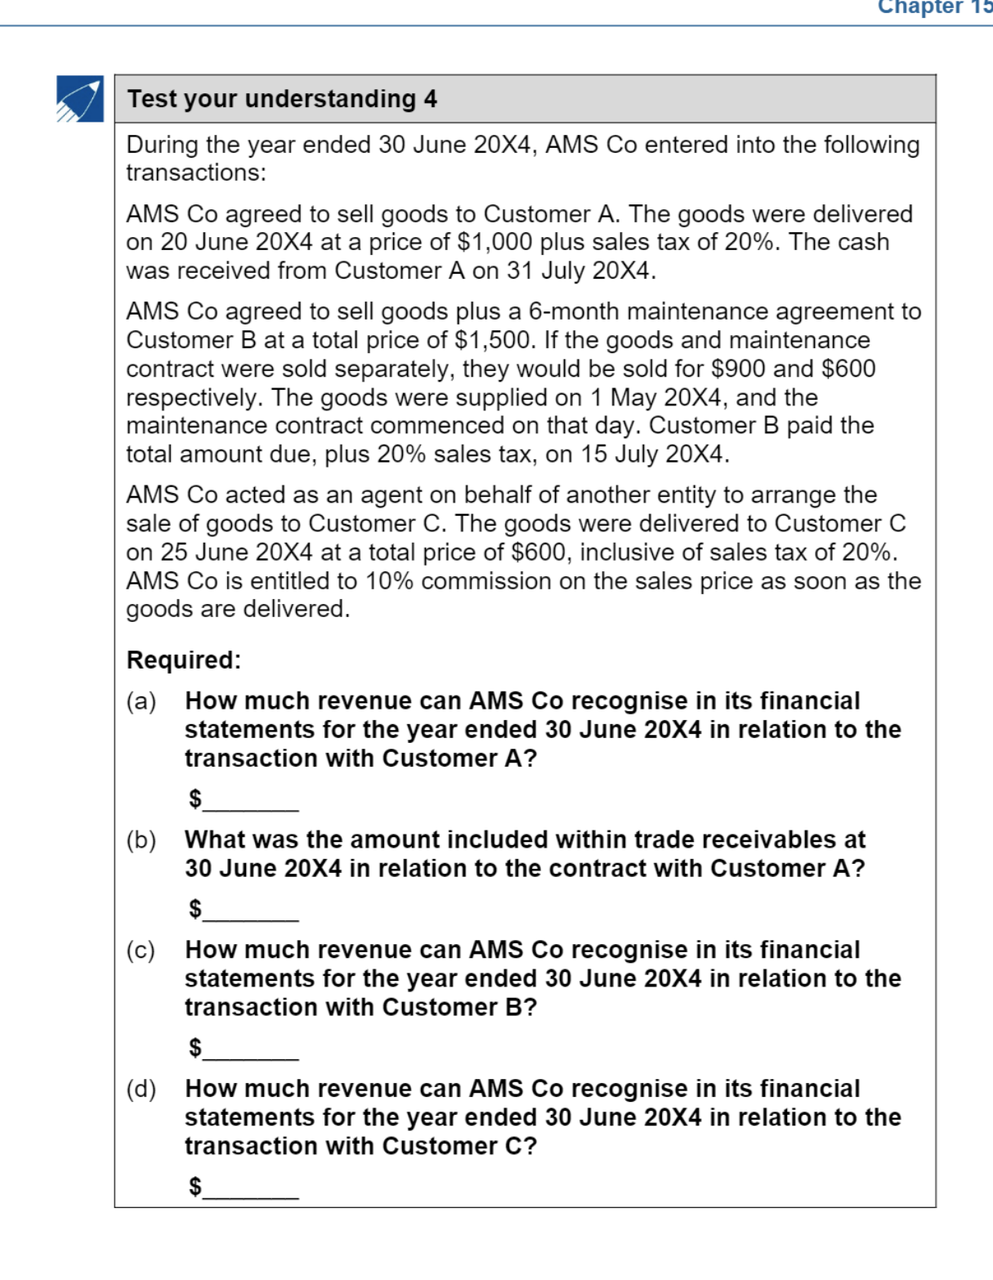
What is the amount included within trade receivables at 30 June 20X4 for the contract with Customer A?
For the contract with Customer B, how much revenue can AMS Co recognize in its financial statements for the year ended 30 June 20X4?
How much revenue can AMS Co recognize for the transaction with Customer C for the year ended 30 June 20X4?
What is the starting point in the preparation process of basic financial statements shown in the flowchart? 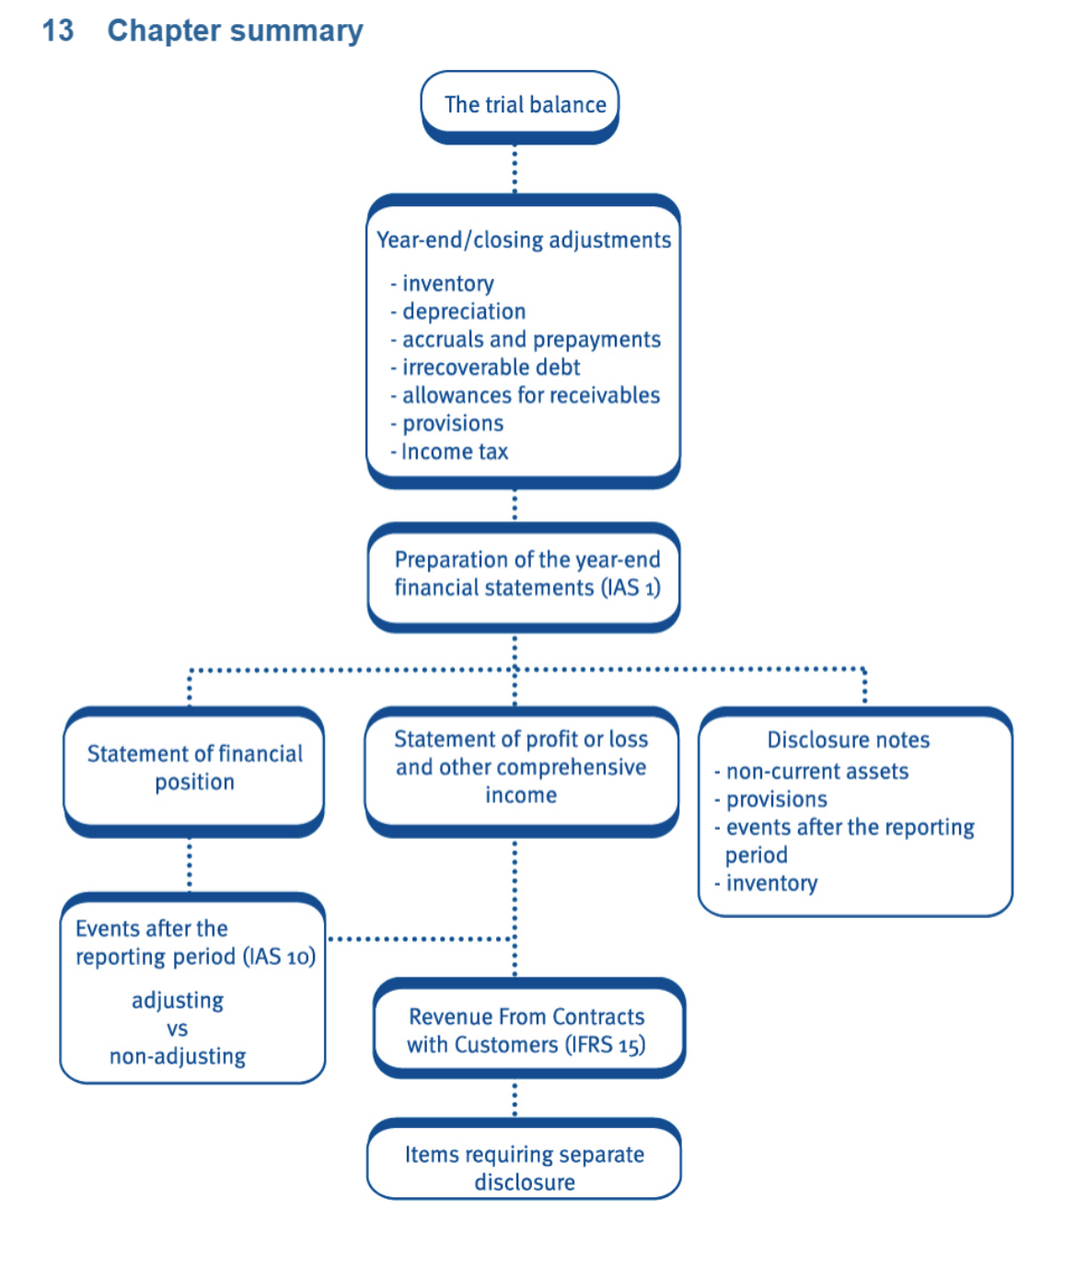
The year-end/closing adjustments process includes: - _______ - _______ - _______ - _______ - _______ - _______ - _______
The preparation of year-end financial statements is governed by _______.
What are the three main components prepared after year-end adjustments, as shown in the flowchart?
Disclosure notes typically include: - _______ - _______ - _______ - _______
Events after the reporting period are categorized as either _______ or _______ and follow standard _______.
Which accounting standard governs revenue from contracts with customers?
What is the formula used to calculate the cost of sales for Penguin Co? 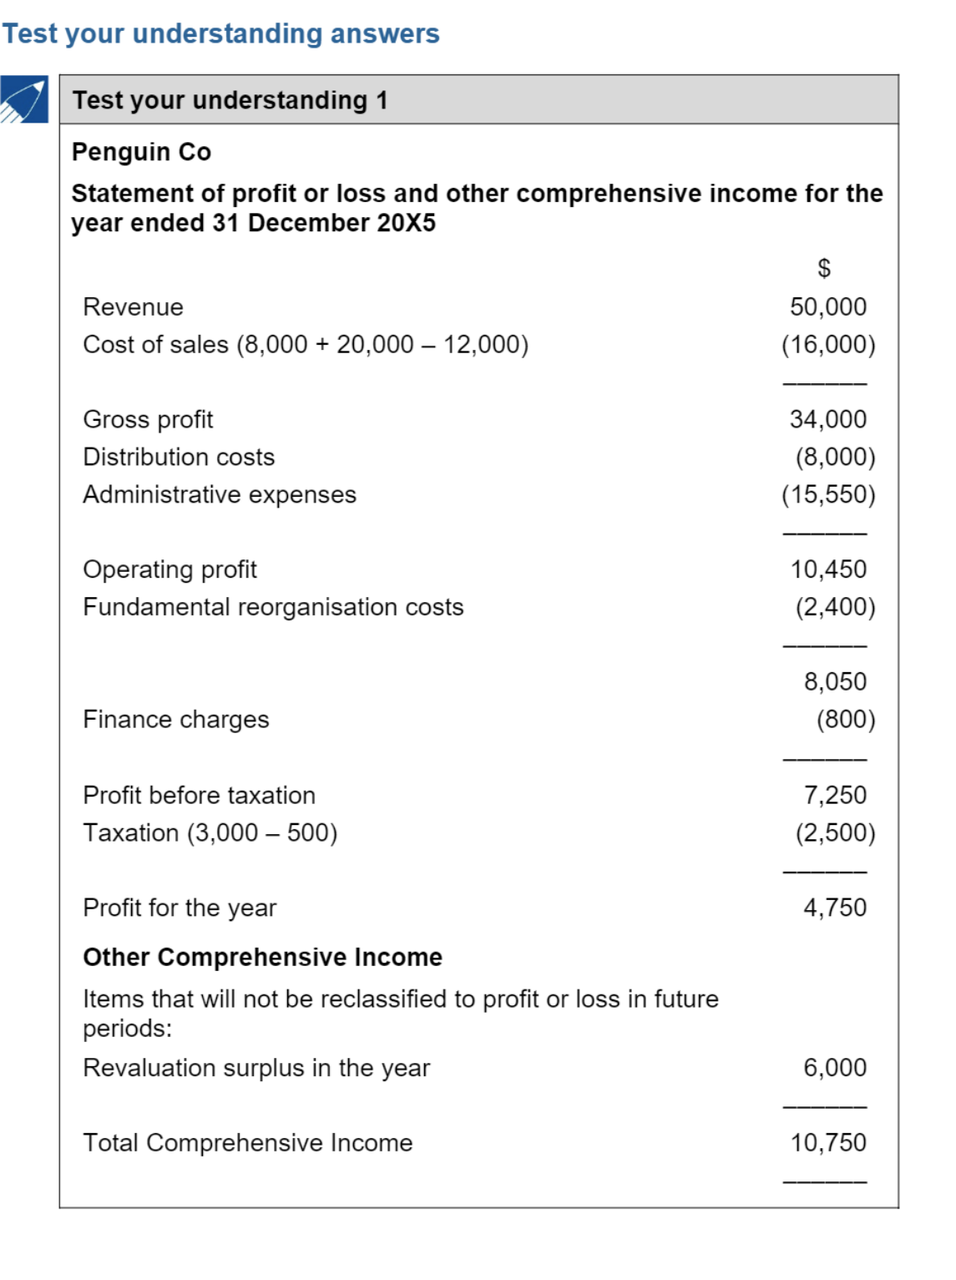
What was the total cost of sales for Penguin Co for the year ended 31 December 20X5?
What is the gross profit for Penguin Co?
What is the operating profit for Penguin Co?
What is the profit before taxation for Penguin Co?
What is the total profit for the year for Penguin Co?
What was the total comprehensive income for Penguin Co?
The revenue for Penguin Co was $_______.
The taxation for Penguin Co was calculated as _______ which equals $_______.
The revaluation surplus in the year for Penguin Co was $_______.
The distribution costs for Penguin Co amounted to $_______.
The administrative expenses for Penguin Co amounted to $_______.
The fundamental reorganisation costs for Penguin Co were $_______.
The finance charges for Penguin Co were $_______.
What is the total value of Tangible assets for Penguin Co. as of 31 December 20X5? 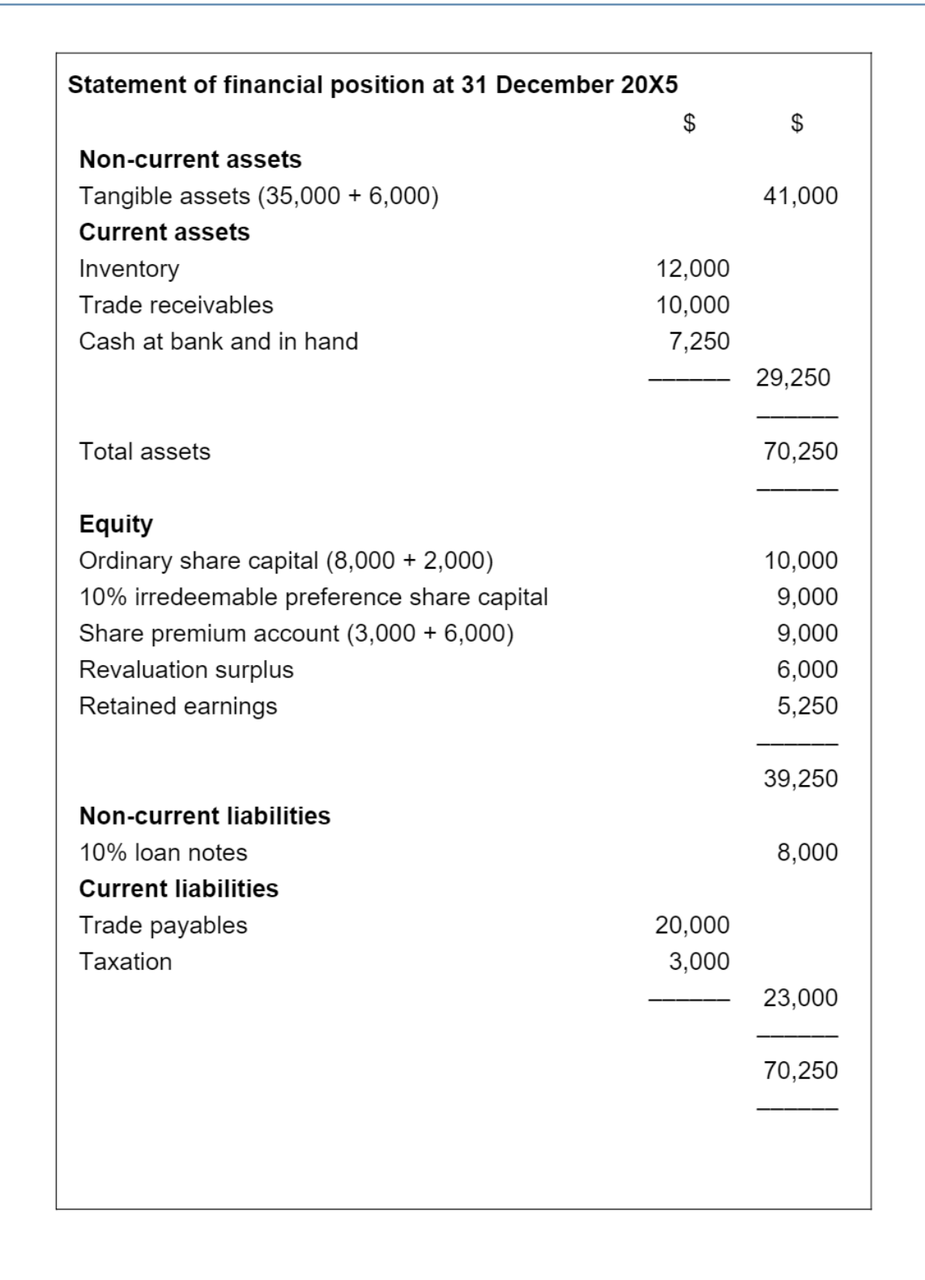
What items are included under Current assets for Penguin Co.?
What is the total value of Current assets for Penguin Co.?
What are the components of Equity for Penguin Co.?
What is the total Equity for Penguin Co. as of 31 December 20X5?
What is listed under Non-current liabilities for Penguin Co.?
What is the value of 10% loan notes for Penguin Co.?
What are the components of Current liabilities for Penguin Co.?
What is the total Current liabilities for Penguin Co.?
The total assets of Penguin Co. as of 31 December 20X5 are _______.
The value of Inventory for Penguin Co. is _______.
The value of Trade receivables for Penguin Co. is _______.
The value of Cash at bank and in hand for Penguin Co. is _______.
What is the primary reason why irredeemable preference share capital is classified as equity?
When 4,000 shares are issued for $8,000, if the nominal value is \(0.50 per share, the share premium per share is _______.
In the statement of changes in equity, how is the revaluation of a building reflected?
In the statement of changes in equity, dividends of $2,500 are deducted from _______.
What is the total equity balance at 31 December 20X5 as shown in the statement of changes in equity?
The issue of 4,000 shares resulting in an $8,000 increase in total equity is split into a $2,000 increase in _______ and a $6,000 increase in _______.
What is the amount of Revenue shown for Ali Page for the year ended 30 June 20X7?
What is the formula to calculate Gross profit in a statement of profit or loss?
What is the calculated Gross profit for Ali Page for the year ended 30 June 20X7?
What is the calculated Operating profit for Ali Page for the year ended 30 June 20X7?
What is the final Profit for the year for Ali Page for the year ended 30 June 20X7?
What are the total Non-current assets for Ali Page at 30 June 20X7?
What are the total Current assets for Ali Page at 30 June 20X7?
What is the Total assets value for Ali Page at 30 June 20X7?
What is the final Capital account balance for Ali Page at 30 June 20X7?
The statement of profit or loss for Ali Page reports an operating profit of _______ and a profit for the year of _______.
The total value of assets for Ali Page at 30 June 20X7 is _______.
Based on the provided Statement of financial position, what is the calculation for Tangible assets?
What is the total value of non-current liabilities shown in the financial notes?
Which items are classified under current liabilities?
The total of current liabilities is _______.
How is the cost of sales calculated in working (W1)?
What is the calculation for the loss on disposal of a non-current asset?
What components are included in Administrative and selling expenses (W2)?
How is the loan interest accrual calculated in (W3)?
The total for Administrative and selling expenses is _______.
Is the sale of year-end inventory at less than cost considered an adjusting or non-adjusting event?
How is a share issue classified regarding year-end adjustments?
Why is a fire in a warehouse generally a non-adjusting event?
Under what condition would a fire in a warehouse necessitate a change to a break-up basis in financial statements?
Is the bankruptcy of a major customer an adjusting or non-adjusting event?
Is the acquisition of a company like Teeny Co an adjusting or non-adjusting event?
Why is the receipt of insurance monies considered an adjusting event?
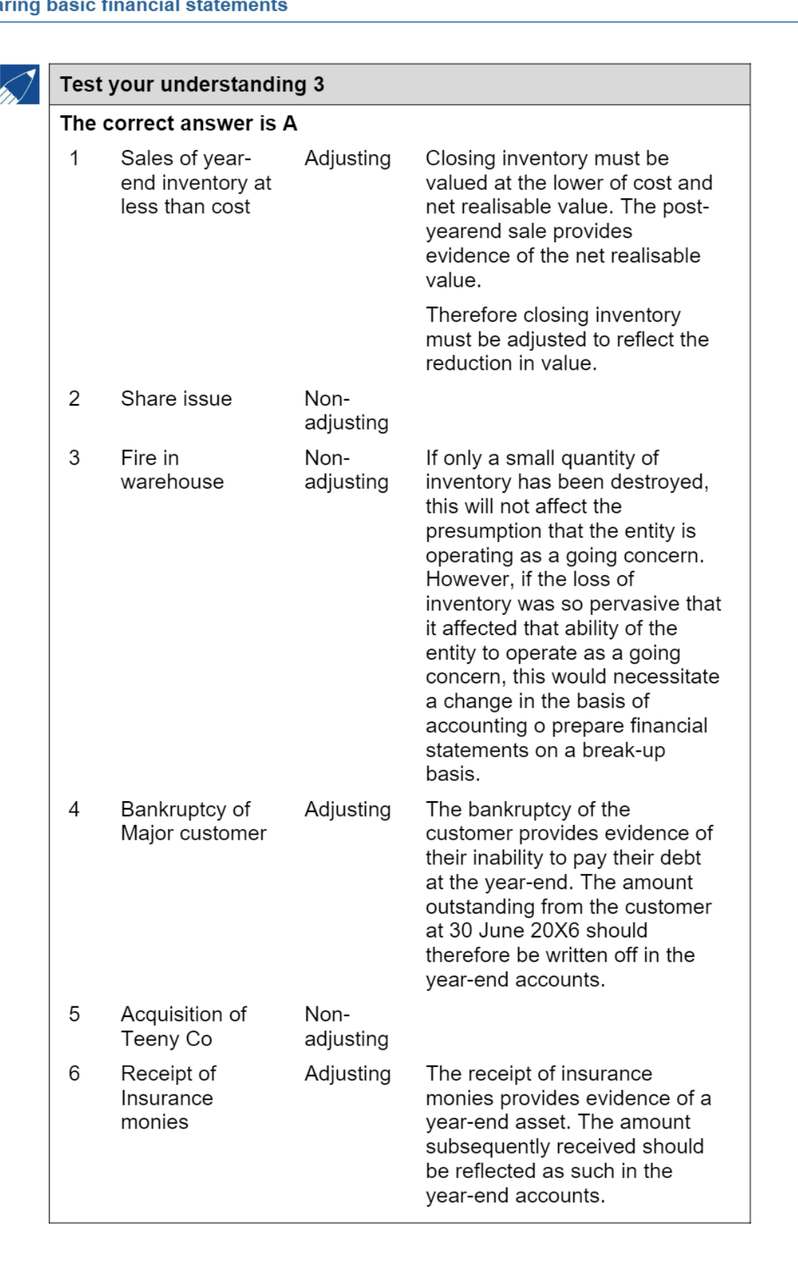
An event that requires a change to the financial statements because it provides evidence of conditions that existed at the year-end is called an _______ event.
What is the key principle regarding the inclusion of sales tax in revenue recognition?
How should trade receivables be calculated in relation to sales tax?
When should revenue from the supply of goods be recognised?
How should revenue from the supply of services be recognised?
How is commission calculated on a transaction of $600 (including 20% sales tax) with a 10% rate?
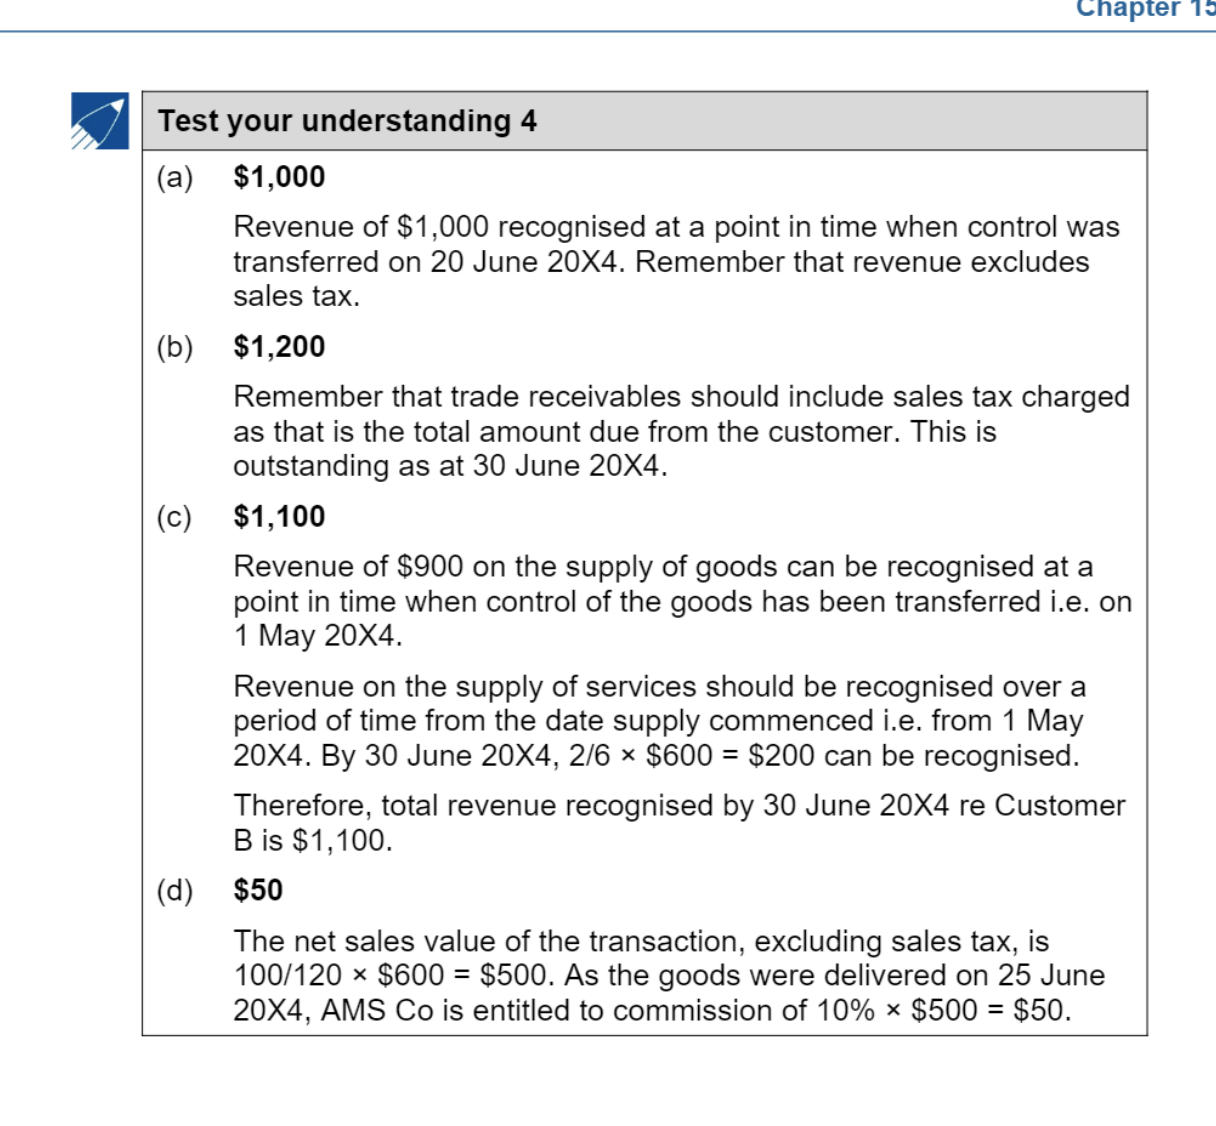
Revenue recognition for the supply of goods occurs at the point in time when _______ of the goods has been transferred.
Revenue for services is recognised over a _______ starting from the date supply commenced.
What is the primary subject matter of Chapter 16?
Techniques used in incomplete record situations include: - Use of the _______ - Use of _______ to calculate missing figures - Use of _______ - Use of given _______ to calculate missing figures
What does PER performance objective PO6 aim to achieve?
What is the primary purpose of the techniques discussed for 'Incomplete records'?
The four main approaches to calculating missing figures in accounting are: - _______ - _______ - _______ - _______
In the context of incomplete records, what does the 'balancing figure approach' typically involve?
Which accounting ratio concepts are mentioned as methods for dealing with incomplete records?
When financial information is incomplete, accountants must use the best available information to _______ any missing figures.
Why are the techniques for handling incomplete records important for future ACCA studies?
What is the basic accounting equation?
How can the accounting equation be expanded to include specific components?
What is the formula to calculate closing retained earnings (RE)?
Work out the profit for Andy Carp Co based on the following: Assets (10,000+3,400=13,400), Liabilities (2,100+1,700=3,800), Share Capital (200), Prior RE (7,350).
The accounting equation is: _______ = _______ + _______.
The formula for _______ is: \(Prior year's RE figure +/– this year's profit(loss) – dividends\).
If a business has very little transaction info, how can they calculate net profit for the year?
What is the primary purpose of the ledger account approach in incomplete records?
In a Receivables ledger account, what are two examples of potential missing figures that could be calculated?
In a Payables ledger account, what are two examples of potential missing figures that could be calculated?
In a Cash at bank ledger account, what are two examples of potential missing figures that could be calculated?
In a Cash in hand ledger account, what are two examples of potential missing figures that could be calculated?
The ledger account approach is used to calculate a _______ in situations involving _______.
Based on the Cash at bank ledger account provided, what item appears on the credit side as a possible missing entry?
What two types of cash transactions might a business need to distinguish between for ledger records?
Looking at the provided templates, what are the entries on the debit side of the Cash at bank ledger account? 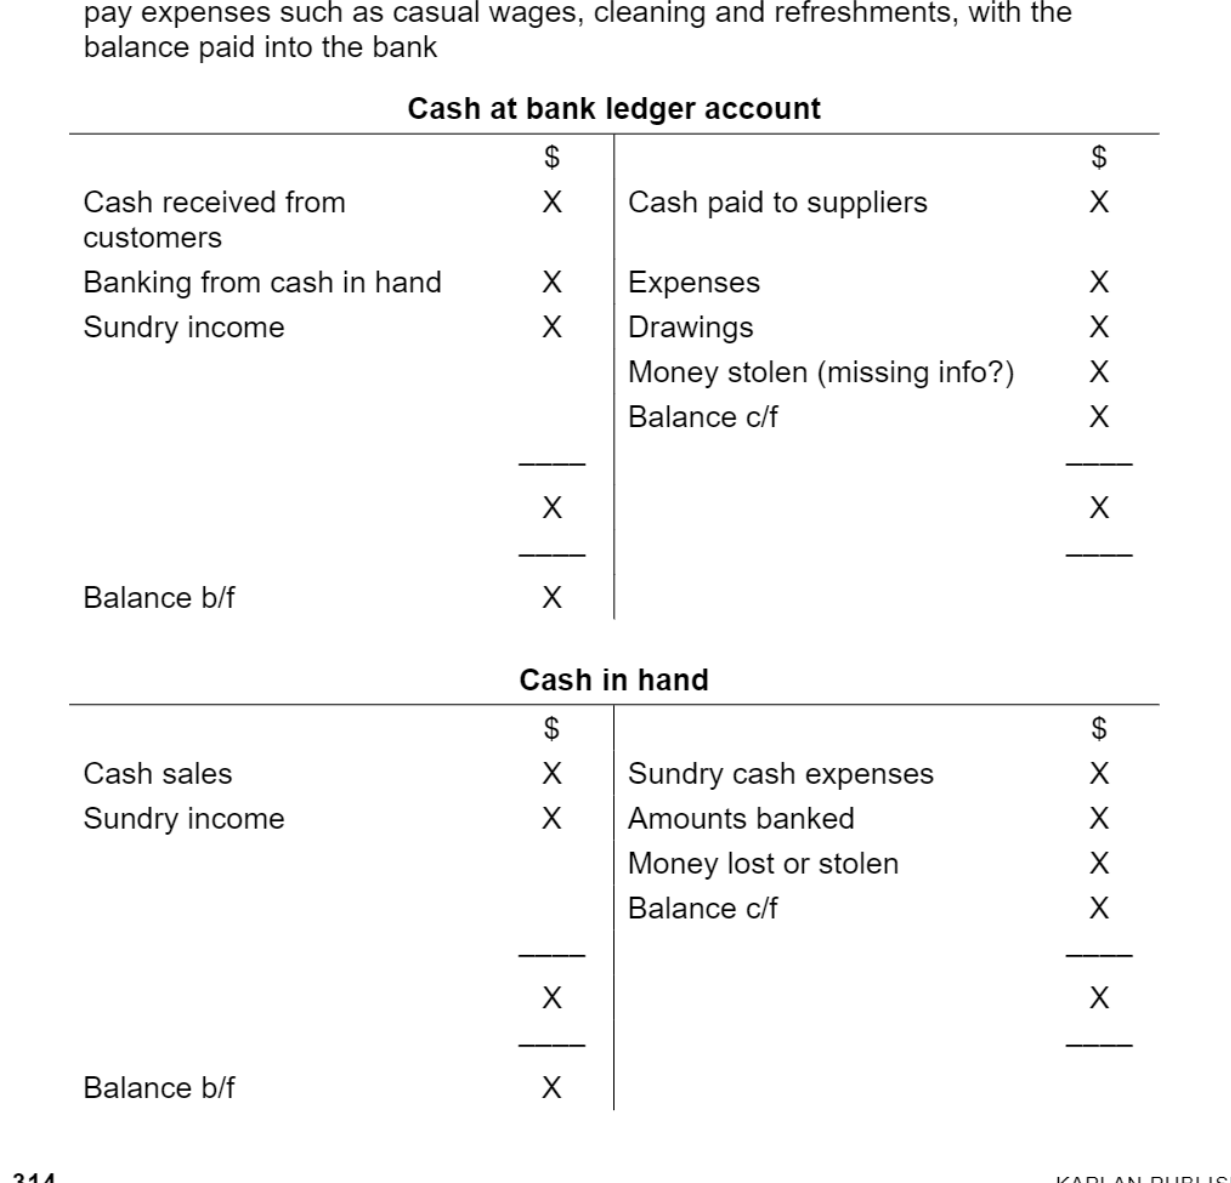
Looking at the provided templates, what are the entries on the credit side of the Cash in hand ledger account?
What is the formula to calculate total sales for the year given accounts receivable information? Use the T-account structure provided. 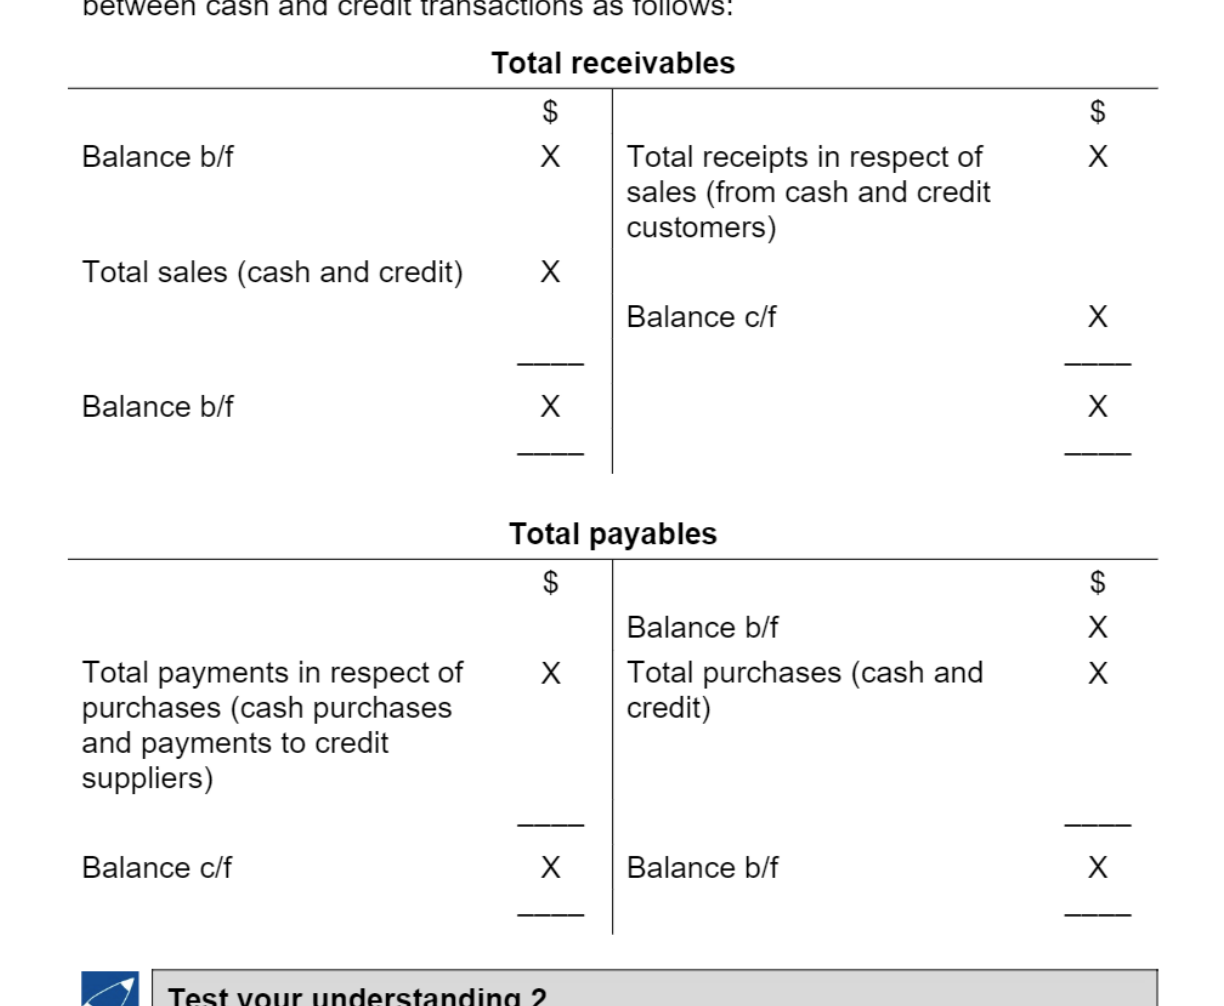
What is the formula to calculate total purchases for the year given accounts payable information?
Solve 'Test your understanding 2': Rubble's business had opening receivables of $30,000, total receipts of $55,000, contras with payables of $3,000, and closing receivables of $37,000. What were the total sales for the year? 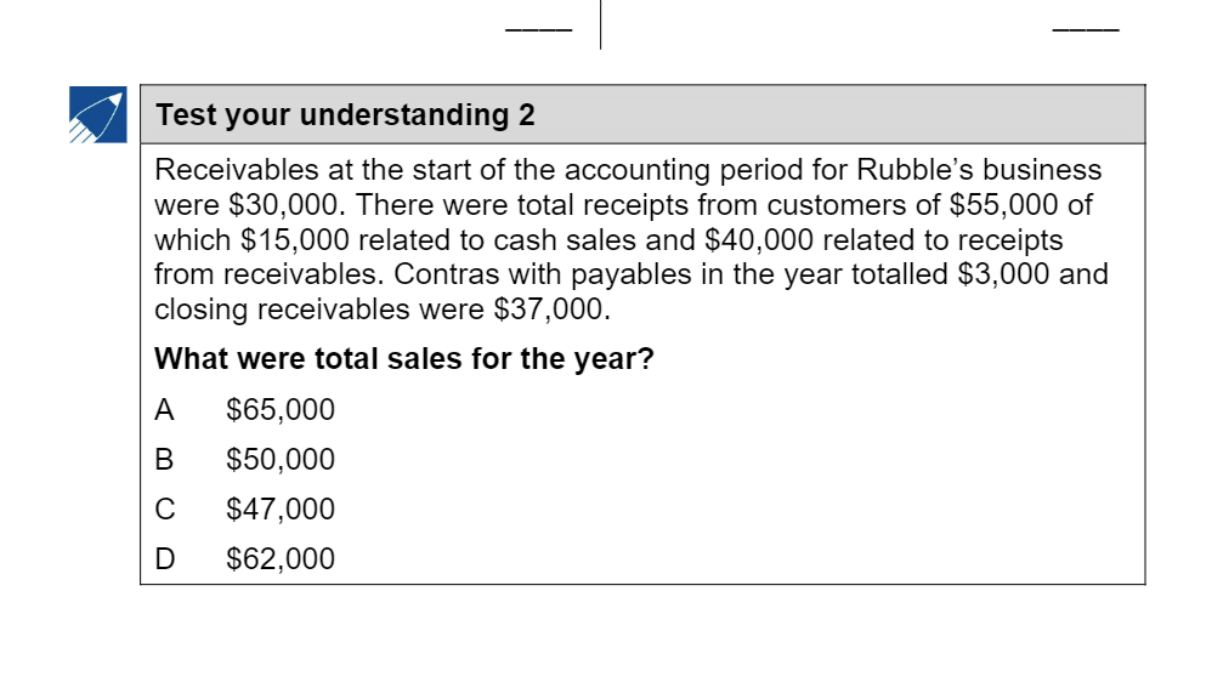
When information cannot be allocated between cash and credit transactions, the _______ or _______ accounts are used to determine total sales or purchases.
What methods can be used to calculate a 'missing' expense figure from a statement of profit or loss? 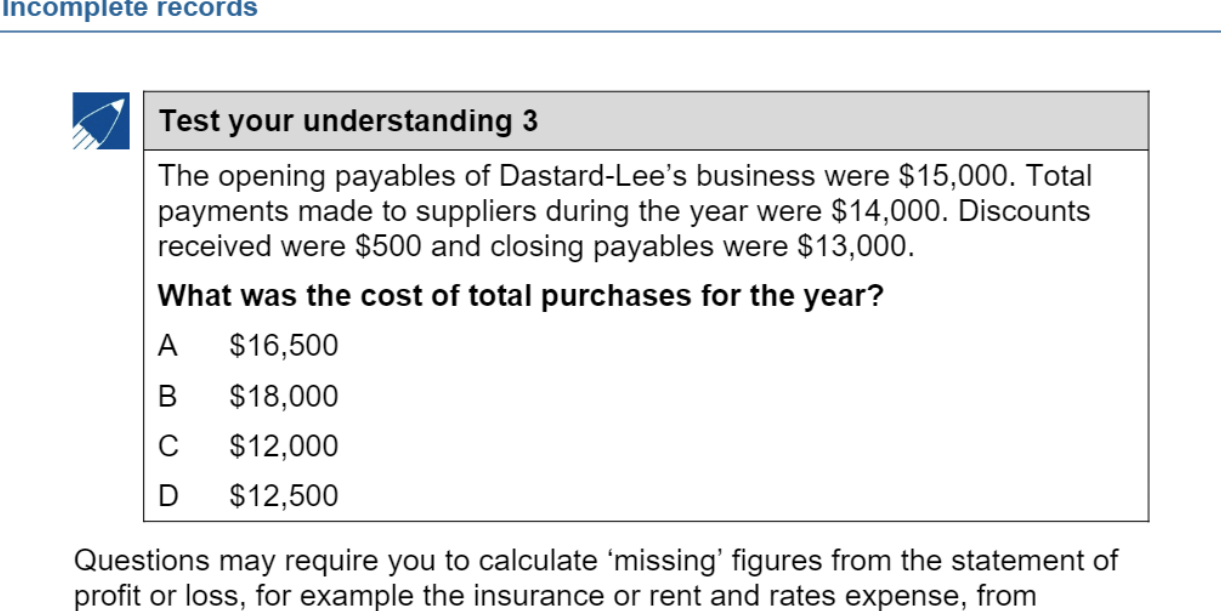
In Test your understanding 3, what is the cost of total purchases for the year? Given: Opening payables $15,000; Total payments $14,000; Discounts received $500; Closing payables $13,000.
Calculate the electricity charge for the year (Test your understanding 4). Accrued 1 Jan: $250; Cash paid: $1,000; Accrued 31 Dec: $300. 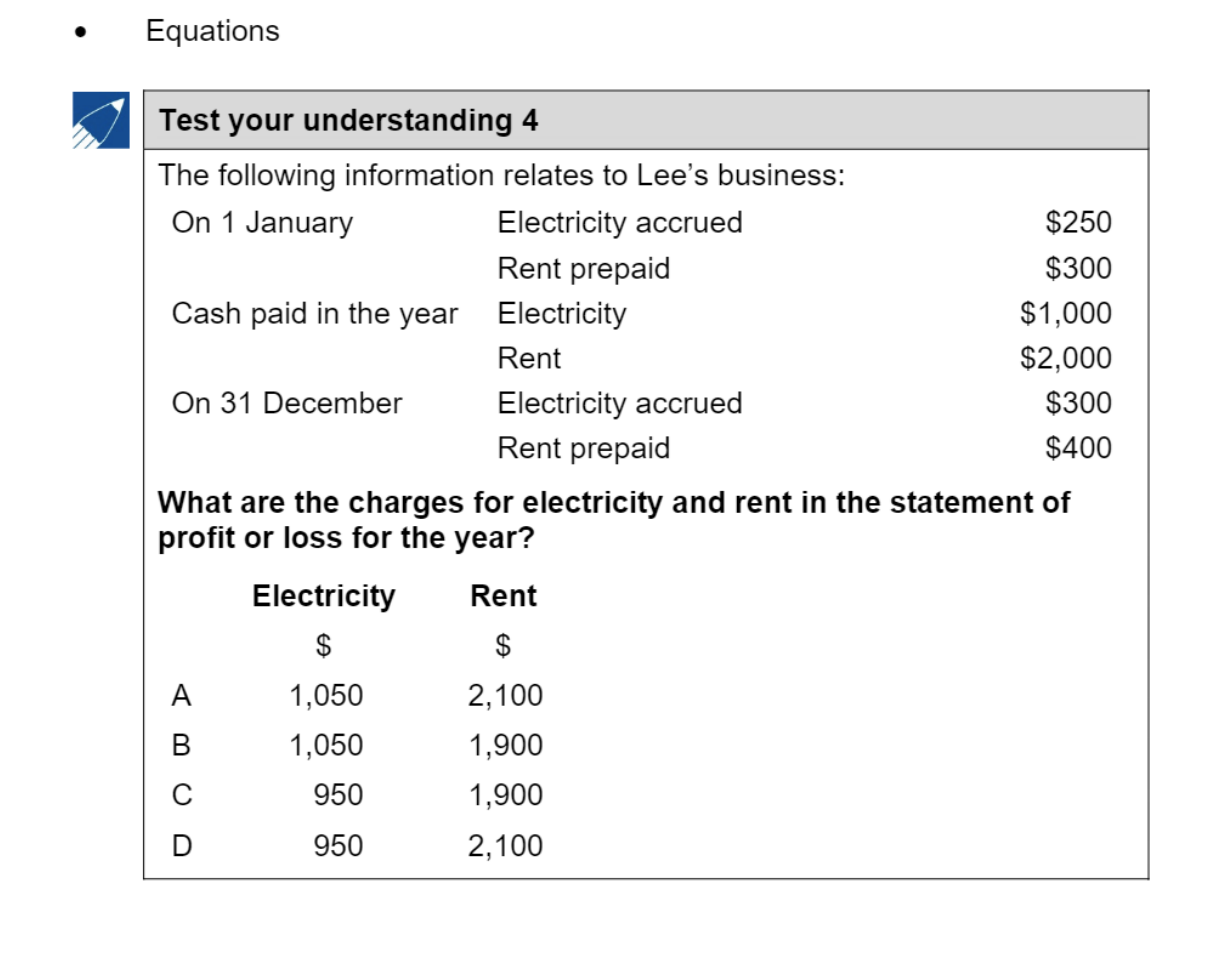
Calculate the rent charge for the year (Test your understanding 4). Prepaid 1 Jan: $300; Cash paid: $2,000; Prepaid 31 Dec: $400.
What is the primary benefit of using bank summaries for reconstructing financial data?
Calculate the total receipts for Jude's bank account if the starting balance was an overdraft of $1,367, total payments were $8,536, and the closing balance was a positive $2,227.
How much cash was received from customers if Dale's business had an opening cash float of $900, closing float of $1,000, banked $10,000, paid out $1,000 in drawings, and paid $2,000 in wages?
What two categories of sales must be combined to calculate total revenue?
Which four figures are required to complete a receivables account?
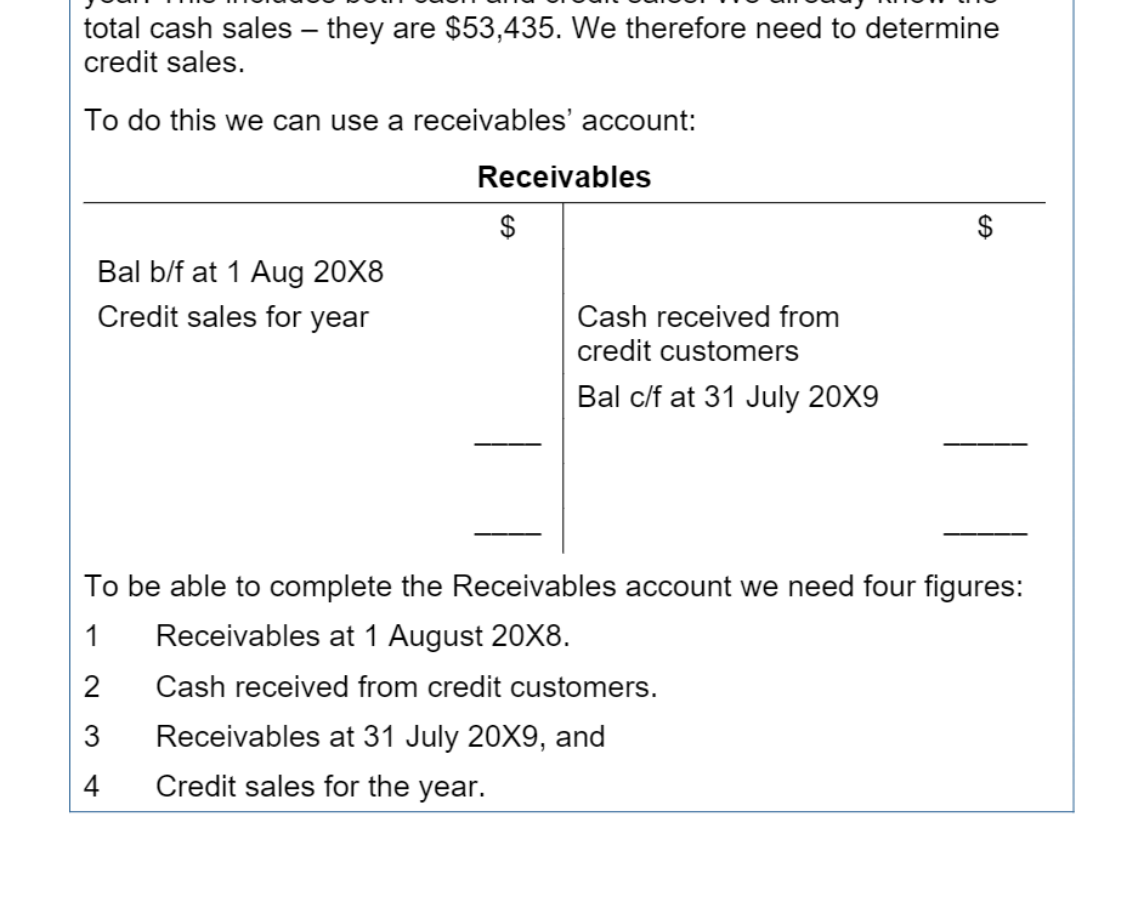 In a receivables account, _______ are recorded on the debit side, while _______ is recorded on the credit side.
When calculating annual revenue, if total cash receipts and cash sales are known, the amount that must be determined to find total sales is _______.
What is the opening receivables figure at 1 August 20X8?
How is the cash received from credit customers calculated when total cash is $245,675 and cash sales are $53,435?
How is the adjusted closing receivables figure calculated when the list/memorandum total is $107,550 and irrecoverable debt is $1,500?
In the receivables account calculation, what is the total of the debit side including opening balance and credit sales?
What items are included on the credit side of the receivables ledger account shown?
How is total revenue calculated based on cash and credit sales?
Based on the provided figures, what is the calculated total revenue?
The opening receivables balance on 1 August 20X8 was _______.
Total receipts from credit customers are calculated as total cash received minus _______.
The closing receivables figure is determined by subtracting _______ from the total receivables per the list/memorandum.
The amount for credit sales is treated as a _______ in the receivables ledger account.
Total revenue is the sum of _______ and _______.
What is the formula for calculating Gross Profit Margin?
What is the formula for calculating Mark-up?
Gross profit can be expressed as a percentage of either _______ or _______.
Pat has sales of $1,000 and a margin of 25%. What is the cost of sales?
Lazim McDuff has a cost of sales of $600 and a mark-up of 25%. What is the related revenue?
What is the relationship between Sales, Cost of sales, and Gross profit for a 20% Margin with $5,000 sales? 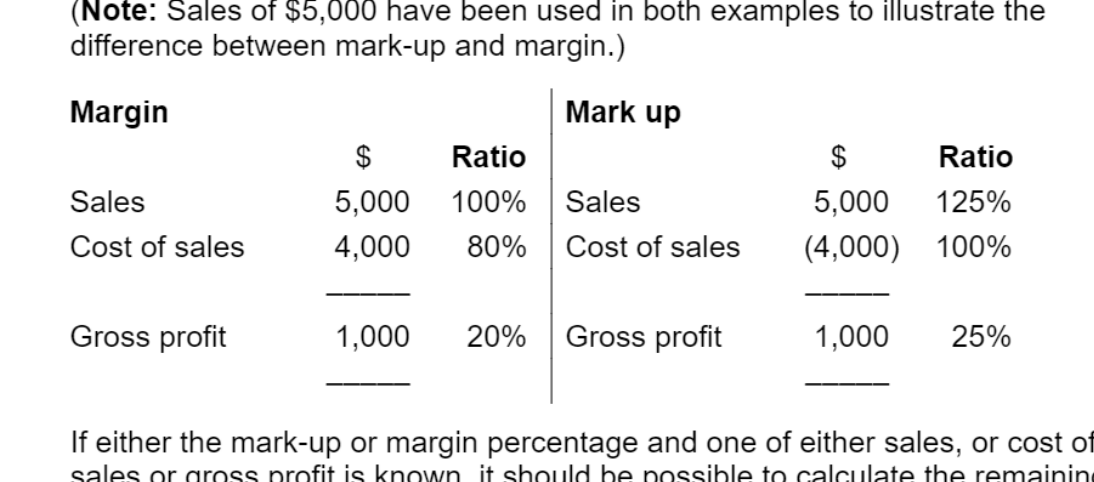
What is the relationship between Sales, Cost of sales, and Gross profit for a 25% Mark-up with $5,000 sales?
Given Jital Longhorn's inventory data (Opening: $800, Closing: $600, Purchases: $2,840), what is the Cost of Sales?
If Jital Longhorn has a 5% margin and a Cost of Sales of $3,040, what is the Sales revenue?
Based on the calculated Sales (\(3,200) and Cost of Sales (\)3,040), what is Jital Longhorn's Gross profit?
The formula to calculate Cost of Sales using inventory is: _______ + _______ - _______.
If a business has a _______ percentage and either sales, cost of sales, or gross profit is known, it is possible to calculate the remaining figures.
What is the basic formula to determine the cost of sales?
In 'Test your understanding 10', what is the cost of inventory lost in the fire?
When recording actual closing inventory in double-entry bookkeeping, the entry is: Dr _______ Cr _______
If lost inventory is insured, the double-entry to remove it from cost of sales and record the claim is: Dr _______ Cr _______
If lost inventory is not insured, the double-entry to remove it from cost of sales and record the loss is: Dr _______ Cr _______
What is the formula to calculate the cost of goods sold when the markup is known?
Calculate the cost of sales for Druva's business given sales of $10,000 and a 25% markup.
Calculate the value of closing inventory for Druva's business before the fire given: opening inventory $2,000, purchases $7,500, and cost of sales $8,000.
What is the journal entry to record the inventory write-off of $1,500?
The cost of sales is calculated as _______ / (1 + _______).
What are the primary methods for handling incomplete records in accounting as shown in the flowchart? 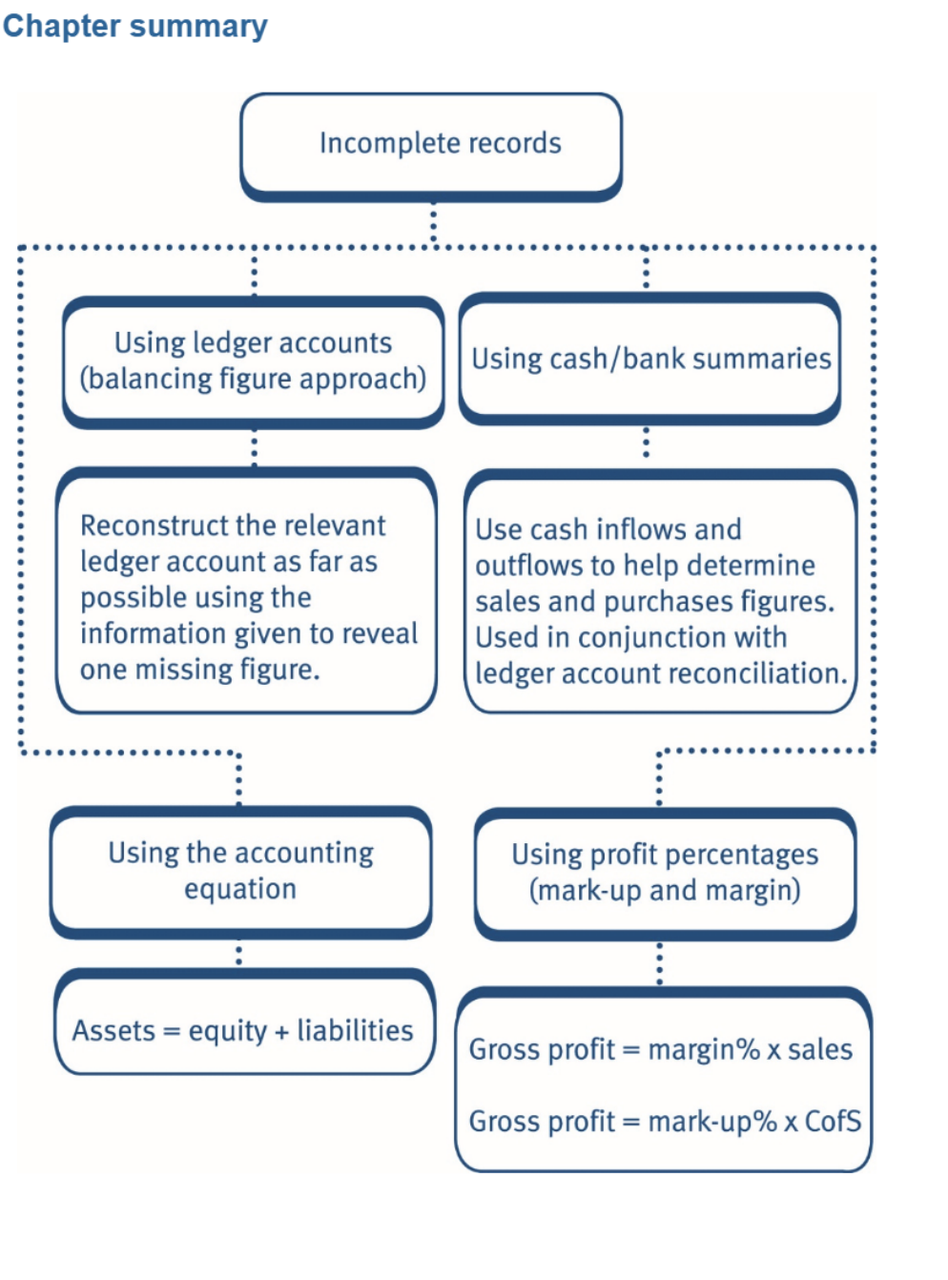
What is the balancing figure approach when dealing with incomplete records?
How are cash/bank summaries utilized for incomplete records?
What is the fundamental accounting equation used to resolve incomplete records?
What is the formula for gross profit using margin percentage?
What is the formula for gross profit using mark-up percentage?
The accounting equation used for handling incomplete records is \(Assets = _______ + _______\).
When using profit percentages, the gross profit formula involving margin is \(Gross\ profit = _______ \times sales\).
When using profit percentages, the gross profit formula involving mark-up is \(Gross\ profit = _______ \times CofS\).
What is the formula to determine total assets based on capital and liabilities?
How do you calculate current year profits using retained earnings?
Given total assets of $13,400, share capital of $200, and other reserves of $3,800, what is the retained earnings value?
Using the provided Receivables ledger, what is the credit sales amount if the total debits equal $80,000 and the starting balance b/f is $30,000?
The formula for calculating current year profits is: Current year profits = _______ - _______.
In a receivables ledger, 'Contras with payables' are recorded on the _______ side.
What is the formula for calculating total sales from credit and cash sales?
When preparing a total receivables account, what are the primary debit entries?
When preparing a total receivables account, what are the primary credit entries?
How is the balance c/f for total payables calculated based on the provided table?
In the total payables account, the credit side includes the opening balance _______ of \(15,000 and the credit purchases of _______.
Calculate the electricity expense for the statement of profit or loss.
Calculate the rent expense for the statement of profit or loss.
Based on the Bank account ledger in 'Test your understanding 5', what is the value of the 'Balance c/f' at the end of the period?
What is the total of the receipts side in the Bank account ledger example?
In the Cash in till ledger, the 'Balance b/f' is $_______ and the total receipts are $_______.
According to the 'Cash in till' ledger in 'Test your understanding 6', what were the payments made for Bank, Drawings, and Wages respectively?
What is the formula for calculating 'Gross profit' shown in 'Test your understanding 7'?
If Sales are $1,000 and Gross profit is $250, what is the 'Cost of sales'?
The 'Balance c/f' in the Cash in till account is _______.
How is gross profit calculated when given sales and a gross profit margin percentage? Refer to Test your understanding 8.
What is the formula for calculating cost of sales in a trading account?
In a trading account, the gross profit margin is calculated as (_______ / _______) * 100.
How should 'Inventory lost' be treated in a trading account calculation?
Using the data in Test your understanding 10, the cost of sales is calculated by adding _______ to _______ and then subtracting _______ and _______.
In the context of 'Test your understanding 11', how is uninsured inventory lost by fire recorded in the profit or loss account?
When recording uninsured inventory destroyed by fire, the accounting entry involves a debit to the _______ account and a credit to the _______ account.
What is the calculation for the Cost of Sales in 'Test your understanding 11'?
In the provided example, the Gross profit is determined by subtracting the Cost of Sales of _______ from the Sales of _______, resulting in a profit of _______.
What is the primary difference between profit and cash flows?
The two methods used to calculate cash flows from operating activities are the _______ and the _______.
The PER performance objective _______ relates to the preparation and review of financial statements in accordance with legal and regulatory requirements.
What are two key aspects users need to evaluate regarding a statement of cash flows?
What are the four key stages in the process of dealing with a statement of cash flows?
The primary stages for dealing with a statement of cash flows are: - _______ - _______ - _______ - _______
Why might a profitable entity still fail to survive?
An entity may be _______ but still fail if it has insufficient _______ available to pay its short-term liabilities.
What is the primary difference in the calculation basis between profit and cash flow?
Profits are calculated using the _______ basis, meaning that _______ is recognized before cash is necessarily received.
What is an example of an expense that is recognized in profit calculations but has no cash impact?
Which accounting standard requires corporate entities to include a statement of cash flows in their annual financial statements?
What are two key measures of the financial health of an entity related to cash flow?
Liquid assets that can be used to settle short-term debts include _______, _______, and _______.
Current liabilities that need to be settled by an entity include _______, _______, _______, and _______.
What are the potential negative consequences if management fails to maintain sufficient current assets to pay liabilities as they fall due?
To ensure effective cash flow balance, management must consider _______ and maintain an effective system of _______.
Besides maintaining an effective credit control system, what else must management balance regarding the entity's financial structure?
One objective of IAS 7 is to report an entity's _______ and _______ for a period.
IAS 7 aims to provide information that assists in the assessment of an entity's _______, _______, and _______.
What is the primary reason why a statement of cash flows is needed?
What does a statement of cash flows help assess regarding liquidity and solvency?
What does financial adaptability in the context of cash flows refer to?
Why are adequate future cash flows essential for an entity in the long term?
The statement of cash flows highlights how cash is being generated through _______, _______, or _______ activities.
Why are cash flows considered more objective than profit calculations?
What is a major limitation regarding the data used in a statement of cash flows?
Are interpretations of the statement of cash flows provided within the financial accounts?
How are non-cash transactions handled in a statement of cash flows?
Which accounting standard governs the preparation of the statement of cash flows?
What are the three main sections of a statement of cash flows?
The statement of cash flows categorizes activities into operating, _______, and _______ activities.
Is interest paid typically included under operating, investing, or financing activities in the statement of cash flows?
Where are 'proceeds of sale of equipment' reported on the statement of cash flows?
Are dividends paid categorized under operating, investing, or financing activities?
How is the net increase or decrease in cash calculated at the end of the statement of cash flows?
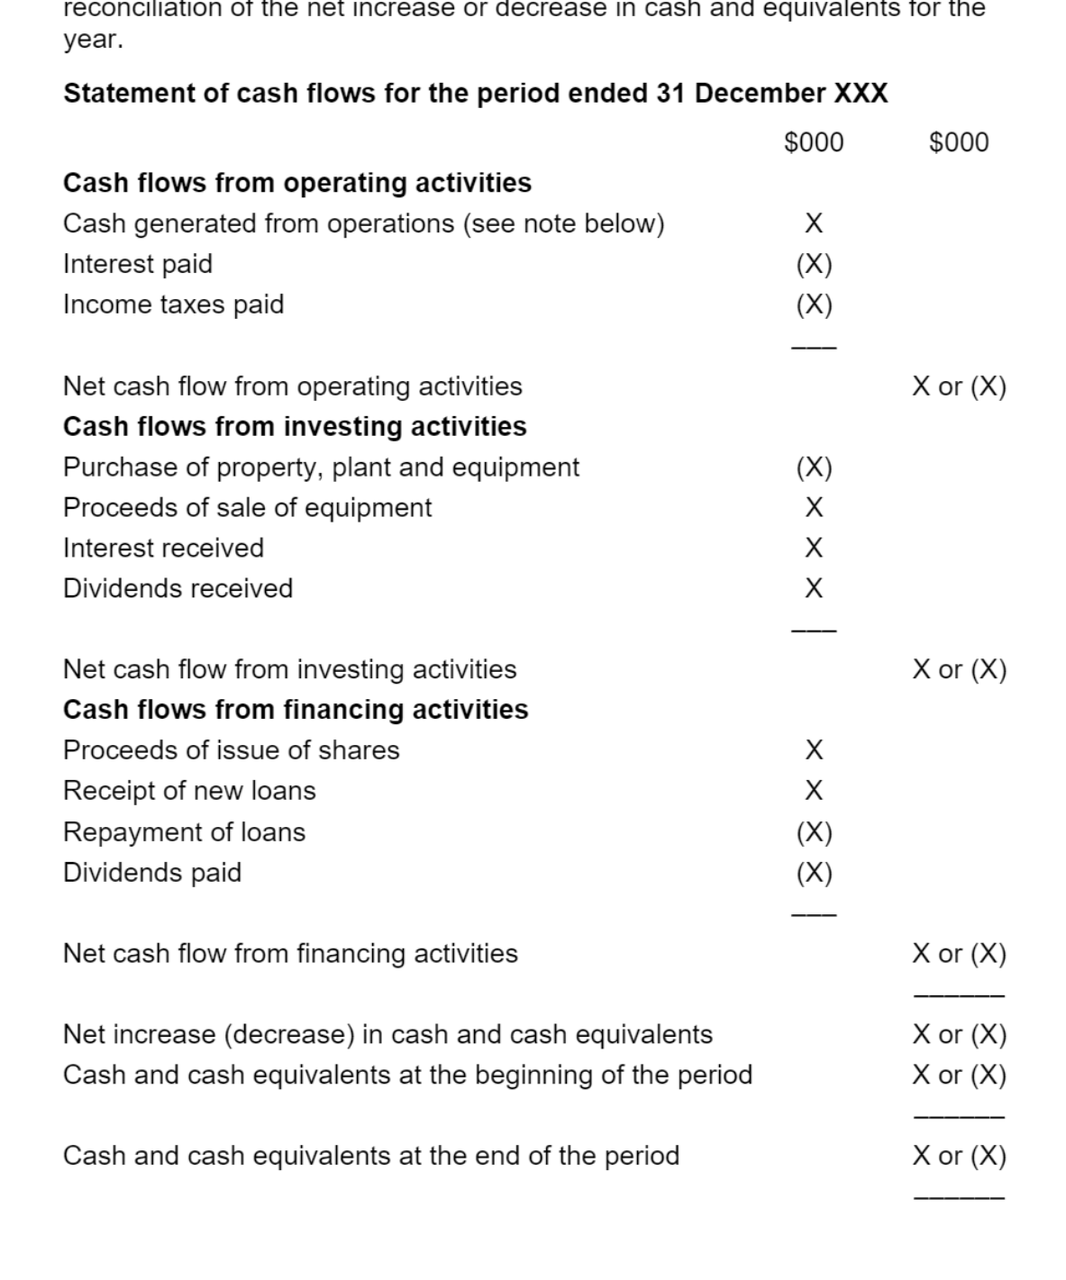 In the statement of cash flows, _______ are classified as an operating activity.
Receipt of new loans and proceeds from the issue of shares are reported under _______.
Dividends received are classified as _______.
What is the accounting definition of 'Cash'?
What are 'Cash equivalents'?
How does IAS 7 define 'Cash flows'?
_______ are the principal revenue-producing activities of the entity.
What is 'Cash generated from operations'?
How is 'Net cash flow from operations' calculated from 'Cash generated from operations'?
_______ are cash spent on non-current assets, proceeds of sale of non-current assets and income from investments.
_______ include the proceeds of issue of shares and long-term borrowings made or repaid.
What represents the net increase or decrease in cash and cash equivalents during the year?
The two methods used to calculate net cash flow from operating activities are the _______ method and the _______ method.
What are the two methods of presenting cash flows from operations?
Why do most entities avoid using the direct method for presenting cash flows?
What are the two sources from which gross cash flows for the direct method can be derived?
When using summary account workings for the direct method, what three specific items are typically analyzed to derive cash flows? - Sales to derive _______ - Purchases to derive _______ - Wages to derive _______
If you are presenting an example using the direct method, what visual aid summarizes the accounting information involved in Cash Co's statement of financial position?
What is the amount of share capital for Cash Co in 20X7? 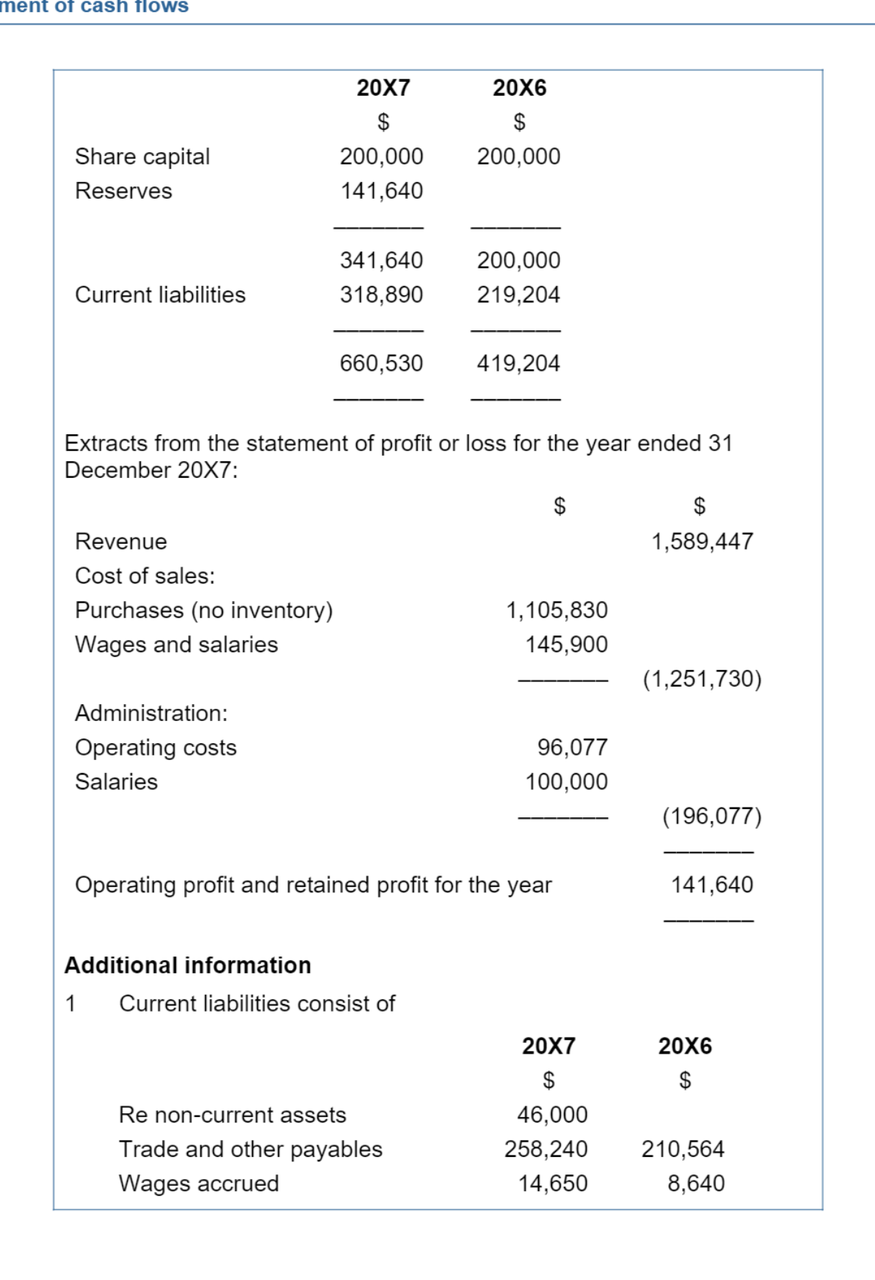
What is the operating profit for the year ended 31 December 20X7?
What are the components of current liabilities for Cash Co in 20X7?
The total value of current liabilities for Cash Co in 20X7 is _______.
What is the total value of wages and salaries recorded in the profit or loss extract for 20X7?
The amount for administration salaries in 20X7 is _______.
What is the figure for purchases (no inventory) in 20X7?
What is the net cash inflow from operating activities for the year ended 31 December 20X7?
How is the amount of cash received from customers determined when calculating operating cash flows?
How is cash paid to suppliers determined in the operating activities calculation?
When calculating cash paid to suppliers for operating activities, _______ purchase invoices totaling $_______ are excluded from the payables ledger.
The net cash flow from operating activities calculation includes: - Cash received from customers: $_______ - Cash payments to suppliers: (_______) - Cash paid to employees: (_______)
Based on the ledger account shown, what is the total amount of net wages paid?
In the Wages and salaries ledger account, the balance brought forward (b/f) is \(_______ and the balance carried forward (c/f) is \(_______.
What is the change in trade receivables for the year ended 30 September 20X8?
What is the change in trade payables for the year ended 30 September 20X8?
Calculate the movement in accrued wages expense for the period.
Calculate the change in interest payable.
Calculate the change in income tax payable.
The note regarding the contra between trade receivables and trade payables states that it amounts to \(_______ and it has _______.
What is the starting point for calculating cash flows from operating activities using the indirect method?
Why is depreciation added back to profit before tax in the indirect method?
How is a loss on the disposal of non-current assets treated in the indirect method?
How is a gain on the disposal of non-current assets treated in the indirect method?
Why is interest payable expense added back to profit before tax when using the indirect method?
Under the indirect method, an increase in inventory is _______ from profit before tax, while a decrease in inventory is _______ to profit before tax.
In the indirect method, an increase in trade receivables is _______ from profit before tax, and a decrease in trade receivables is _______ to profit before tax.
In the indirect method, an increase in trade payables is _______ to profit before tax, whereas a decrease in trade payables is _______ from profit before tax.
What information is required to prepare a statement of cash flows?
What was the total value of non-current assets for Geronimo as of 31 December 20X6?
What is the total value of current assets for Geronimo as of 31 December 20X5?
How much was the accumulated depreciation for Geronimo in 20X6?
What was the total amount of share capital for Geronimo as of 31 December 20X6?
What was the total value of revaluation surplus for Geronimo as of 31 December 20X5?
What was the value of the loan for Geronimo in 20X6 and 20X5?
Calculate the net book value of non-current assets for Geronimo in 20X6.
The total assets for Geronimo as of 31 December 20X6 were _______.
As of 31 December 20X6, Geronimo had a trade payable amount of _______ and a tax payable amount of _______.
The retained earnings for Geronimo increased from _______ in 20X5 to _______ in 20X6.
Provide the total figure for Equity and liabilities in 20X6 and 20X5.
What is the operating profit for Geronimo for the year ended 31 December 20X6?
How is the cash flow for interest and income taxes paid calculated?
The _______ for Geronimo for the year ended 31 December 20X6 was $113,000.
The net profit for the year for Geronimo was _______.
What are two examples of items that may be included in cash flows from operating activities?
Operating expenses for Geronimo include a loss on disposal of non-current assets of _______.
What was the original cost of the plant disposed of by Geronimo?
What was the accumulated depreciation on the plant disposed of by Geronimo?
The _______ is a technique used to calculate the cash flow generated from operations.
When using a T-account to determine cash paid for interest or tax, what are the components of the debit side (left side) and credit side (right side)?
How is the cash paid figure derived in a T-account working for interest or tax?
Cash flows from _______ include interest received, dividends received, and proceeds of disposal of _______.
What is a major cash outflow example within investing activities?
Under IAS 7, how might interest and dividends received be classified?
Whatever _______ is adopted for interest and dividends received, it must be applied _______ from one accounting period to another.
What figures are required to calculate interest and dividends received?
What is the recommended tool for calculating complex cash flow items like interest or dividends in a statement of cash flows?
In a T-account for interest receivable, what does the balancing figure typically represent?
To calculate cash flows related to property, plant, and equipment, one should use T-accounts for the _______, the _______, and the _______ (where relevant).
When there is a revaluation of an asset, where should the uplift in value be recorded in the T-account?
What is the heading under which dividends and interest received are shown in a statement of cash flows?
Data from financial statements should be entered into T-accounts to find required cash flows, which are often found as _______.
What should be used when there is insufficient detail to produce separate asset and accumulated depreciation accounts?
What is the cash outflow to purchase PPE equivalent to in an NCA carrying amount T-account?
Cash inflows from financing activities include proceeds of the _______ and proceeds of receipt of _______.
Cash outflows from financing activities include: - repayment of _______ - _______ - _______
According to IAS 7, where can interest paid be classified in the statement of cash flows?
What is the crucial requirement for classifying interest paid in the statement of cash flows under IAS 7?
Which two accounts are compared to calculate the proceeds from a share issue?
How should a bonus issue made during the year be treated when calculating cash flows from a share issue?
How is the cash flow from loan proceeds or repayments derived?
If there is a fall in the loan balance outstanding, it indicates that the loan has been _______.
If there is an increase in the loan balance outstanding, it indicates that a _______ during the year.
How is the amount of dividends paid usually identified in financial statements?
Under IAS 7, how can dividends paid be classified in the statement of cash flows?
Which classification is most commonly used for dividends paid in the statement of cash flows?
What is the requirement for 'Test your understanding 6' regarding Geronimo's statement of cash flows? 
What are the three main categories typically included in a statement of cash flows?
What items are typically included under 'Cash flows from operating activities' in a statement of cash flows?
What items are typically included under 'Cash flows from investing activities' in a statement of cash flows?
What items are typically included under 'Cash flows from financing activities' in a statement of cash flows?
The _______ is calculated by summing the net cash flows from operating, investing, and financing activities.
The _______ is calculated as the sum of the net increase in cash and cash equivalents and the _______.
What is the total carrying amount (CA) of Plant and Buildings for Algernon as of 31 December 20X7?
What was the total value of Investments at cost for Algernon on 31 December 20X7?
What was the total value of land held by Algernon on 31 December 20X7?
What was the Revaluation surplus (land) reported by Algernon on 31 December 20X7?
What was the value of 10% Loan notes for Algernon on 31 December 20X7?
The carrying amount for buildings in 20X6 was _______, while in 20X7 it increased to _______. 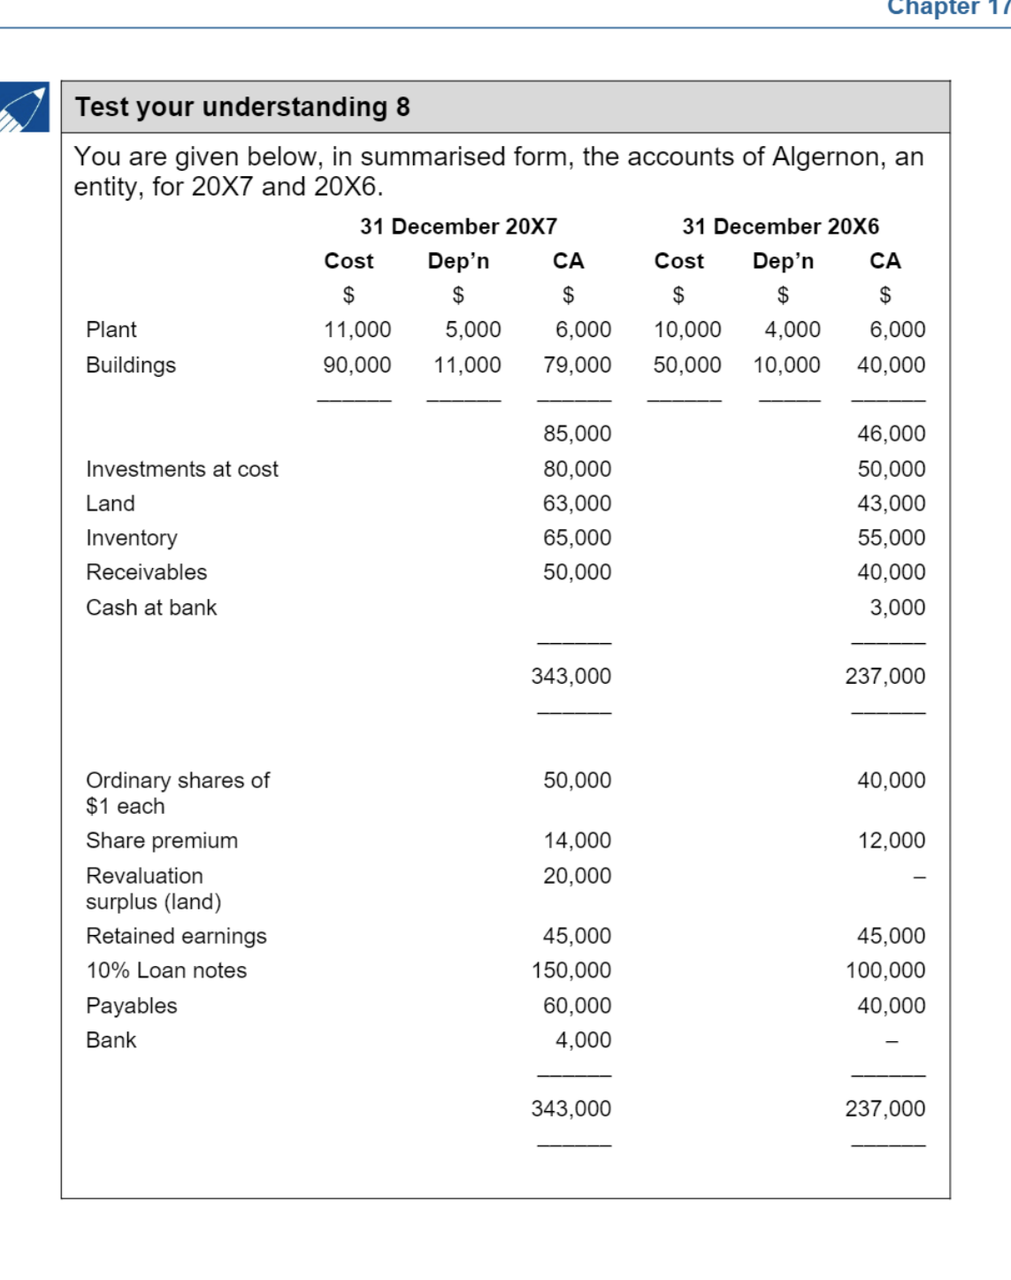
The ordinary shares for Algernon were valued at _______ on 31 December 20X7.
Payables for Algernon increased from _______ in 20X6 to _______ in 20X7.
What is the total balance sheet footing for Algernon for both 20X7 and 20X6?
What was the Cash at bank value for Algernon on 31 December 20X6?
What is the net profit for Algernon for the year ended 31 December 20X6? 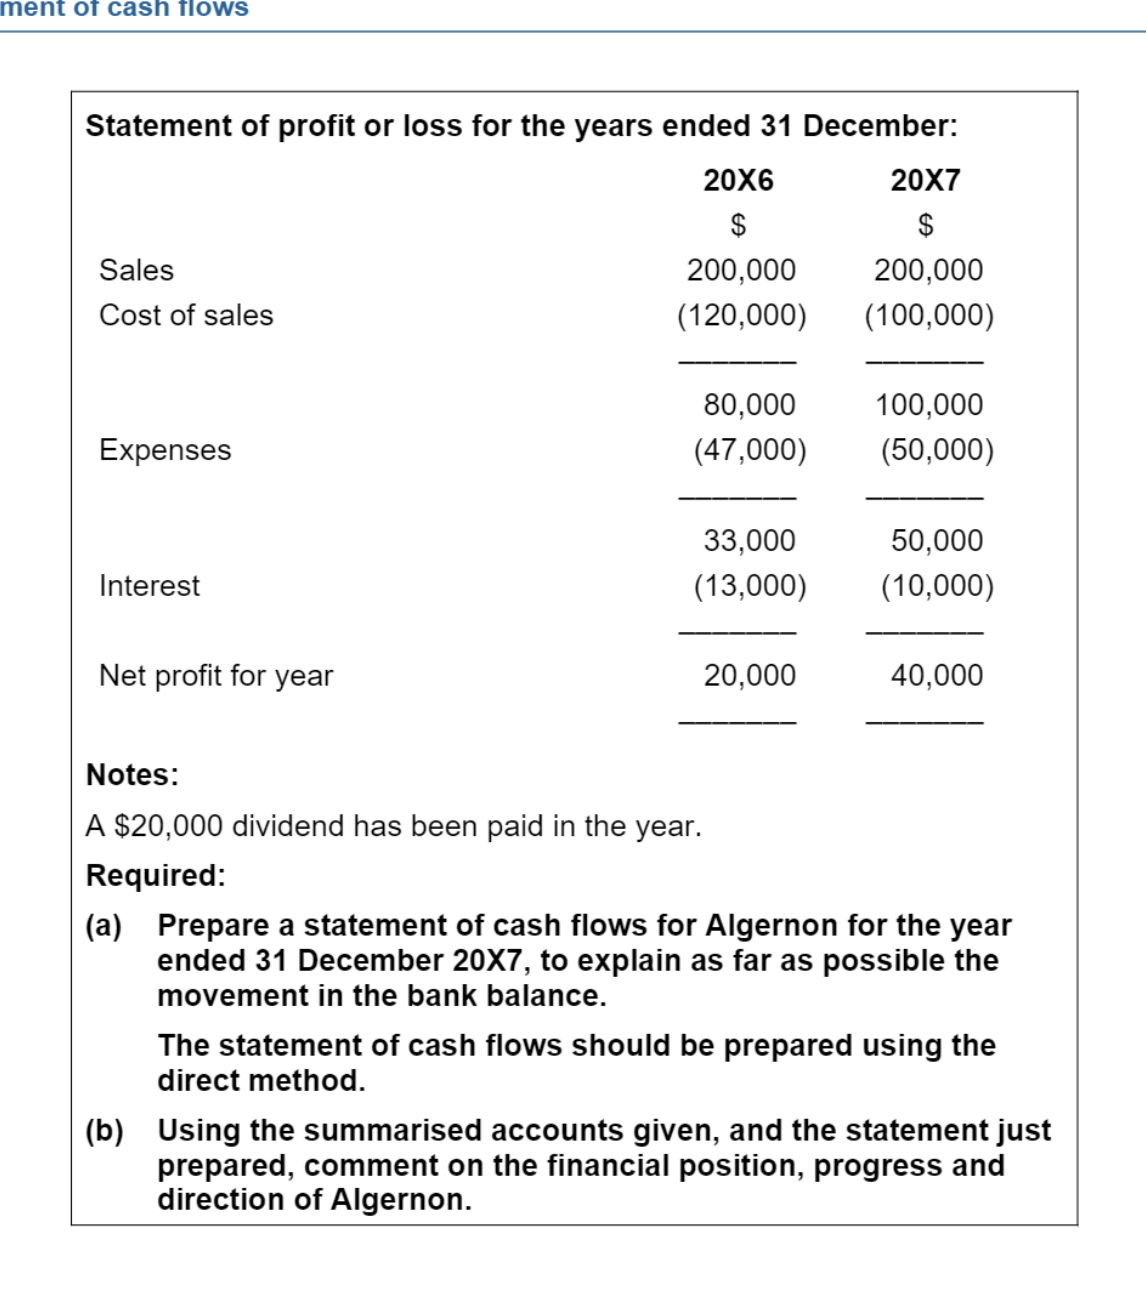
What is the net profit for Algernon for the year ended 31 December 20X7?
How much was the dividend paid by Algernon in 20X7?
For the year ended 31 December 20X6, Algernon's sales were $_______ and cost of sales was $_______.
For the year ended 31 December 20X7, Algernon's sales were $_______ and cost of sales was $_______.
The expenses reported for Algernon in 20X6 were $_______ and in 20X7 were $_______.
The interest paid by Algernon was $_______ in 20X6 and $_______ in 20X7.
When preparing a statement of cash flows, which specific method is required by the problem for Algernon?
In a statement of cash flows, how should a loss on disposal be treated relative to profit before tax?
In a statement of cash flows, how is an increase in receivables treated?
In a statement of cash flows, how is an increase in payables treated?
Which of the following items can appear in an entity's statement of cash flows: 1. Proposed dividend, 2. Dividends received, 3. Bonus issue of shares, 4. Surplus on revaluation of non-current assets?
What is the formula to calculate cash generated from operations when starting from profit before tax? 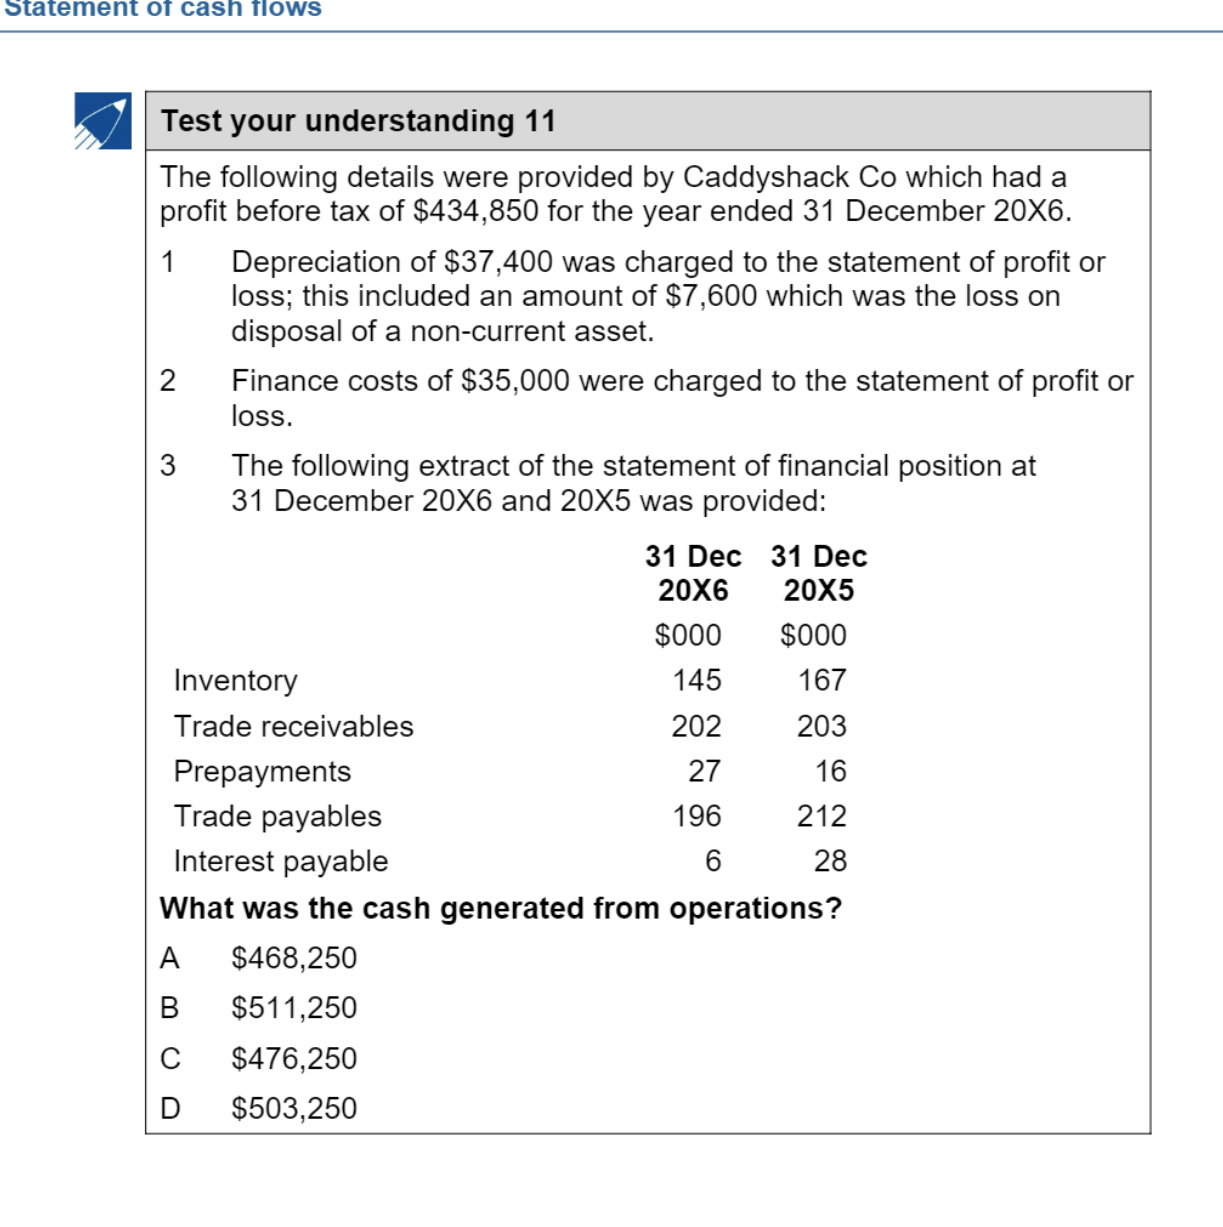
Calculate the cash generated from operations for Caddyshack Co. based on the following: Profit before tax $434,850, Depreciation $37,400, Finance costs $35,000, decrease in inventory $22,000, decrease in trade receivables $1,000, increase in prepayments $11,000, decrease in trade payables $16,000, decrease in interest payable $22,000.
When calculating cash generated from operations, _______ and _______ are added back to the profit before tax because they are non-cash or financing activities.
For Caddyshack Co, the change in inventory from 20X5 to 20X6 is a decrease of _______, which acts as a cash inflow in the statement of cash flows.
The change in trade payables for Caddyshack Co. from 20X5 to 20X6 resulted in a cash _______ of _______ because the liability decreased.
What is the primary benefit of a statement of cash flows regarding business liquidity? 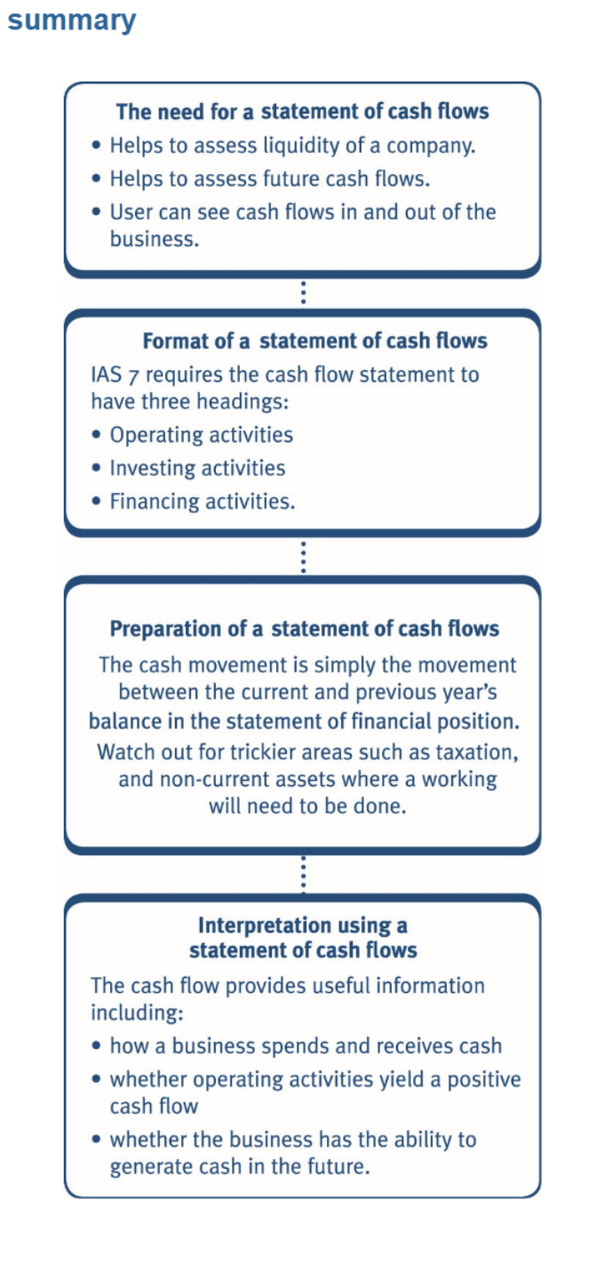
A statement of cash flows helps to assess _______ and allows users to see cash flows in and out of the business.
According to IAS 7, what are the three required headings in a statement of cash flows?
How is cash movement calculated when preparing a statement of cash flows?
When preparing a statement of cash flows, one must be careful with trickier areas such as _______ and _______ where a working will need to be done.
What kind of information can be derived from interpreting a statement of cash flows?
What is the total cash inflow from operations in 'Test your understanding 1'?
How is the net cash inflow from operating activities calculated from cash inflow from operations?
In the provided receivables ledger (W1), how is the cash received from customers calculated?
In the receivables ledger, the balance c/f is calculated as _______ which equals _______.
In the provided payables ledger (W2), how is the cash paid to suppliers calculated?
The net cash inflow from operating activities shown in the statement is $_______.
What is the impact of a 'contra with payables' on the cash received from customers ledger?
Based on the statement, interest paid is $_______ and income tax paid is $_______.
What is the accounting effect of accounting for a contra as described in the note?
In the Wages (W3) account, the total value credited to the Profit or Loss account is $_______.
The Interest payable (W4) account shows a balance brought forward of $_______ and a closing balance (c/f) of $_______.
For the Income tax (W5) account, the total amount charged to Profit or Loss is $_______.
How much was paid in net wages as shown in account (W3)?
What is the total value of interest paid as per the (W4) Interest payable account?
What is the starting figure used to calculate 'Cash flow generated from operations' in the provided example?
When calculating 'Cash flow generated from operations', how are finance charges treated in the statement?
When calculating 'Cash flow generated from operations', how is investment income treated in the statement?
What is the effect of an increase in trade receivables on cash flow from operations?
What is the effect of a decrease in trade payables on cash flow from operations?
What additional items must be deducted from 'Cash flow generated from operations' to arrive at 'Net cash flow from operations'?
In the accumulated depreciation account, what is the opening balance (balance b/f)?
What is the depreciation charge for the period as shown in the accumulated depreciation account (W1)?
The total cash flow generated from operations calculated in the example is \(_______.
In the accumulated depreciation account, the depreciation charge of \(_______ is used to reconcile the closing balance.
Explain the calculation of the depreciation charge shown in the cash flow statement using the accumulated depreciation account.
Based on the ledger for Interest payable, what was the amount of interest paid in cash?
What was the total P/L finance charge shown in the Interest payable account?
Calculate the cash paid for income tax using the Income tax payable ledger provided.
For the Dividends receivable ledger, the opening balance was _______ and the P/L dividends receivable was _______.
How much cash was received for dividends based on the provided ledger?
The Interest payable account shows an opening interest accrual (b/f) of _______.
In the PPE cost account, what does the amount of $178 represents?
How is the revaluation amount in the PPE cost account calculated?
The closing balance (Balance c/f) for the PPE cost account is \(_______\) thousand dollars.
What is the total cost of the items disposed of, based on the Disposals account?
How is the Loss on disposal calculated within the Disposals account?
The proceeds from the disposal of PPE amounted to \(_______\) thousand dollars.
What are the components that make up the total value of the items disposed of in the Disposals account?
The _______ of the disposed PPE is $15,000.
What is the formula to calculate the loan repayment amount given a balance of $300,000 in 20X5 and $200,000 in 20X6?
Based on the provided Retained earnings account, what is the calculation to find the dividends paid?
The proceeds of a share issue can be calculated by adding the change in _______ and the change in _______.
Using the Retained earnings account as a reference, identify the opening balance, profit, and closing balance.
To determine the dividends paid from the Retained earnings account, one must account for the _______ and the _______ against the _______.
What is the calculation for 'Net cash generated from operating activities' for Geronimo in 20X6?
What is the calculation for 'Net cash used in investing activities' for Geronimo in 20X6?
What is the calculation for 'Net cash generated from financing activities' for Geronimo in 20X6?
For the year 20X6, Geronimo experienced a net _______ in cash and cash equivalents of _______ ($000).
How are 'Cash and cash equivalents at end of period' calculated for Geronimo?
The main categories of a statement of cash flows are: - Cash flows from _______ activities - Cash flows from _______ activities - Cash flows from _______ activities
Looking at the statement of cash flows for Geronimo, which items fall under investing activities?
Looking at the statement of cash flows for Geronimo, which items fall under financing activities?
The statement of cash flows for Geronimo for the year ended 31 December 20X6 shows that interest paid (\(24k) and tax paid (\)62k) are classified as _______ activities.
In the statement of cash flows, the beginning cash balance of $18k plus the net increase of \(24k results in an ending cash balance of _______ (\)000).
What are the three main categories of cash flows presented in a Statement of Cash Flows?
What is the net cash from operating activities for Algernon for the year ended 31 December 20X6?
Which items are included in 'Cash flows from investing activities' in the provided Statement of Cash Flows?
What is the net cash used for investing activities for Algernon?
Which items are classified under 'Cash flows from financing activities'?
What was the total net cash from financing activities for Algernon?
The net decrease in cash and cash equivalents for Algernon was _______.
The cash and cash equivalents at 31 December 20X7 were _______.
What is the balance at bank as of 31 December 20X7?
What was the balance at bank on 31 December 20X6?
Cash generated from operations is calculated by adding cash receipts from customers and subtracting _______.
Interest paid is categorized under _______ in the statement of cash flows.
What is the formula for calculating receipts from sales in a Receivables account?
What is the formula to calculate cash paid, as shown in the Payables and wages account?
What is the relationship between Cost of sales, opening/closing inventory, and purchases?
In the Receivables account, the _______ of $200,000 is added to the opening balance, while the _______ of $190,000 represents the outflow of cash.
Depreciation is recorded in the _______ account as a credit adjustment of $_______.
The calculation for purchases in the Cost of sales account is derived as: _______ + _______ - _______ = $130,000.
What is the amount for Cash receipts in the Receivables account?
What is the total for Cash paid in the Payables and wages account?
What is the value of purchases for cost of sales?
When calculating cash generated from operations, should a loss on disposal be added back to profit?
Why are dividends received relevant to cash flow?
When calculating cash generated from operations, the _______ charged in the statement of profit or loss are included in the reconciliation, but the _______ in the year relating to those costs is only relevant when calculating the _______.
What is the cash generated from operations based on the following: Profit before tax $434,850; Depreciation and loss $37,400; Decrease in inventory $22,000; Decrease in trade receivables $1,000; Increase in prepayments $(11,000); Decrease in trade payables $(16,000); Finance costs $35,000?
For the entity Algernon, the equity to assets ratio has decreased due to financing expansion through new _______ and _______.
Algernon has financed its working capital requirements through an increase in _______.
Bu destedeki kartlar (644)
-
What are the two types of events defined after the reporting period?
- Adjusting events
- Non-adjusting events
-
Events occurring after the reporting period are classified as either adjusting or non-adjusting events.
-
What is the stated purpose of disclosure notes in financial reporting?
To provide additional context and details that are not fully captured on the face of the financial statements.
-
Financial reporting requires companies to explain the purpose of disclosure notes.
-
Which financial statements are specifically mentioned as being prepared from given information?
- Statement of financial position
- Statement of profit or loss and other comprehensive income
-
One learning objective is to prepare a statement of financial position and a statement of profit or loss and other comprehensive income from provided information.
-
What is one performance objective related to financial statements under PER (PO7)?
To prepare and review financial statements in accordance with legal and regulatory requirements.
-
The PER performance objective PO7 requires the ability to prepare and review financial statements in accordance with legal and regulatory requirements.
-
What is the starting point in the process of preparing basic financial statements as shown in the flowchart?
The trial balance.
-
What is the second step in the preparation of financial statements after the trial balance?
Year-end/closing adjustments.
-
Which accounting standard governs the preparation of year-end financial statements?
IAS 1.
-
Which accounting standard deals with events occurring after the reporting period?
IAS 10.
-
Which accounting standard addresses revenue from contracts with customers?
IFRS 15.
-
The process of preparing financial statements involves entities such as: - Statement of financial position - Statement of profit or loss and other comprehensive income - Disclosure notes
-
The preparation of financial statements applies to both a sole trader or a limited liability company.
-
For which two reporting levels is the preparation of financial statements for a limited liability company a key syllabus element? - Financial Reporting - Strategic Business Reporting
-
What is the first step in the process of preparing financial statements as shown in the flowchart?
Transactions recorded in ledger accounts.
-
The standard process for preparing financial statements follows these steps: 1. Transactions recorded in ledger accounts 2. Ledger accounts balanced and closed off 3. Trial balance extracted 4. Year end adjustments made and ledger accounts closed off 5. Trial balance used to prepare financial statements
-
What must be done to the trial balance figures before financial statements are created?
Common adjustments made at the end of the accounting period must be processed.
-
Common end-of-period adjustments include: - Closing inventory - Depreciation charge for the year - Accruals and prepayments - Irrecoverable debts and allowances for receivables - Provisions and contingent liabilities - Income tax - Events after the reporting period
-
What is the accounting entry to record closing inventory?
- Debit Inventory (SFP)
- Credit Cost of sales (P/L)
-
What is the accounting entry for the annual depreciation charge?
- Debit Depreciation expense (P/L)
- Credit Accumulated depreciation (SFP)
-
What is the accounting entry for accruals?
- Debit Expenses (P/L)
- Credit Accrual (Liability) (SFP)
-
What is the accounting entry for prepayments?
- Debit Prepayment (Current Asset) (SFP)
- Credit Expenses (P/L)
-
What is the accounting entry for irrecoverable debts?
- Debit Irrecoverable debt expense (P/L)
- Credit Receivables (SFP)
-
What is the accounting entry for an increase in the allowance for receivables?
- Debit Irrecoverable debt expense (P/L)
- Credit Allowance for receivables (SFP)
-
What is the accounting entry for a decrease in the allowance for receivables?
- Debit Allowance for receivables (SFP)
- Credit Irrecoverable debt expense (P/L)
-
What is the accounting entry for the tax estimate for the year?
- Debit Tax charge (P/L)
- Credit Current tax liabilities (SFP)
-
What is the accounting entry to record an overprovision of tax from a prior year?
- Debit Current tax provision (SFP)
- Credit Tax charge for the year (P/L)
-
What is the accounting entry to record an underprovision of tax from a prior year?
- Debit Tax charge for the year (P/L)
- Credit Current tax provision (SFP)
-
The accounting entry for closing inventory involves debiting Inventory (SFP) and crediting Cost of sales (P/L).
-
The accounting entry for an increase in the allowance for receivables is debiting Irrecoverable debt expense (P/L) and crediting Allowance for receivables (SFP).
-
Which accounting standard governs the presentation of published company financial statements?
IAS 1 Presentation of Financial Statements.
-
Name the components that are required to be presented in a set of financial statements according to IAS 1.
- A statement of financial position
- A statement of profit or loss
- A statement of other comprehensive income
- A statement of changes in equity
- Notes to the financial statements
- A statement of cash flows
-
What does a statement of financial position summarize?
It summarizes the asset, liability, and equity balances at the end of the accounting period.
-
IAS 1 requires that assets and liabilities in the statement of financial position must be classified as either current or non-current.
-
List the categories included under 'Non-current assets' in the standardized statement of financial position.
- Property, plant and equipment
- Investments
- Intangibles
-
List the categories included under 'Current assets' in the standardized statement of financial position.
- Inventories
- Trade and other receivables
- Prepayments
- Cash at bank
-
What standard format is shown in the statement of financial position for XYZ Co at 31 December 20XX?
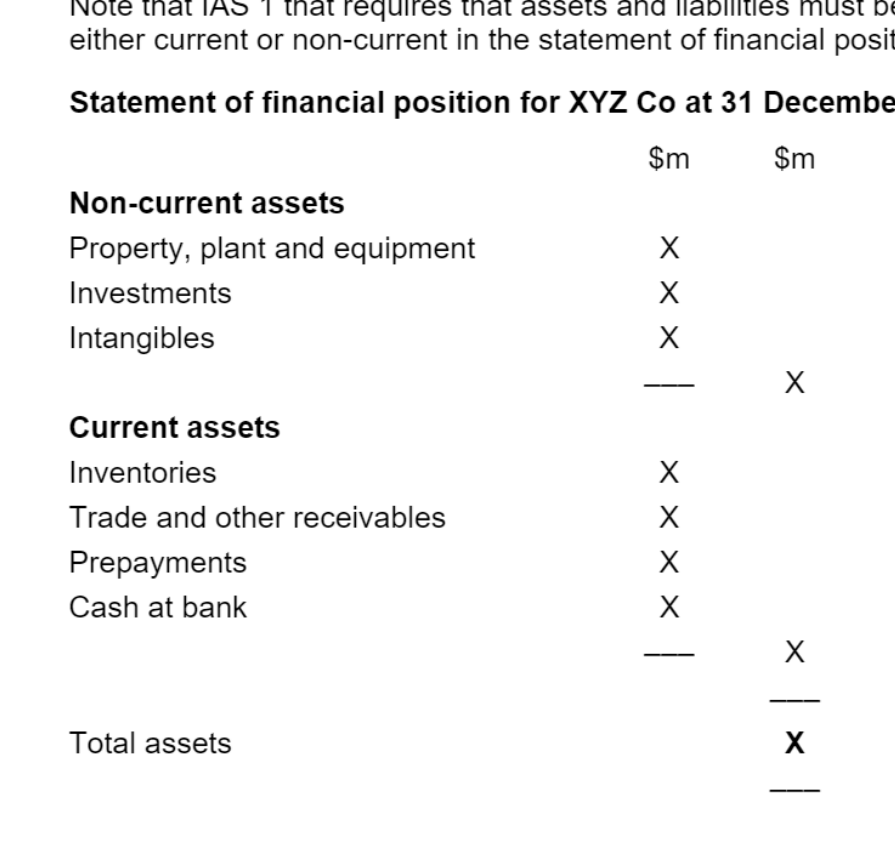 The statement presents non-current assets and current assets, which total to the 'Total assets'.
-
Name the five categories included under 'Equity' in the statement of financial position.
- Ordinary share capital
- Irredeemable preference share capital
- Share premium
- Revaluation surplus
- Retained earnings
-
What items are typically listed under 'Current liabilities' in a statement of financial position?
- Trade and other payables
- Overdrafts
- Tax payable
-
An asset is classified as a current asset if it is held primarily for trading purposes, expected to be realised within 12 months of the statement of financial position date, or is cash or a cash equivalent.
-
How should assets that do not meet the definition of a current asset be classified?
They should be classified as non-current assets.
-
Can inventory or receivables be classified as current assets even if they are not expected to be realised within twelve months?
Yes, they can qualify as current assets if they are held primarily for trading purposes.
-
Which accounting standard provides the rules for distinguishing between current and non-current assets and liabilities?
IAS 1
-
What is the primary function of the statement of profit or loss?
It summarizes the income earned and expenses incurred during the financial period.
-
A liability is classified as a current liability if it is expected to be settled in the normal course of the enterprise's operating cycle.
-
A liability should be classified as a current liability if it is held primarily for the purpose of being traded.
-
A liability is a current liability if it is due to be settled within 12 months of the statement of financial position date.
-
How are liabilities that do not meet the criteria for current liabilities classified?
They are classified as non-current liabilities.
-
In the statement of profit or loss, what is the sequence after calculating gross profit?
Subtracting distribution costs and administrative expenses to arrive at profit from operations.
-
The statement of profit or loss formula is: Revenue - Cost of sales = Gross profit.
-
What is the order of items deducted from 'Profit from operations' to arrive at 'Profit before tax'?
First add investment income, then subtract finance costs.
-
The final step in the statement of profit or loss is: Profit before tax - Tax expense = Net profit for the period.
-
What is the primary reason that the 'statement of profit or loss and other comprehensive income' extends the traditional 'statement of profit or loss'?
It accounts for unrealised gains that are not yet included in net profit.
-
A common example of an unrealised gain that is reported in other comprehensive income is the revaluation of tangible non-current assets.
-
Why are unrealised gains, such as those from asset revaluation, excluded from net profit for the period?
Because they are not realised through the sale of the asset and conversion into cash; they are hypothetical gains based on the date of revaluation.
-
Where are unrealised gains added in the financial reporting structure presented in this chapter?
They are added to the end of the statement of profit or loss.
-
An entity has the option to present 'other comprehensive income' information in which two ways?
- As part of a single statement combined with profit or loss.
- As two separate statements: the statement of profit or loss and the statement of other comprehensive income.
-
In the provided statement format, Total comprehensive income is calculated by adding the gain or loss on property revaluation to the net profit for the period.
-
Why must certain items be disclosed separately on the face of the financial statements or in the notes?
To ensure they are clearly visible to users, as they are not part of normal trading activity and could significantly distort reported profits or losses.
-
Items requiring separate disclosure are typically significant, one-off transactions or events that are not part of the normal trading activity of the business.
-
What are three examples of items that require separate disclosure in the statement of profit or loss?
- Cost of restructuring or reorganisation
- Profits or losses on disposal of property, plant, equipment, or investments
- Impairments of inventory, property, plant, and equipment
-
How should items requiring separate disclosure be presented in the statement of profit or loss?
They should be included on their own separate line.
-
Based on the provided flowchart, what two components link the statement of financial position at the start and end of a period?
- Profit or loss
- Movement of cash to/from shareholders
-
The movement of cash between a business and its shareholders interacts with the statement of financial position to reflect changes between the start and end of a period.
-
What does equity represent in a company?
Equity represents the owners' interests in the company, defined as what is left after all assets are sold and all liabilities are paid upon ceasing to trade.
-
The components of equity include share capital, share premium, and reserves.
-
What is the function of the revaluation surplus?
It is created to recognize the surplus arising when tangible non-current assets, such as land and buildings, are revalued.
-
Why can the revaluation surplus not be included in retained earnings?
Because the gain is not realized.
-
What are retained earnings?
The sum total of all profits and losses made by the company since its incorporation that have not yet been paid to shareholders as a dividend.
-
What is the purpose of the statement of changes in equity?
It summarizes the opening and closing positions on all equity accounts and identifies the reasons for any movements during the year.
-
In the statement of changes in equity, dividends paid are represented by (X).
-
Based on the provided statement of changes in equity for XYZ Co, how are equity shares issued recorded?
They increase both share capital and share premium.
-
Based on the statement of changes in equity for XYZ Co, where is net profit added?
It is added to the retained earnings column and the total column.
-
The main reserves in a company are the revaluation surplus and retained earnings.
-
What is the primary purpose of disclosure notes in financial statements?
To explain the accounting policies used, explain the movement between opening and closing balances, show how certain balances are complied with, and provide further detail to help users understand the accounts.
-
The disclosure notes are required to explain the accounting policies used when preparing the accounts.
-
Disclosure notes are used to explain the movement between the opening and closing balances of major statement of financial position items.
-
According to the requirements, disclosure notes are provided to offer further detail or explanation to users to ensure the financial statements are understandable.
-
Which specific chapter covers disclosure notes related to inventory?
Chapter 5
-
Which chapters cover disclosure notes for non-current tangible and intangible assets?
Chapters 6 and 7
-
Which chapter covers disclosure notes for provisions?
Chapter 11
-
Which chapter covers disclosure notes for events after the reporting period?
Chapter 15
-
What is the primary objective of the exercise shown in the illustration?
To prepare a statement of profit or loss and a statement of financial position based on a trial balance and adjustments.
-
In the trial balance for Crown Co, the ordinary share capital of $100,000 is recorded as a credit balance.
-
In the provided trial balance, are 'Sales' and 'Purchases' separate accounts or a combined entry?
They are listed as a combined entry of 'Sales and purchases' with both a debit amount of $266,800 and a credit amount of $365,200.
-
The inventory value at the start of the period for Crown Co on 1 January 20X5 is $23,340.
-
What is the total value of 'Land' listed in the Crown Co trial balance?
$100,000 as a debit.
-
The accumulated depreciation for motor vehicles as of 1 January 20X5 is a credit balance of $12,240.
-
What are the recorded amounts for 'Receivables and payables' in the trial balance?
- Receivables (Debit): $17,330
- Payables (Credit): $23,004
-
The retained earnings as of 1 January 20X5 for Crown Co are $104,800 and are recorded as a credit balance.
-
What is the total of the debit and credit columns in the trial balance?
Both columns total $631,854.
-
What is the inventory valuation for Crown Co. as of 31 December 20X5?
$25,680
-
How are rent, and light and heat adjustments handled for Crown Co. at 31 December 20X5?
Rent is prepaid by $1,000 and light and heat owed is $460.
-
What is the revalued amount for land at 31 December 20X5?
$250,000
-
How are receivables adjusted for Crown Co. at 31 December 20X5?
A debt of $130 is written off and the allowance for receivables is adjusted to $516.
-
What is the estimated income tax charge for the year for Crown Co.?
$7,300
-
What is the annual depreciation rate and method for buildings?
2% annually, straight-line method.
-
How are fixtures and fittings depreciated?
Using the straight line method over a useful life of five years with no residual value.
-
What is the depreciation rate and method for motor vehicles?
30% annually on a reducing balance basis.
-
What is the policy for charging depreciation in the year of acquisition and year of disposal?
A full year's depreciation is charged in the year of acquisition and none in the year of disposal.
-
The annual depreciation for buildings is 2% using the straight-line method.
-
The annual depreciation for motor vehicles is 30% on a reducing balance basis.
-
What is the formula used to calculate gross profit as shown in the statement of profit or loss?
Gross profit is calculated as Revenue minus Cost of sales.
-
Total comprehensive income is the sum of Profit for the year and Other comprehensive income.
-
List the components classified under Current assets in the statement of financial position.
- Inventory
- Trade receivables
- Prepayments
- Cash at bank
-
In the statement of financial position, Property, plant and equipment is classified as a Non-current asset.
-
Calculate the total value of current assets based on the figures provided.
$25,680 (Inventory) + $16,684 (Trade receivables) + $1,000 (Prepayments) + $3,312 (Cash at bank) = $46,676.
-
The statement of profit or loss for the year ended 31 December 20X5 shows a revenue of $364,000 after deducting the adjustment.
-
The income tax charge deducted from Profit before tax to reach the Profit for the year is $7,400.
-
What is the total comprehensive income for the year ended 31 December 20X5?
$166,944
-
Based on the statement of financial position, the total assets amount to $402,508.
-
What is the total value of equity based on the provided financial data?
$371,744
-
What are the components of current liabilities?
- Income tax liability ($7,300)
- Trade payables ($23,004)
- Accrued expenses ($460)
-
How is the cost of sales calculated (W1)?
\[Cost of Sales = Opening Inventory + Purchases - Purchase returns - Closing inventory\] -
The calculation for cost of sales (W1) starts with opening inventory of $23,340 and adds purchases of 266,800.
-
What is the final calculated cost of sales (W1)?
$262,860
-
In the administrative expenses (W2), the total expense amount is 78,418.
-
List the three largest administrative expenses shown in (W2).
- Wages: $46,160
- Depreciation: $11,128
- Rent: $12,000
-
The formula used to calculate Revaluation surplus in the provided data is $250,000 - $100,000.
-
The total of all current liabilities is 30,764.
-
The total equity and current liabilities combined equals 402,508.
-
What is the calculation for Retained earnings in the provided data?
\[104,800 + 16,944 = 121,744\] -
The total administrative expenses include irrecoverable debts calculated as $984 + $130 = $1,114.
-
What is the total income tax expense for the year, based on the income tax schedule?
$7,400
-
How is the depreciation charge for buildings calculated?
$100,000 * 2% = $2,000
-
How is the depreciation charge for fixtures calculated?
$28,000 * 20% = $5,600
-
How is the depreciation charge for vehicles calculated?
($24,000 - $12,240) * 30% = $3,528
-
The total depreciation charge for the year is \(\)11,128.
-
What is the carrying amount (CA) for buildings after accumulated depreciation?
$92,000
-
What is the carrying amount (CA) for fixtures and fittings after accumulated depreciation?
$5,600
-
What is the carrying amount (CA) for motor vehicles after accumulated depreciation?
$8,232
-
The total cost or valuation of non-current assets is \(\)402,000.
-
How is the net trade receivables balance calculated after allowance?
$17,200 - $516 = $16,684
-
What is the impact of the movement in the allowance for receivables on the P&L?
A decrease of $72.
-
The movement in the allowance for receivables is calculated as the difference between the balance b/fwd of \(\)588 and the balance c/fwd of \(\)516.
-
What is the new carrying amount for the building as per adjustment 1 for Penguin Co?
$11,000
-
What is the proposed final ordinary dividend per share as per adjustment 2?
10c per share
-
What is the estimated current year tax charge as per adjustment 3?
$3,000
-
What is the closing inventory value for Penguin Co as per adjustment 4?
$12,000
-
What does the suspense account balance of $8,000 represent according to adjustment 5?
Proceeds from the issue of 4,000 ordinary shares
-
The trial balance of Penguin Co shows a tax account balance of $500, which represents an overprovision of tax from the previous year.
-
The three financial statements to be prepared for Penguin Co are the statement of profit or loss and other comprehensive income, the statement of financial position, and the statement of changes in equity.
-
What is the inventory valuation for Ali Page as at 30 June 20X7?
$12,000
-
How should the write-off of an irrecoverable debt of $1,000 be classified?
As an administrative and selling expense.
-
How should the wages cost of $15,000 be split?
Equally between cost of sales and administrative and selling expenses.
-
Where should the $5,000 depreciation charge for the year be classified?
As a cost of sale.
-
The trial balance shows a bank balance of Cr $4,150.
-
The interest rate on the bank loan shown in the trial balance is 6%.
-
What is the total value of purchases listed in the trial balance?
$60,000
-
What is the total value of sales listed in the trial balance?
$120,000
-
What is the balance of drawings listed in the trial balance?
$8,000
-
What is the value of the suspense account listed in the trial balance?
$8,000 (Cr)
-
The inventory value at the start of the period (1 July 20X6) was $10,000.
-
The capital account at the start of the period (1 July 20X6) was $73,100.
-
What is the definition of events after the reporting period according to IAS 10?
These are events, favourable and unfavourable, that occur between the end of the reporting period and the date when the financial statements are authorised for issue.
-
IAS 10 classifies events after the reporting period into two categories: adjusting events and non-adjusting events.
-
How are adjusting events treated according to IAS 10?
Adjusting events provide additional evidence of conditions existing at the reporting date, and the financial statements must be adjusted to reflect the event.
-
What defines a non-adjusting event under IAS 10?
Non-adjusting events concern conditions which did not exist at the reporting date.
-
If a non-adjusting event impacts the going concern status, how should it be treated?
The financial statements must be adjusted to present on the break-up basis.
-
How are non-adjusting events that do not impact going concern treated?
The financial statements are not adjusted, but the event should be disclosed by note if it is important to the users' understanding.
-
For the disposal of an item of property, plant and equipment, the gain or loss is determined by comparing the proceeds to the $10,000 net carrying amount.
-
What is the primary characteristic of adjusting events in financial reporting?
They provide additional evidence of conditions that already existed at the reporting date.
-
If a material adjusting event is identified, the financial statements must be amended to reflect the relevant condition.
-
Examples of adjusting events include: - The settlement after the reporting date of a court case which confirms a year end obligation - The receipt of information after the reporting date that indicates that an asset was impaired at the reporting date
-
Examples of adjusting events include: - The bankruptcy of a customer after the reporting date that confirms that a year-end debt is irrecoverable - The sale of inventories after the reporting period at a price lower than cost
-
What must be done if non-adjusting events are material?
Additional disclosure is required by way of a note to the financial statements giving details of the event.
-
Non-adjusting events arise after the reporting date but do not concern conditions existing at the reporting date.
-
Examples of non-adjusting events include: - Announcing a plan to discontinue an operation - Major purchases of assets
-
Examples of non-adjusting events include: - Entering into significant commitments or contingent liabilities - Commencing a court case arising out of events after the reporting date
-
What information must be disclosed in a note for a material non-adjusting event according to IAS 10?
- The nature of the event
- An estimate of the financial effect, or a statement that such an estimate cannot be made.
-
For material non-adjusting events, IAS 10 requires disclosure of the nature of the event and an estimate of the financial effect or a statement that such an estimate cannot be made.
-
What standard governs revenue recognition from contracts with customers?
IFRS 15
-
When stating revenue in financial statements, how should sales tax and amounts collected on behalf of others be treated?
They should be excluded.
-
Revenue should be stated in financial statements excluding sales tax and any amounts collected on behalf of others.
-
According to IFRS 15, how is revenue defined?
Revenue is defined as income arising in the course of an entity's ordinary activities.
-
The five-step approach for revenue recognition under IFRS 15 begins by: 1. Identify the contract
-
The second step in the five-step revenue recognition approach is to: 2. Identify the separate performance obligations within a contract
-
The third step in the five-step revenue recognition approach is to: 3. Determine the transaction price
-
The fourth step in the five-step revenue recognition approach is to: 4. Allocate the transaction price to the performance obligations in the contract
-
The final step in the five-step revenue recognition approach is to: 5. Recognise revenue when (or as) a performance obligation is satisfied.
-
In the example of the travel agent receiving a $3,000 booking with a 10% commission, what amount should the agent recognise as revenue?
$300.
-
In the example of the travel agent receiving a $3,000 booking with a 10% commission, how is the balance of $2,700 accounted for?
As a liability due to the holiday company.
-
In the case study provided, how many performance obligations did Wad Co identify for the customer purchase?
Two: - Supply of a computer - Supply of technical support for 12 months
-
What is the primary factor that makes revenue recognition variable for credit customers?
If they are offered an early settlement discount.
-
When is revenue recognized?
Either at a point in time, or over a period of time.
-
Revenue is recognized over time if the entity's performance creates or enhances an asset that the customer controls as the asset is created or enhanced.
-
An entity recognizes revenue over time if the customer simultaneously receives and consumes the benefits provided by the entity's performance as the entity performs its obligations.
-
What are the two components of the total transaction price of $420 mentioned for the computer and technical support sale?
- $300 for the sale of the computer
- $120 for the supply of technical support
-
What is the amount of deferred income as at 31 March 20X2 for the technical support contract?
$80
-
Revenue is recognized over time if the entity's performance does not create an asset with an alternative use to the entity and the entity has an enforceable right to payment for performance completed to date.
-
In the example provided, why is the computer sale revenue recognized on 1 December 20X1?
Because control of the computer was transferred to the customer on that date.
-
According to IFRS 15, when must revenue be recognised if it is not recognised over time?
Revenue must be recognised at a point in time.
-
What is the primary condition for an entity to recognise revenue at a point in time under IFRS 15?
The entity must be able to determine when control over goods or assets supplied has been transferred.
-
Control of an asset refers to the ability to direct the use of, and obtain substantially all of the remaining benefits (inflows or savings in outflows) from the asset.
-
What does control of an asset include besides the ability to direct its use and obtain benefits?
Control includes the ability to prevent other entities from obtaining benefits (using or selling) that asset.
-
Indicators of the transfer of control include: - The entity has a present right to payment for the asset. - The customer has legal title to the asset. - The entity has transferred physical possession of the asset.
-
Additional indicators of the transfer of control include: - The customer has the significant risks and rewards of ownership of the asset. - The customer has accepted the asset.
-
When is the transfer of control criteria more likely to apply?
It is more likely to apply when physical products or goods have been sold to a customer and it can be clearly established that control has been transferred at a specific point or date in time.
-
What are the three key disclosure requirements relating to revenue recognition under IFRS 15?
- The accounting policy for revenue recognition.
- Significant judgements made to apply the 5-step approach.
- The total amount of revenue recognised, broken down into significant categories.
-
For the transaction with Customer A, how much revenue can AMS Co recognize in its financial statements for the year ended 30 June 20X4?
Revenue of $1,000. Revenue is recognized when goods are delivered (20 June 20X4), regardless of when cash is received.
-
What is the amount included within trade receivables at 30 June 20X4 for the contract with Customer A?
$1,200. This consists of the \(1,000 revenue plus 20% sales tax (\)200) that is owed to AMS Co at the year-end.
-
For the contract with Customer B, how much revenue can AMS Co recognize in its financial statements for the year ended 30 June 20X4?
\(1,350. The total revenue of \(1,500 is split between goods (\)900) and 6 months of maintenance (\)600). As of 30 June 20X4, the goods were supplied and 2 months of maintenance (May and June) have been earned ($600 / 6 * 2 = $200). $900 + $200 = $1,100. (Correction based on standard revenue allocation: the total contract price is $1,500. $900 goods + 2/6 * $600 = $1,100).
-
How much revenue can AMS Co recognize for the transaction with Customer C for the year ended 30 June 20X4?
$50. AMS Co acts as an agent and recognizes only its commission. The sale price of the goods is $500 (since $600 includes 20% sales tax, $600 / 1.2 = $500). The 10% commission is 10% of $500, which is $50.
-
What is the starting point in the preparation process of basic financial statements shown in the flowchart?
The trial balance.
-
The year-end/closing adjustments process includes: - inventory - depreciation - accruals and prepayments - irrecoverable debt - allowances for receivables - provisions - Income tax
-
The preparation of year-end financial statements is governed by IAS 1.
-
What are the three main components prepared after year-end adjustments, as shown in the flowchart?
- Statement of financial position
- Statement of profit or loss and other comprehensive income
- Disclosure notes
-
Disclosure notes typically include: - non-current assets - provisions - events after the reporting period - inventory
-
Events after the reporting period are categorized as either adjusting or non-adjusting and follow standard IAS 10.
-
Which accounting standard governs revenue from contracts with customers?
IFRS 15
-
What is the formula used to calculate the cost of sales for Penguin Co?
\(8,000 + 20,000 - 12,000\)
-
What was the total cost of sales for Penguin Co for the year ended 31 December 20X5?
\(16,000\)
-
What is the gross profit for Penguin Co?
\(34,000\)
-
What is the operating profit for Penguin Co?
\(10,450\)
-
What is the profit before taxation for Penguin Co?
\(7,250\)
-
What is the total profit for the year for Penguin Co?
\(4,750\)
-
What was the total comprehensive income for Penguin Co?
\(10,750\)
-
The revenue for Penguin Co was $50,000.
-
The taxation for Penguin Co was calculated as \(3,000 - 500\) which equals $2,500.
-
The revaluation surplus in the year for Penguin Co was $6,000.
-
The distribution costs for Penguin Co amounted to $8,000.
-
The administrative expenses for Penguin Co amounted to $15,550.
-
The fundamental reorganisation costs for Penguin Co were $2,400.
-
The finance charges for Penguin Co were $800.
-
What is the total value of Tangible assets for Penguin Co. as of 31 December 20X5?
$41,000
-
What items are included under Current assets for Penguin Co.?
- Inventory
- Trade receivables
- Cash at bank and in hand
-
What is the total value of Current assets for Penguin Co.?
$29,250
-
What are the components of Equity for Penguin Co.?
- Ordinary share capital
- 10% irredeemable preference share capital
- Share premium account
- Revaluation surplus
- Retained earnings
-
What is the total Equity for Penguin Co. as of 31 December 20X5?
$39,250
-
What is listed under Non-current liabilities for Penguin Co.?
10% loan notes
-
What is the value of 10% loan notes for Penguin Co.?
$8,000
-
What are the components of Current liabilities for Penguin Co.?
- Trade payables
- Taxation
-
What is the total Current liabilities for Penguin Co.?
$23,000
-
The total assets of Penguin Co. as of 31 December 20X5 are $70,250.
-
The value of Inventory for Penguin Co. is $12,000.
-
The value of Trade receivables for Penguin Co. is $10,000.
-
The value of Cash at bank and in hand for Penguin Co. is $7,250.
-
What is the primary reason why irredeemable preference share capital is classified as equity?
There is no obligation to redeem or repay this share capital.
-
When 4,000 shares are issued for $8,000, if the nominal value is \(0.50 per share, the share premium per share is \)1.50.
-
In the statement of changes in equity, how is the revaluation of a building reflected?
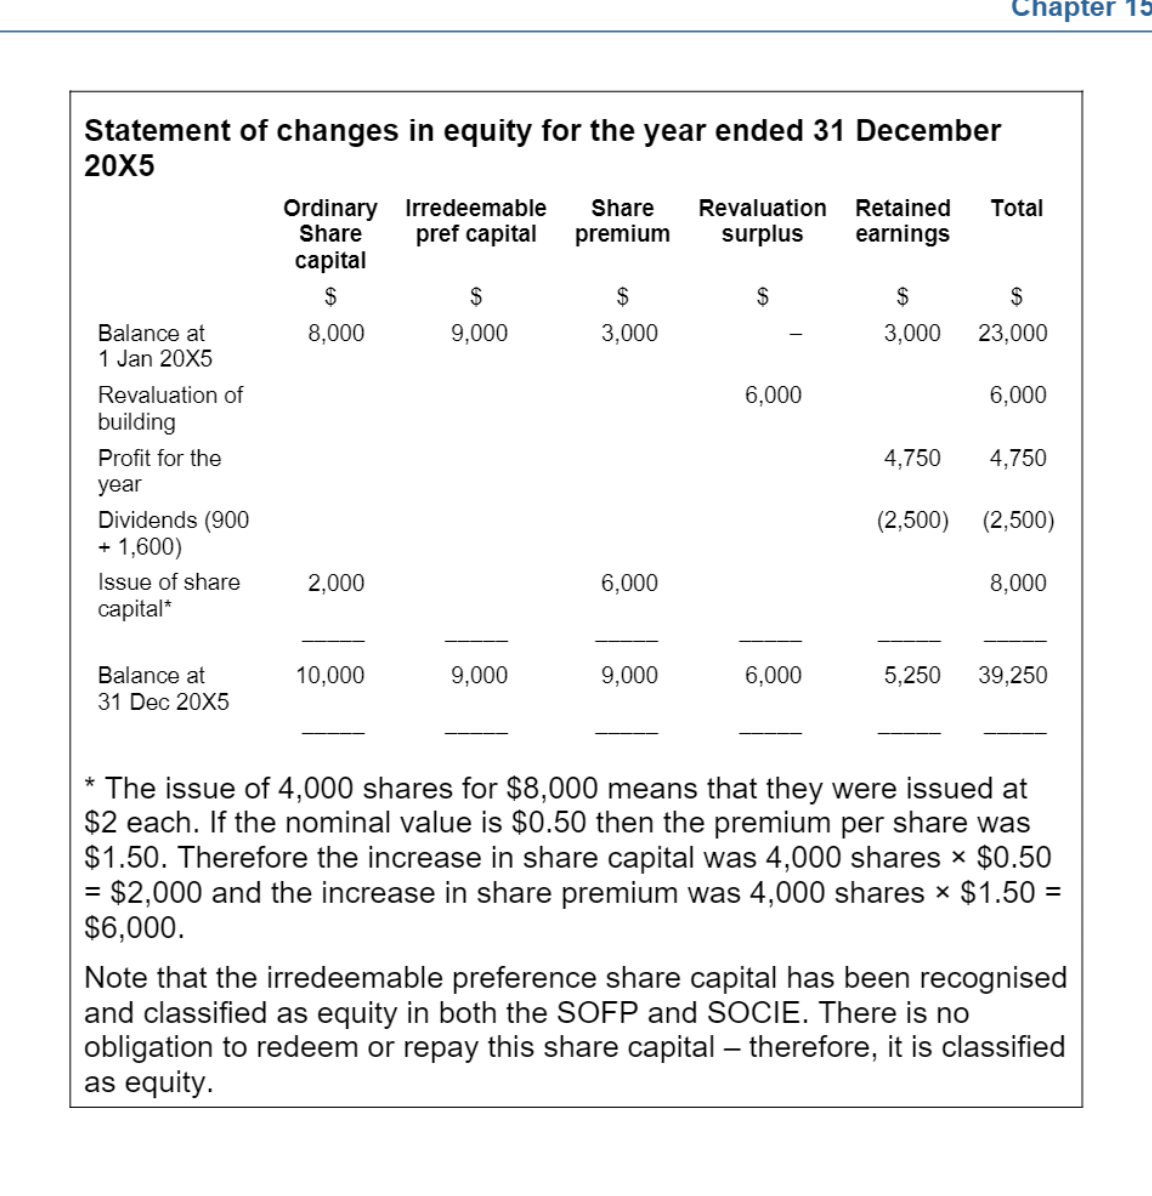
It is recorded as an increase of $6,000 in the Revaluation surplus column.
-
In the statement of changes in equity, dividends of $2,500 are deducted from Retained earnings.
-
What is the total equity balance at 31 December 20X5 as shown in the statement of changes in equity?
$39,250
-
The issue of 4,000 shares resulting in an $8,000 increase in total equity is split into a $2,000 increase in Ordinary Share capital and a $6,000 increase in Share premium.
-
What is the amount of Revenue shown for Ali Page for the year ended 30 June 20X7?
$120,000
-
What is the formula to calculate Gross profit in a statement of profit or loss?
Revenue minus Cost of sales
-
What is the calculated Gross profit for Ali Page for the year ended 30 June 20X7?
$50,000
-
What is the calculated Operating profit for Ali Page for the year ended 30 June 20X7?
$21,150
-
What is the final Profit for the year for Ali Page for the year ended 30 June 20X7?
$20,550
-
What are the total Non-current assets for Ali Page at 30 June 20X7?
$87,500
-
What are the total Current assets for Ali Page at 30 June 20X7?
$23,200
-
What is the Total assets value for Ali Page at 30 June 20X7?
$110,700
-
What is the final Capital account balance for Ali Page at 30 June 20X7?
$90,650
-
The statement of profit or loss for Ali Page reports an operating profit of \(21,150 and a profit for the year of \)20,550.
-
The total value of assets for Ali Page at 30 June 20X7 is $110,700.
-
Based on the provided Statement of financial position, what is the calculation for Tangible assets?
$102,500 - $10,000 - $5,000 = $87,500
-
What is the total value of non-current liabilities shown in the financial notes?
$10,000 (representing the 6% bank loan).
-
Which items are classified under current liabilities?
- Trade payables
- Bank overdraft
- Interest accrual
-
The total of current liabilities is $10,050.
-
How is the cost of sales calculated in working (W1)?
Opening inventory + Purchases - Closing inventory + Wages (50%) + Loss on disposal + Depreciation charge - Discount received.
-
What is the calculation for the loss on disposal of a non-current asset?
Cost of $10,000 less proceeds of $8,000, resulting in a loss of $2,000.
-
What components are included in Administrative and selling expenses (W2)?
- Per trial balance ($5,600)
- Wages ($7,500)
- Irrecoverable debts ($2,550)
-
How is the loan interest accrual calculated in (W3)?
Annual charge of \(600 (\)10,000 * 6%) minus the amount already paid of $300, leaving an accrual of $300.
-
The total for Administrative and selling expenses is $15,650.
-
Is the sale of year-end inventory at less than cost considered an adjusting or non-adjusting event?
Adjusting event. It provides evidence of the net realisable value, requiring a write-down of inventory.
-
How is a share issue classified regarding year-end adjustments?
Non-adjusting event.
-
Why is a fire in a warehouse generally a non-adjusting event?
If only a small quantity is destroyed, it does not affect the entity's ability to operate as a going concern.
-
Under what condition would a fire in a warehouse necessitate a change to a break-up basis in financial statements?
If the loss of inventory is so pervasive that it affects the entity's ability to operate as a going concern.
-
Is the bankruptcy of a major customer an adjusting or non-adjusting event?
Adjusting event. It provides evidence of the customer's inability to pay their debt at year-end, meaning the amount should be written off.
-
Is the acquisition of a company like Teeny Co an adjusting or non-adjusting event?
Non-adjusting event.
-
Why is the receipt of insurance monies considered an adjusting event?
It provides evidence of a year-end asset, requiring the amount to be reflected in the year-end accounts.
-
An event that requires a change to the financial statements because it provides evidence of conditions that existed at the year-end is called an adjusting event.
-
What is the key principle regarding the inclusion of sales tax in revenue recognition?
Revenue excludes sales tax.
-
How should trade receivables be calculated in relation to sales tax?
Trade receivables should include sales tax charged as that is the total amount due from the customer.
-
When should revenue from the supply of goods be recognised?
Revenue from the supply of goods can be recognised at a point in time when control of the goods has been transferred.
-
How should revenue from the supply of services be recognised?
Revenue on the supply of services should be recognised over a period of time from the date supply commenced.
-
How is commission calculated on a transaction of $600 (including 20% sales tax) with a 10% rate?
- Determine net sales: $600 / 1.2 = $500
- Calculate commission: $500 * 10% = $50
-
Revenue recognition for the supply of goods occurs at the point in time when control of the goods has been transferred.
-
Revenue for services is recognised over a period of time starting from the date supply commenced.
-
What is the primary subject matter of Chapter 16?
Incomplete records.
-
Techniques used in incomplete record situations include: - Use of the accounting equation - Use of ledger accounts to calculate missing figures - Use of cash and/or bank summaries - Use of given gross profit percentage to calculate missing figures
-
What does PER performance objective PO6 aim to achieve?
 It aims to help you record and process transactions and events and understand how to demonstrate that objective.
-
What is the primary purpose of the techniques discussed for 'Incomplete records'?
To derive missing information when accounting records and ledgers are incomplete or unavailable.
-
The four main approaches to calculating missing figures in accounting are: - accounting equation method - balancing figure approach - using cash/banking data - profit ratios – mark-up and margin
-
In the context of incomplete records, what does the 'balancing figure approach' typically involve?
Using ledger accounts to determine missing figures.
-
Which accounting ratio concepts are mentioned as methods for dealing with incomplete records?
Mark-up and margin.
-
When financial information is incomplete, accountants must use the best available information to guesstimate any missing figures.
-
Why are the techniques for handling incomplete records important for future ACCA studies?
They are relevant to future studies in Financial Reporting.
-
What is the basic accounting equation?
\(Assets = equity + liabilities\)
-
How can the accounting equation be expanded to include specific components?
\(Total assets = share capital + retained earnings + other reserves + total liabilities\)
-
What is the formula to calculate closing retained earnings (RE)?
\(Closing RE = prior year's RE figure +/– this year's profit(loss) – dividends\)
-
Work out the profit for Andy Carp Co based on the following: Assets (10,000+3,400=13,400), Liabilities (2,100+1,700=3,800), Share Capital (200), Prior RE (7,350).
- Total Assets: \(10,000 + 3,400 = 13,400\)
- Total Liabilities: \(2,100 + 1,700 = 3,800\)
- Equity: \(13,400 - 3,800 = 9,600\)
- Equity also equals: \(Share Capital + RE = 200 + RE = 9,600\) so \(RE = 9,400\)
- Profit: \(9,400 (closing) - 7,350 (opening) = 2,050\) Answer: $2,050 (Option C)
-
The accounting equation is: Assets = equity + liabilities.
-
The formula for closing retained earnings is: \(Prior year's RE figure +/– this year's profit(loss) – dividends\).
-
If a business has very little transaction info, how can they calculate net profit for the year?
By using the accounting equation to compare the value of assets, liabilities, and share capital between the current year and the previous year's retained earnings.
-
What is the primary purpose of the ledger account approach in incomplete records?
It is used to determine a balancing figure for various accounts when information is missing.
-
In a Receivables ledger account, what are two examples of potential missing figures that could be calculated?
- Credit sales
- Receipts from credit customers
-
In a Payables ledger account, what are two examples of potential missing figures that could be calculated?
- Credit purchases
- Payments to credit suppliers
-
In a Cash at bank ledger account, what are two examples of potential missing figures that could be calculated?
- Drawings
- Money stolen
-
In a Cash in hand ledger account, what are two examples of potential missing figures that could be calculated?
- Cash sales
- Cash stolen
-
The ledger account approach is used to calculate a balancing figure in situations involving incomplete records.
-
Based on the Cash at bank ledger account provided, what item appears on the credit side as a possible missing entry?
Money stolen
-
What two types of cash transactions might a business need to distinguish between for ledger records?
Cash transactions involving notes and coins versus transactions recorded in the bank ledger account.
-
Looking at the provided templates, what are the entries on the debit side of the Cash at bank ledger account?
- Cash received from customers
- Banking from cash in hand
- Sundry income
-
Looking at the provided templates, what are the entries on the credit side of the Cash in hand ledger account?
- Sundry cash expenses
- Amounts banked
- Money lost or stolen
- Balance c/f
-
What is the formula to calculate total sales for the year given accounts receivable information? Use the T-account structure provided.
Total sales = (Closing receivables + Total receipts from customers) - Opening receivables
-
What is the formula to calculate total purchases for the year given accounts payable information?
Total purchases = (Closing payables + Total payments to suppliers) - Opening payables
-
Solve 'Test your understanding 2': Rubble's business had opening receivables of $30,000, total receipts of $55,000, contras with payables of $3,000, and closing receivables of $37,000. What were the total sales for the year?
The correct answer is B, $50,000.
Workings: Sales = (Closing receivables + Receipts from receivables + Contras with payables) - Opening receivables Sales = ($37,000 + $40,000 + $3,000) - $30,000 Sales = $80,000 - $30,000 = $50,000
-
When information cannot be allocated between cash and credit transactions, the total receivables or total payables accounts are used to determine total sales or purchases.
-
What methods can be used to calculate a 'missing' expense figure from a statement of profit or loss?
- T-accounts
- Equations
-
In Test your understanding 3, what is the cost of total purchases for the year? Given: Opening payables $15,000; Total payments $14,000; Discounts received $500; Closing payables $13,000.
The answer is B ($18,000). Working: Cost of purchases = Closing payables + Cash paid + Discounts received - Opening payables Cost of purchases = \(13,000 + (14,000 + (500 - (15,000 = \(12,500 Wait, re-calculating based on standard T-account logic: Balance c/d (\)13,000) + Payments (\)14,000) + Discounts (\)500) - Balance b/d (\)15,000) = \(12,500. Correction: The options provided in the source include B (\)18,000) and D (\)12,500). Based on the formula: $13,000 (Closing) + $14,000 (Payments) + $500 (Discounts) - $15,000 (Opening) = $12,500. Correct option is D.
-
Calculate the electricity charge for the year (Test your understanding 4). Accrued 1 Jan: $250; Cash paid: $1,000; Accrued 31 Dec: $300.
The charge is $1,050. Working: Charge = Payments + Closing accrual - Opening accrual Charge = $1,000 + $300 - $250 = $1,050.
-
Calculate the rent charge for the year (Test your understanding 4). Prepaid 1 Jan: $300; Cash paid: $2,000; Prepaid 31 Dec: $400.
The charge is $1,900. Working: Charge = Payments + Opening prepayment - Closing prepayment Charge = $2,000 + $300 - $400 = $1,900.
-
What is the primary benefit of using bank summaries for reconstructing financial data?
It allows an entity to reconstruct cash inflows and outflows even when data is missing from the ledger accounts, by utilizing alternative sources like bank pay-in slips or bank statements.
-
Calculate the total receipts for Jude's bank account if the starting balance was an overdraft of $1,367, total payments were $8,536, and the closing balance was a positive $2,227.
The calculation is as follows: - Opening balance: -$1,367 - Closing balance: $2,227 - Net movement: \(2,227 - (-\)1,367) = $3,594 - Receipts = Net movement + Payments - Receipts = $3,594 + $8,536 = $12,130
The correct answer is D.
-
How much cash was received from customers if Dale's business had an opening cash float of $900, closing float of $1,000, banked $10,000, paid out $1,000 in drawings, and paid $2,000 in wages?
The calculation is as follows: - Cash banked: $10,000 - Payments: $1,000 (drawings) + $2,000 (wages) = $3,000 - Change in cash float: $1,000 - $900 = $100 - Cash received = Banked + Payments + Increase in float - Cash received = $10,000 + $3,000 + $100 = $13,100
The correct answer is C.
-
What two categories of sales must be combined to calculate total revenue?
Total revenue is the sum of: - Cash sales - Credit sales
-
Which four figures are required to complete a receivables account?
- Receivables at the beginning of the period (e.g., 1 August 20X8)
- Cash received from credit customers
- Receivables at the end of the period (e.g., 31 July 20X9)
- Credit sales for the year
-
In a receivables account, credit sales are recorded on the debit side, while cash received from credit customers is recorded on the credit side.
-
When calculating annual revenue, if total cash receipts and cash sales are known, the amount that must be determined to find total sales is credit sales.
-
What is the opening receivables figure at 1 August 20X8?
$98,425
-
How is the cash received from credit customers calculated when total cash is $245,675 and cash sales are $53,435?
Total cash received (\(245,675) minus cash sales (\)53,435) equals $192,240.
-
How is the adjusted closing receivables figure calculated when the list/memorandum total is $107,550 and irrecoverable debt is $1,500?
$107,550 minus $1,500 equals $106,050.
-
In the receivables account calculation, what is the total of the debit side including opening balance and credit sales?
$299,790
-
What items are included on the credit side of the receivables ledger account shown?
- Irrecoverable debt ($1,500)
- Cash received from credit customers ($192,240)
- Balance c/f at 31 July 20X9 ($106,050)
-
How is total revenue calculated based on cash and credit sales?
Revenue = Cash sales + Credit sales.
-
Based on the provided figures, what is the calculated total revenue?
\(254,800 (\)53,435 cash sales + $201,365 credit sales).
-
The opening receivables balance on 1 August 20X8 was $98,425.
-
Total receipts from credit customers are calculated as total cash received minus cash sales.
-
The closing receivables figure is determined by subtracting irrecoverable debt from the total receivables per the list/memorandum.
-
The amount for credit sales is treated as a balancing figure in the receivables ledger account.
-
Total revenue is the sum of cash sales and credit sales.
-
What is the formula for calculating Gross Profit Margin?
\(\(\text{Gross Profit Margin} = \left( \frac{\text{Gross profit}}{\text{Sales}} \right) \times 100\)\)
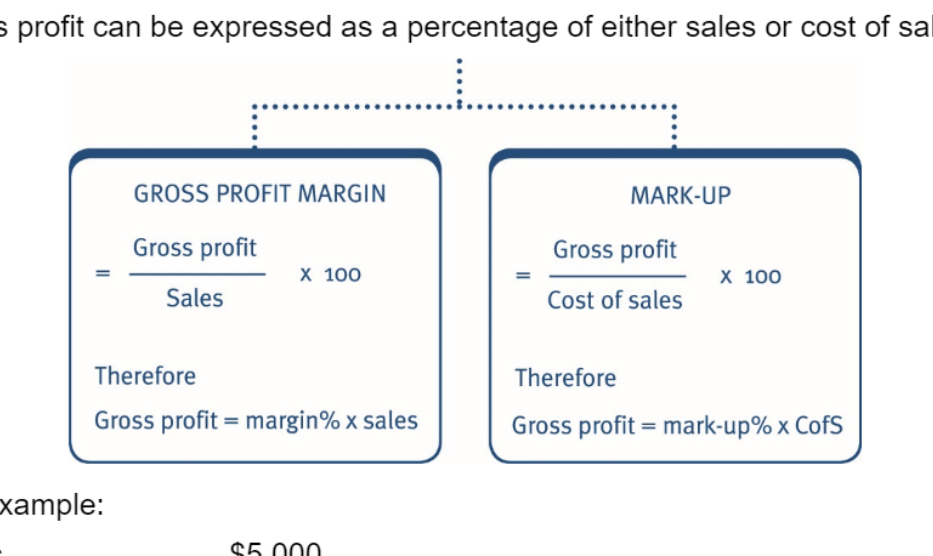
-
What is the formula for calculating Mark-up?
\(\(\text{Mark-up} = \left( \frac{\text{Gross profit}}{\text{Cost of sales}} \right) \times 100\)\)
-
Gross profit can be expressed as a percentage of either sales or cost of sales.
-
Pat has sales of $1,000 and a margin of 25%. What is the cost of sales?
The cost of sales is $750.
Workings: 1. Gross profit = $1,000 * 25% = $250. 2. Cost of sales = Sales - Gross profit = $1,000 - $250 = $750.
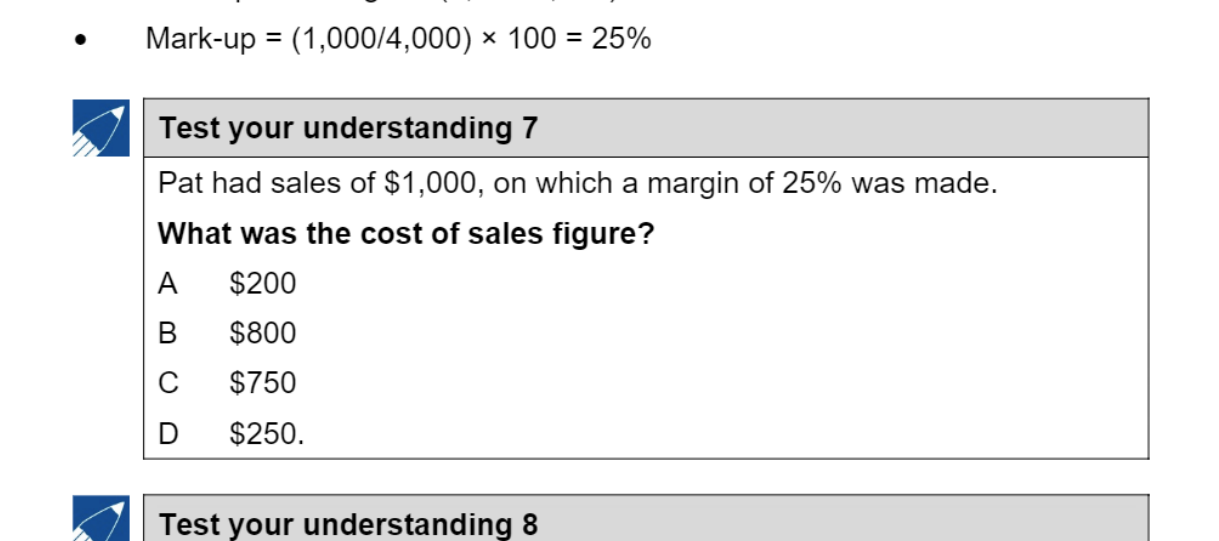
-
Lazim McDuff has a cost of sales of $600 and a mark-up of 25%. What is the related revenue?
The related revenue (sales) is $750.
Workings: 1. Gross profit = $600 * 25% = $150. 2. Sales (Revenue) = Cost of sales + Gross profit = $600 + $150 = $750.
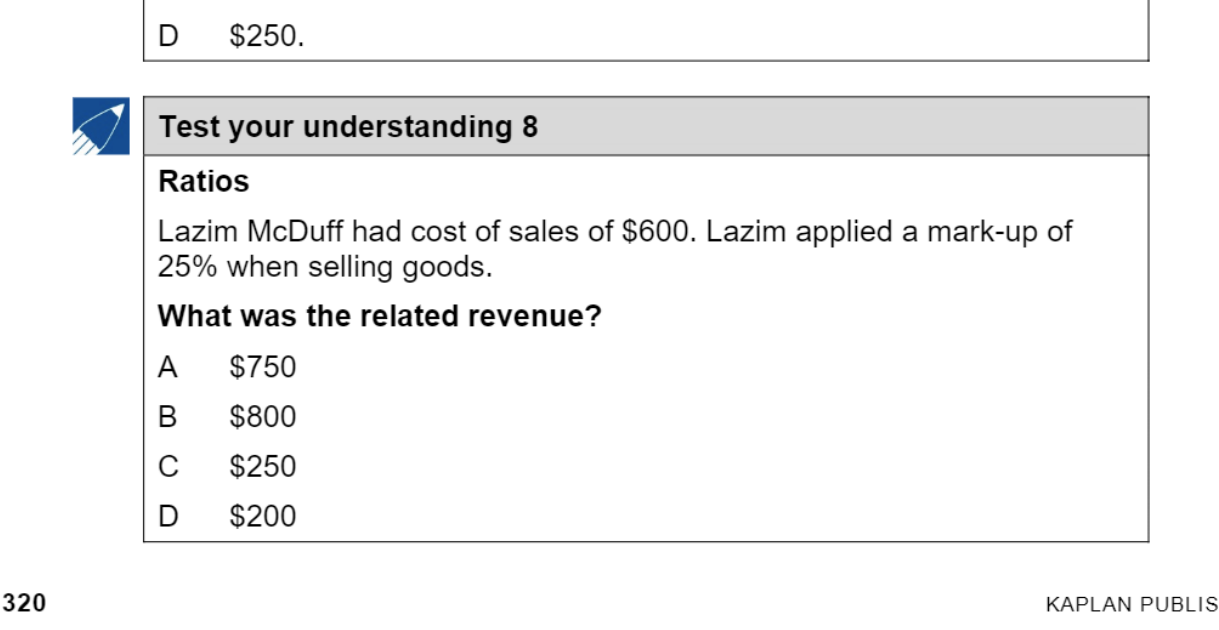
-
What is the relationship between Sales, Cost of sales, and Gross profit for a 20% Margin with $5,000 sales?
- Sales: $5,000 (100%)
- Cost of sales: $4,000 (80%)
- Gross profit: $1,000 (20%)
-
What is the relationship between Sales, Cost of sales, and Gross profit for a 25% Mark-up with $5,000 sales?
- Sales: $5,000 (125%)
- Cost of sales: $4,000 (100%)
- Gross profit: $1,000 (25%)
-
Given Jital Longhorn's inventory data (Opening: $800, Closing: $600, Purchases: $2,840), what is the Cost of Sales?
Cost of Sales = Opening Inventory + Purchases - Closing Inventory $800 + $2,840 - $600 = $3,040
-
If Jital Longhorn has a 5% margin and a Cost of Sales of $3,040, what is the Sales revenue?
If Margin is 5%, then Cost of Sales is 95% of Sales. Sales = Cost of Sales / 0.95 $3,040 / 0.95 = $3,200
-
Based on the calculated Sales (\(3,200) and Cost of Sales (\)3,040), what is Jital Longhorn's Gross profit?
Gross profit = Sales - Cost of Sales $3,200 - $3,040 = $160
-
The formula to calculate Cost of Sales using inventory is: Opening inventory + Purchases - Closing inventory.
-
If a business has a margin percentage and either sales, cost of sales, or gross profit is known, it is possible to calculate the remaining figures.
-
What is the basic formula to determine the cost of sales?
Cost of sales = Opening inventory + Purchases - Closing inventory.
-
In 'Test your understanding 10', what is the cost of inventory lost in the fire?
The cost of inventory lost is $9,000.
Workings: 1. Cost of goods sold = Sales - (Margin% * Sales) = $100,000 - (0.20 * $100,000) = $80,000. 2. Expected closing inventory = Opening inventory + Purchases - Cost of goods sold = $10,000 + $82,000 - $80,000 = $12,000. 3. Inventory lost = Expected closing inventory - Actual closing inventory = $12,000 - $3,000 = $9,000.
-
When recording actual closing inventory in double-entry bookkeeping, the entry is: Dr Inventory (SFP) Cr Profit or loss
-
If lost inventory is insured, the double-entry to remove it from cost of sales and record the claim is: Dr Insurance company (Other receivables/current asset) Cr Profit or loss (Cost of sales)
-
If lost inventory is not insured, the double-entry to remove it from cost of sales and record the loss is: Dr Profit or loss (Expense) Cr Profit or loss (Cost of sales)
-
What is the formula to calculate the cost of goods sold when the markup is known?
Cost of goods sold = Sales / (1 + Markup percentage).
-
Calculate the cost of sales for Druva's business given sales of $10,000 and a 25% markup.
Cost of sales = $10,000 / (1 + 0.25) = $8,000.
-
Calculate the value of closing inventory for Druva's business before the fire given: opening inventory $2,000, purchases $7,500, and cost of sales $8,000.
Closing inventory = Opening inventory + Purchases - Cost of sales = $2,000 + $7,500 - $8,000 = $1,500.
-
What is the journal entry to record the inventory write-off of $1,500?
Debit: Inventory destroyed (or Loss in P&L) $1,500 Credit: Inventory $1,500
-
The cost of sales is calculated as Sales / (1 + Markup percentage).
-
What are the primary methods for handling incomplete records in accounting as shown in the flowchart?
- Using ledger accounts (balancing figure approach)
- Using cash/bank summaries
- Using the accounting equation
- Using profit percentages (mark-up and margin)
-
What is the balancing figure approach when dealing with incomplete records?
Reconstructing the relevant ledger account as far as possible using the information given to reveal one missing figure.
-
How are cash/bank summaries utilized for incomplete records?
Using cash inflows and outflows to determine sales and purchases figures, often in conjunction with ledger account reconciliation.
-
What is the fundamental accounting equation used to resolve incomplete records?
\(Assets = Equity + Liabilities\)
-
What is the formula for gross profit using margin percentage?
\(Gross\ profit = margin\% \times sales\)
-
What is the formula for gross profit using mark-up percentage?
\(Gross\ profit = mark-up\% \times Cost\ of\ Sales\ (CofS)\)
-
The accounting equation used for handling incomplete records is \(Assets = equity + liabilities\).
-
When using profit percentages, the gross profit formula involving margin is \(Gross\ profit = margin\% \times sales\).
-
When using profit percentages, the gross profit formula involving mark-up is \(Gross\ profit = mark-up\% \times CofS\).
-
What is the formula to determine total assets based on capital and liabilities?
Total assets = share capital + retained earnings + other reserves + total liabilities
-
How do you calculate current year profits using retained earnings?
Current year profits = Closing retained earnings - prior year retained earnings
-
Given total assets of $13,400, share capital of $200, and other reserves of $3,800, what is the retained earnings value?
$9,400
-
Using the provided Receivables ledger, what is the credit sales amount if the total debits equal $80,000 and the starting balance b/f is $30,000?
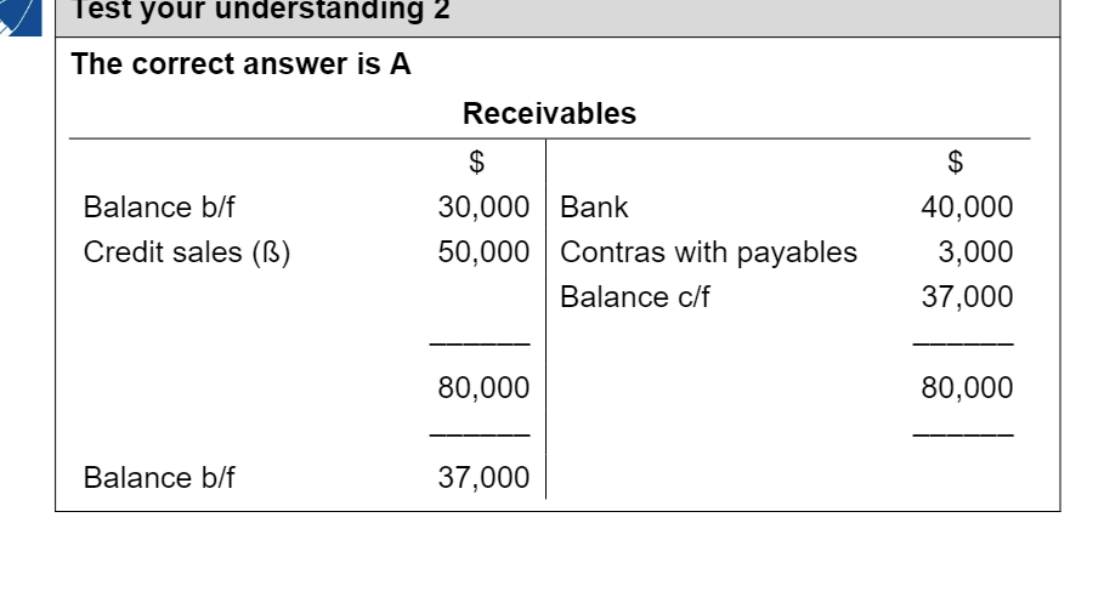 $50,000
-
The formula for calculating current year profits is: Current year profits = Closing retained earnings - prior year retained earnings.
-
In a receivables ledger, 'Contras with payables' are recorded on the credit side.
-
What is the formula for calculating total sales from credit and cash sales?
Total sales = $50,000 + $15,000 = $65,000
-
When preparing a total receivables account, what are the primary debit entries?
- Balance b/f: $30,000
- Total sales: $65,000
-
When preparing a total receivables account, what are the primary credit entries?
- Bank (total cash rec'd): $55,000
- Contras with payables: $3,000
- Balance c/f: $37,000
-
How is the balance c/f for total payables calculated based on the provided table?
Bank (\(14,000) + Discount received (\)500) + Balance c/f (\(13,000) = Total (\)27,500). The balance c/f is derived to balance the account against the credit entries.
-
In the total payables account, the credit side includes the opening balance Balance b/f of \(15,000 and the credit purchases of \)12,500.
-
Calculate the electricity expense for the statement of profit or loss.
$(-250 + 1,000 + 300) = $1,050
-
Calculate the rent expense for the statement of profit or loss.
$(300 + 2,000 - 400) = $1,900
-
Based on the Bank account ledger in 'Test your understanding 5', what is the value of the 'Balance c/f' at the end of the period?
$2,227
-
What is the total of the receipts side in the Bank account ledger example?
$12,130
-
In the Cash in till ledger, the 'Balance b/f' is $900 and the total receipts are $13,100.
-
According to the 'Cash in till' ledger in 'Test your understanding 6', what were the payments made for Bank, Drawings, and Wages respectively?
- Bank: $10,000
- Drawings: $1,000
- Wages: $2,000
-
What is the formula for calculating 'Gross profit' shown in 'Test your understanding 7'?
\[Gross profit = Sales \times 25\%\] -
If Sales are $1,000 and Gross profit is $250, what is the 'Cost of sales'?
$750
-
The 'Balance c/f' in the Cash in till account is $1,000.
-
How is gross profit calculated when given sales and a gross profit margin percentage? Refer to Test your understanding 8.
Gross profit is calculated by multiplying sales by the gross profit margin. For example, if sales are $600 and the margin is 25%, the gross profit is $600 * 25% = $150.
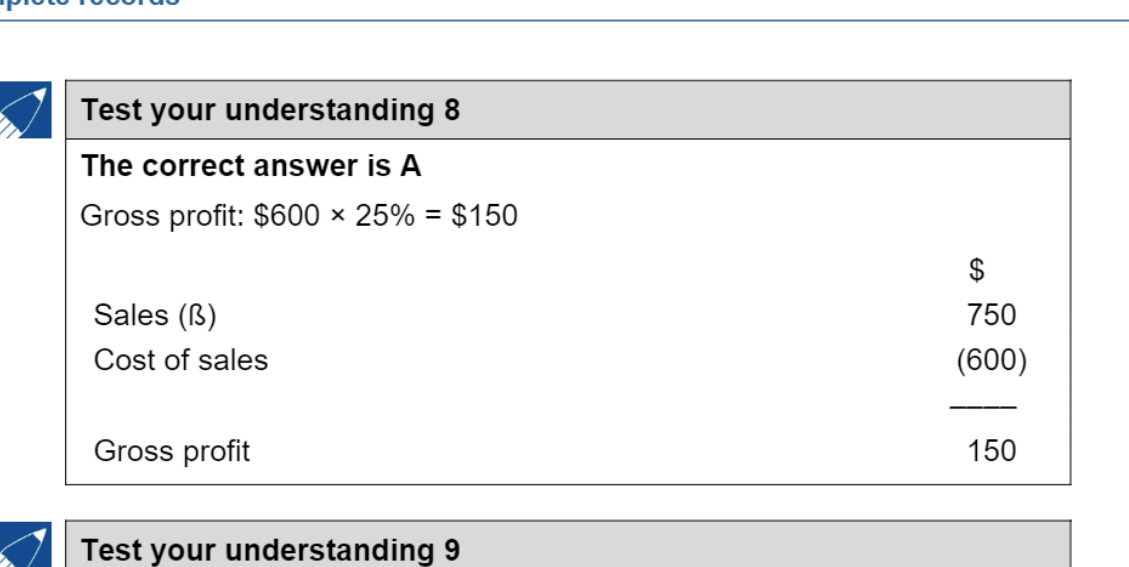
-
What is the formula for calculating cost of sales in a trading account?
Cost of sales = Opening inventory + Purchases - Closing inventory.
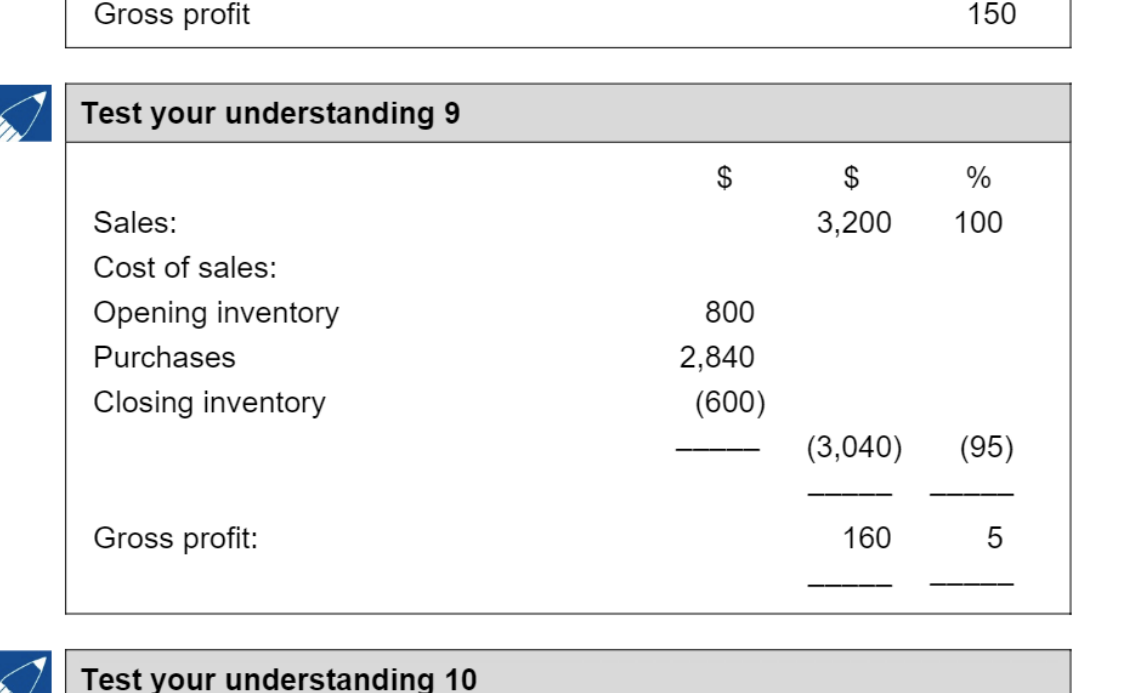
-
In a trading account, the gross profit margin is calculated as (Gross profit / Sales) * 100.
-
How should 'Inventory lost' be treated in a trading account calculation?
Inventory lost is subtracted as part of the total cost of sales adjustments to determine the final gross profit. For example, as seen in Test your understanding 10, it is subtracted along with the net movement in inventory.
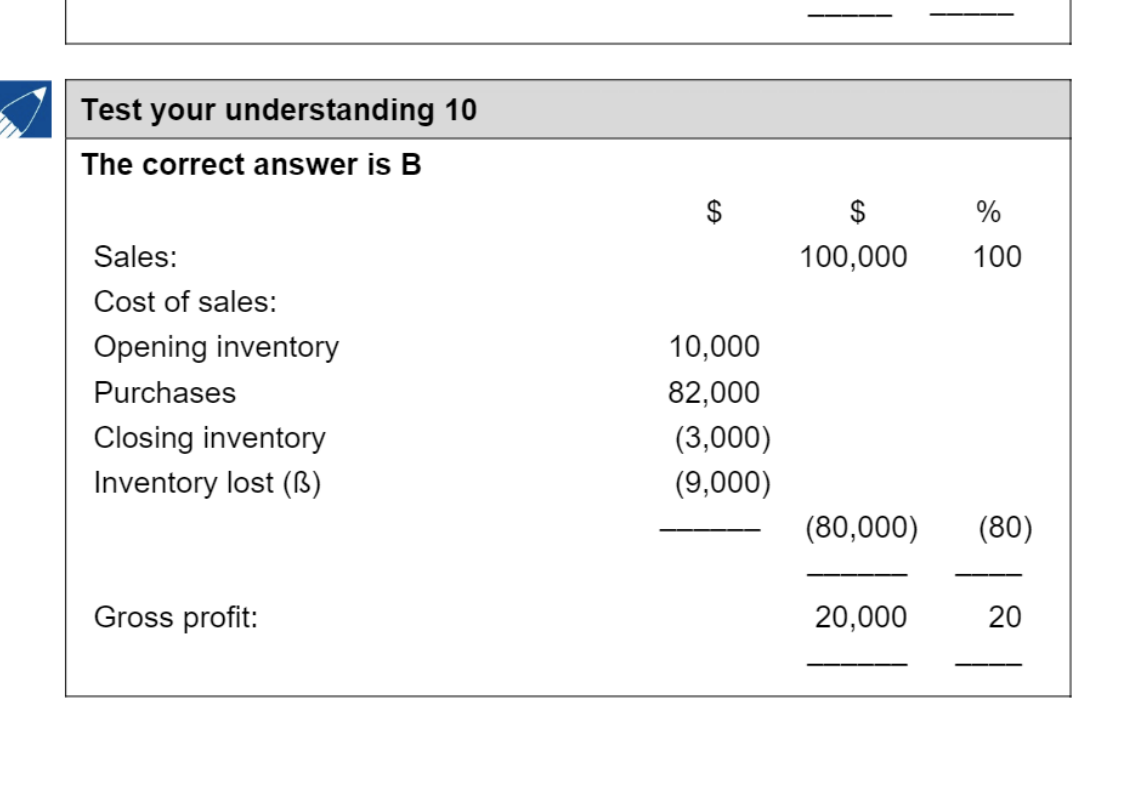
-
Using the data in Test your understanding 10, the cost of sales is calculated by adding Opening inventory to Purchases and then subtracting Closing inventory and Inventory lost.
-
In the context of 'Test your understanding 11', how is uninsured inventory lost by fire recorded in the profit or loss account?
It is recorded as a debit to the profit or loss (expense) account and a credit to the cost of sales account for the amount of $1,500.
-
When recording uninsured inventory destroyed by fire, the accounting entry involves a debit to the profit or loss (expense) account and a credit to the cost of sales account.
-
What is the calculation for the Cost of Sales in 'Test your understanding 11'?
The Cost of Sales is calculated as: Opening inventory (\(2,000) + Purchases (\)7,500) - Inventory lost ($1,500) = $8,000.
-
In the provided example, the Gross profit is determined by subtracting the Cost of Sales of \(8,000 from the Sales of \)10,000, resulting in a profit of $2,000.
-
What is the primary difference between profit and cash flows?
Profit is a measure of financial performance based on accounting principles, whereas cash flows represent the actual movement of money into and out of an entity.
-
The two methods used to calculate cash flows from operating activities are the indirect method and the direct method.
-
The PER performance objective PO7 relates to the preparation and review of financial statements in accordance with legal and regulatory requirements.
-
What are two key aspects users need to evaluate regarding a statement of cash flows?
- Benefits
- Drawbacks
-
What are the four key stages in the process of dealing with a statement of cash flows?
- The need for a cash flow statement
- Format of a cash flow statement
- Preparation of a cash flow statement
- Interpretation using a cash flow statement
-
The primary stages for dealing with a statement of cash flows are: - The need for a cash flow statement - Format of a cash flow statement - Preparation of a cash flow statement - Interpretation using a cash flow statement
-
Why might a profitable entity still fail to survive?
It may have insufficient cash to pay its debts and become insolvent.
-
An entity may be profitable but still fail if it has insufficient cash available to pay its short-term liabilities.
-
What is the primary difference in the calculation basis between profit and cash flow?
Profits are calculated using the accruals basis, whereas cash flows track actual cash received or paid.
-
Profits are calculated using the accruals basis, meaning that revenue is recognized before cash is necessarily received.
-
What is an example of an expense that is recognized in profit calculations but has no cash impact?
Depreciation.
-
Which accounting standard requires corporate entities to include a statement of cash flows in their annual financial statements?
IAS 7
-
What are two key measures of the financial health of an entity related to cash flow?
Solvency and liquidity.
-
Liquid assets that can be used to settle short-term debts include inventory, receivables, and cash.
-
Current liabilities that need to be settled by an entity include overdrafts, trade payables, loan interest, and tax balances.
-
What are the potential negative consequences if management fails to maintain sufficient current assets to pay liabilities as they fall due?
- Loss of supplier goodwill
- Fines and sanctions
- Being declared insolvent by a supplier, lender, or tax authority
-
To ensure effective cash flow balance, management must consider inventory production and storage cycles and maintain an effective system of credit control.
-
Besides maintaining an effective credit control system, what else must management balance regarding the entity's financial structure?
The level of debt the entity is exposed to.
-
One objective of IAS 7 is to report an entity's cash generation and cash absorption for a period.
-
IAS 7 aims to provide information that assists in the assessment of an entity's liquidity, solvency, and financial adaptability.
-
What is the primary reason why a statement of cash flows is needed?
It is needed as a consequence of the differences between profits and cash.
-
What does a statement of cash flows help assess regarding liquidity and solvency?
It helps assess if an entity has an adequate cash position in the short term to ensure survival, pay debts, and pay dividends.
-
What does financial adaptability in the context of cash flows refer to?
The ability of an entity to take effective action to alter its cash flows in response to unexpected events.
-
Why are adequate future cash flows essential for an entity in the long term?
They are essential to enable asset replacement, repayment of debt, and to fund further expansion.
-
The statement of cash flows highlights how cash is being generated through operating, financing, or investing activities.
-
Why are cash flows considered more objective than profit calculations?
Cash flows are matters of fact, whereas the calculation of profit is subjective and possible to manipulate.
-
What is a major limitation regarding the data used in a statement of cash flows?
It uses historic cash flows.
-
Are interpretations of the statement of cash flows provided within the financial accounts?
No, users are required to draw their own conclusions as to the relevance of the figures contained within it.
-
How are non-cash transactions handled in a statement of cash flows?
They are not highlighted in the statement of cash flows, although they are disclosed elsewhere.
-
Which accounting standard governs the preparation of the statement of cash flows?
IAS 7 Statement of Cash Flows.
-
What are the three main sections of a statement of cash flows?
- Cash flows from operating activities
- Cash flows from investing activities
- Cash flows from financing activities
-
The statement of cash flows categorizes activities into operating, investing, and financing activities.
-
Is interest paid typically included under operating, investing, or financing activities in the statement of cash flows?
Operating activities.
-
Where are 'proceeds of sale of equipment' reported on the statement of cash flows?
Cash flows from investing activities.
-
Are dividends paid categorized under operating, investing, or financing activities?
Financing activities.
-
How is the net increase or decrease in cash calculated at the end of the statement of cash flows?
By taking the net cash flow from operating, investing, and financing activities and comparing it to the cash and cash equivalents at the beginning of the period.
-
In the statement of cash flows, income taxes paid are classified as an operating activity.
-
Receipt of new loans and proceeds from the issue of shares are reported under financing activities.
-
Dividends received are classified as investing activities.
-
What is the accounting definition of 'Cash'?
Cash consists of cash in hand and deposits repayable upon demand, less overdrafts.
-
What are 'Cash equivalents'?
Short-term, highly liquid investments that are readily convertible to known amounts of cash and are subject to an insignificant risk of changes in value.
-
How does IAS 7 define 'Cash flows'?
Inflows and outflows of cash and cash equivalents.
-
Operating activities are the principal revenue-producing activities of the entity.
-
What is 'Cash generated from operations'?
A figure based on a reconciliation beginning with profit before tax, adjusted for items included in profit before tax but not involving the movement of cash.
-
How is 'Net cash flow from operations' calculated from 'Cash generated from operations'?
By deducting interest paid and tax paid in the year.
-
Investing activities are cash spent on non-current assets, proceeds of sale of non-current assets and income from investments.
-
Financing activities include the proceeds of issue of shares and long-term borrowings made or repaid.
-
What represents the net increase or decrease in cash and cash equivalents during the year?
The difference between the level of cash and cash equivalents at the start and at the end of the accounting period.
-
The two methods used to calculate net cash flow from operating activities are the direct method and the indirect method.
-
What are the two methods of presenting cash flows from operations?
- Direct method
- Indirect method
-
Why do most entities avoid using the direct method for presenting cash flows?
It discloses information that would otherwise remain confidential.
-
What are the two sources from which gross cash flows for the direct method can be derived?
- Accounting records by totalling cash receipts and payments directly.
- Opening and closing statements of financial position and statement of profit or loss by constructing summary account workings.
-
When using summary account workings for the direct method, what three specific items are typically analyzed to derive cash flows? - Sales to derive cash received from customers - Purchases to derive cash payments to suppliers - Wages to derive cash paid to and on behalf of employees
-
If you are presenting an example using the direct method, what visual aid summarizes the accounting information involved in Cash Co's statement of financial position?
The ledger accounting information, showing values for non-current assets, inventories, receivables, and cash for 20X6 and 20X7.
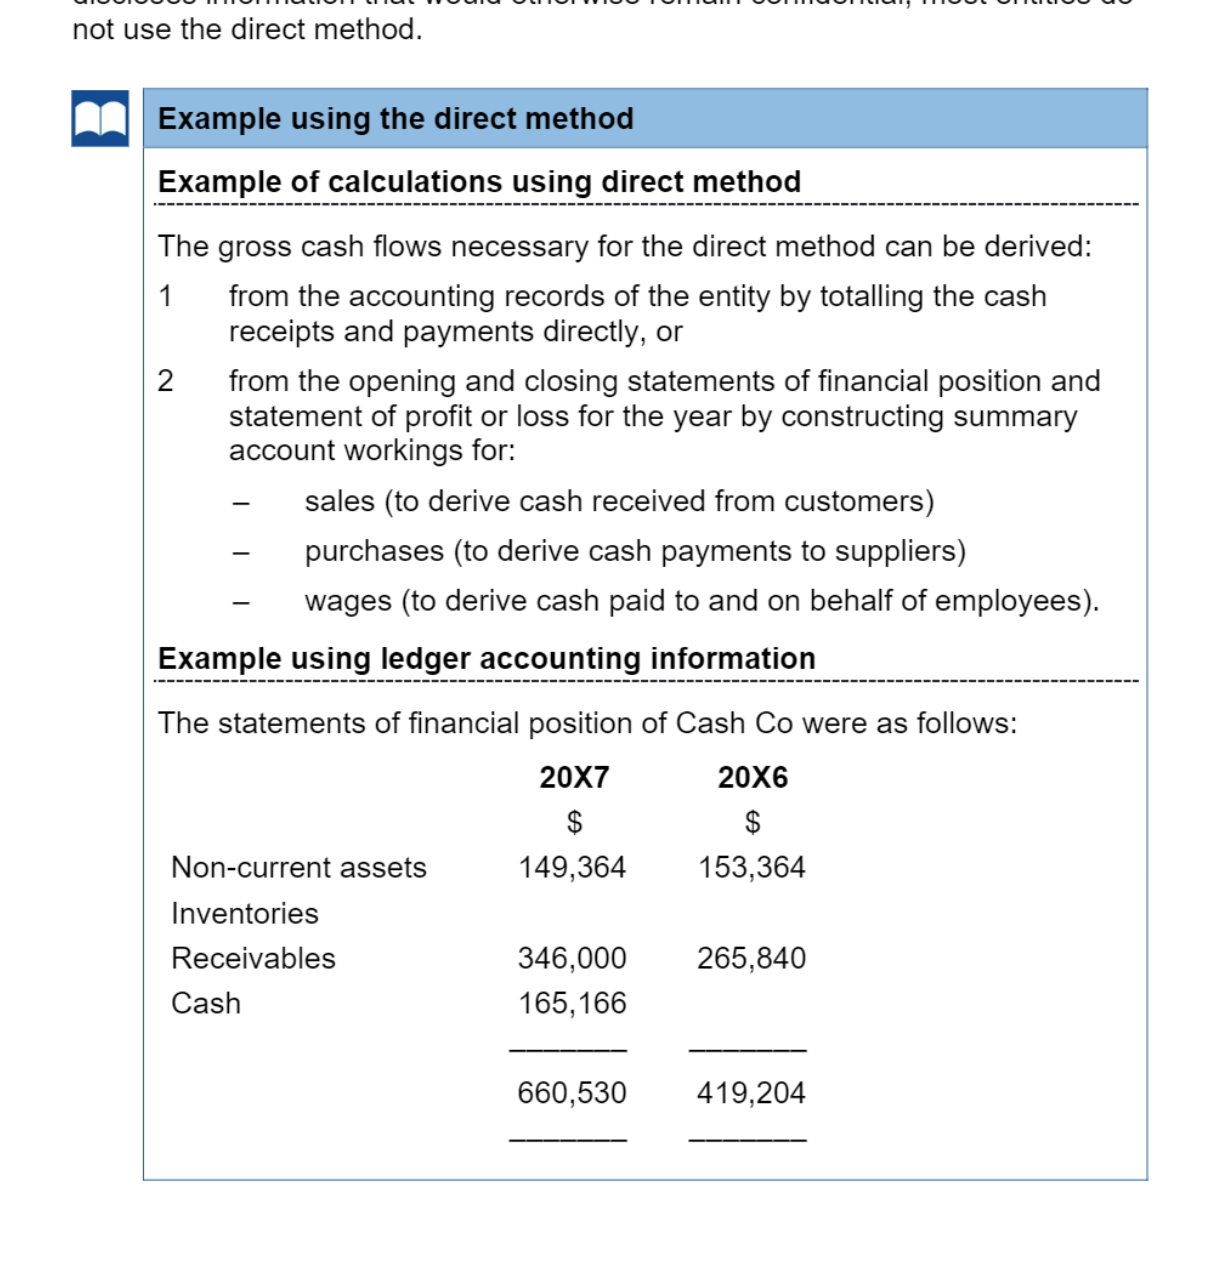
-
What is the amount of share capital for Cash Co in 20X7?
$200,000
-
What is the operating profit for the year ended 31 December 20X7?
$141,640
-
What are the components of current liabilities for Cash Co in 20X7?
- Re non-current assets: $46,000
- Trade and other payables: $258,240
- Wages accrued: $14,650
-
The total value of current liabilities for Cash Co in 20X7 is $318,890.
-
What is the total value of wages and salaries recorded in the profit or loss extract for 20X7?
$145,900
-
The amount for administration salaries in 20X7 is $100,000.
-
What is the figure for purchases (no inventory) in 20X7?
$1,105,830
-
What is the net cash inflow from operating activities for the year ended 31 December 20X7?
$115,166
-
How is the amount of cash received from customers determined when calculating operating cash flows?
By analyzing the receivables ledger account: - Opening Balance: $265,840 - Revenue: $1,589,447 - Closing Balance: $346,000 - Cash received: $1,509,287
-
How is cash paid to suppliers determined in the operating activities calculation?
Using the payables ledger account (excluding non-current asset purchases): - Opening Balance: $210,564 - Purchases (Cost of sales $1,105,830 + Operating costs $96,077): $1,201,907 - Closing Balance: $258,240 - Cash paid: $1,154,231
-
When calculating cash paid to suppliers for operating activities, non-current asset purchase invoices totaling $80,000 are excluded from the payables ledger.
-
The net cash flow from operating activities calculation includes: - Cash received from customers: $1,509,287 - Cash payments to suppliers: (1,154,231) - Cash paid to employees: (239,890)
-
Based on the ledger account shown, what is the total amount of net wages paid?
$239,890
-
In the Wages and salaries ledger account, the balance brought forward (b/f) is \(\)8,640 and the balance carried forward (c/f) is \(\)14,650.
-
What is the change in trade receivables for the year ended 30 September 20X8?
A decrease of \(4,383 (\)35,633 - $31,250).
-
What is the change in trade payables for the year ended 30 September 20X8?
An increase of \(445 (\)14,195 - $13,750).
-
Calculate the movement in accrued wages expense for the period.
Increase of \(180 (\)1,015 - $835).
-
Calculate the change in interest payable.
Increase of \(50 (\)350 - $300).
-
Calculate the change in income tax payable.
Increase of \(175 (\)1,250 - $1,075).
-
The note regarding the contra between trade receivables and trade payables states that it amounts to \(\)230 and it has not yet been accounted for.
-
What is the starting point for calculating cash flows from operating activities using the indirect method?
Profit before tax.
-
Why is depreciation added back to profit before tax in the indirect method?
Because it is a non-cash expense that does not result in a cash outflow.
-
How is a loss on the disposal of non-current assets treated in the indirect method?
It is added back to profit before tax because it is a non-cash expense.
-
How is a gain on the disposal of non-current assets treated in the indirect method?
It is deducted from profit before tax.
-
Why is interest payable expense added back to profit before tax when using the indirect method?
Because it is not part of cash generated from operations.
-
Under the indirect method, an increase in inventory is deducted from profit before tax, while a decrease in inventory is added to profit before tax.
-
In the indirect method, an increase in trade receivables is deducted from profit before tax, and a decrease in trade receivables is added to profit before tax.
-
In the indirect method, an increase in trade payables is added to profit before tax, whereas a decrease in trade payables is deducted from profit before tax.
-
What information is required to prepare a statement of cash flows?
Information from the current and prior year statement of financial position and the current year statement of profit or loss.
-
What was the total value of non-current assets for Geronimo as of 31 December 20X6?
$1,048,000
-
What is the total value of current assets for Geronimo as of 31 December 20X5?
$259,000
-
How much was the accumulated depreciation for Geronimo in 20X6?
$190,000
-
What was the total amount of share capital for Geronimo as of 31 December 20X6?
$200,000
-
What was the total value of revaluation surplus for Geronimo as of 31 December 20X5?
$12,000
-
What was the value of the loan for Geronimo in 20X6 and 20X5?
In 20X6, the loan was $200,000. In 20X5, the loan was $300,000.
-
Calculate the net book value of non-current assets for Geronimo in 20X6.
The net book value is calculated as $1,048,000 - $190,000 = $858,000.
-
The total assets for Geronimo as of 31 December 20X6 were $1,157,000.
-
As of 31 December 20X6, Geronimo had a trade payable amount of \(77,000 and a tax payable amount of \)76,000.
-
The retained earnings for Geronimo increased from \(226,000 in 20X5 to \)283,000 in 20X6.
-
Provide the total figure for Equity and liabilities in 20X6 and 20X5.
In 20X6, the total was $1,157,000. In 20X5, the total was $889,000.
-
What is the operating profit for Geronimo for the year ended 31 December 20X6?
$113,000
-
How is the cash flow for interest and income taxes paid calculated?
By reference to the charge to profits for the item shown in the statement of profit or loss and any opening or closing payable balance shown on the statement of financial position.
-
The operating profit for Geronimo for the year ended 31 December 20X6 was $113,000.
-
The net profit for the year for Geronimo was $92,000.
-
What are two examples of items that may be included in cash flows from operating activities?
- Interest paid
- Income taxes paid
-
Operating expenses for Geronimo include a loss on disposal of non-current assets of $5,000.
-
What was the original cost of the plant disposed of by Geronimo?
$80,000
-
What was the accumulated depreciation on the plant disposed of by Geronimo?
$15,000
-
The indirect method is a technique used to calculate the cash flow generated from operations.
-
When using a T-account to determine cash paid for interest or tax, what are the components of the debit side (left side) and credit side (right side)?
Debit side: - Cash paid - Accrual c/f
Credit side: - Accrual b/f - P&L charge
-
How is the cash paid figure derived in a T-account working for interest or tax?
The cash paid is the missing figure, calculated by taking the opening and closing accruals from the statement of financial position and the expense for the year from the statement of profit or loss.
-
Cash flows from investing activities include interest received, dividends received, and proceeds of disposal of non-current assets.
-
What is a major cash outflow example within investing activities?
Purchase of property, plant and equipment.
-
Under IAS 7, how might interest and dividends received be classified?
They are normally classified as investing activities, but IAS 7 permits them to be classified as operating activities.
-
Whatever classification is adopted for interest and dividends received, it must be applied consistently from one accounting period to another.
-
What figures are required to calculate interest and dividends received?
The income shown in the statement of profit or loss and any relevant receivables balance from the opening and closing statements of financial position.
-
What is the recommended tool for calculating complex cash flow items like interest or dividends in a statement of cash flows?
T-account workings.
-
In a T-account for interest receivable, what does the balancing figure typically represent?
Cash received.
-
To calculate cash flows related to property, plant, and equipment, one should use T-accounts for the cost account, the accumulated depreciation account, and the disposals account (where relevant).
-
When there is a revaluation of an asset, where should the uplift in value be recorded in the T-account?
On the debit side of the asset T-account.
-
What is the heading under which dividends and interest received are shown in a statement of cash flows?
Cash flows from investing activities.
-
Data from financial statements should be entered into T-accounts to find required cash flows, which are often found as balancing figures.
-
What should be used when there is insufficient detail to produce separate asset and accumulated depreciation accounts?
A carrying amount T-account working should be used.
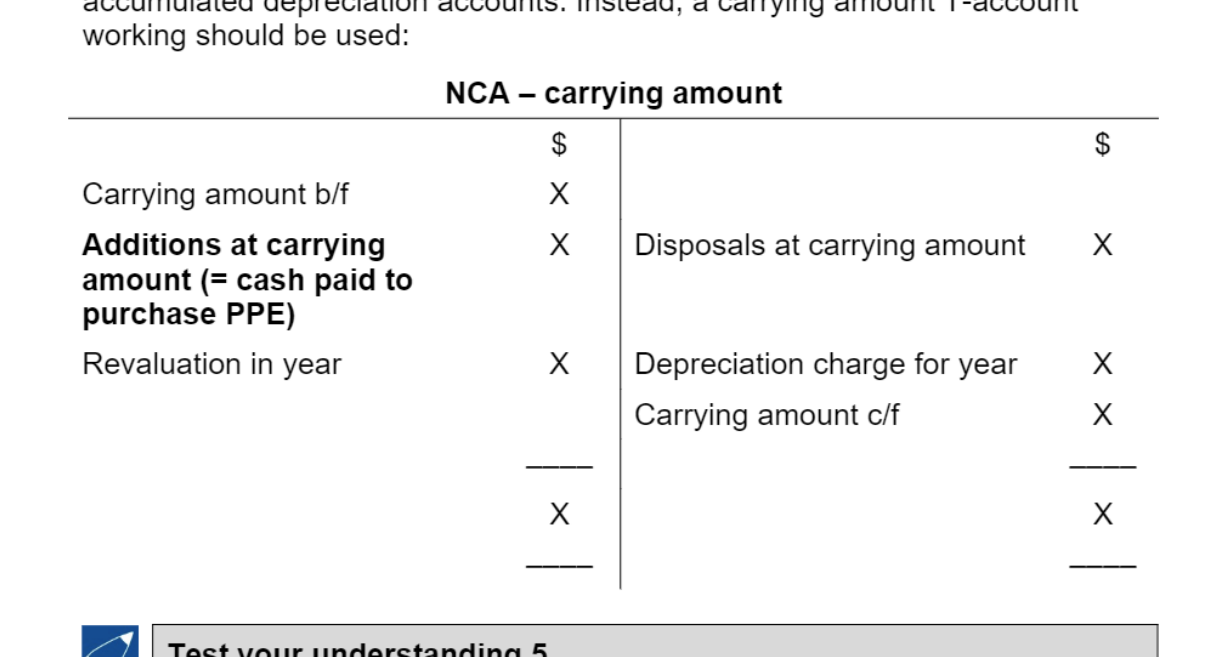
-
What is the cash outflow to purchase PPE equivalent to in an NCA carrying amount T-account?
Additions at carrying amount.
-
Cash inflows from financing activities include proceeds of the issue of shares and proceeds of receipt of loans/debentures.
-
Cash outflows from financing activities include: - repayment of loans/debentures - dividends paid - interest paid
-
According to IAS 7, where can interest paid be classified in the statement of cash flows?
Within operating activities or within financing activities.
-
What is the crucial requirement for classifying interest paid in the statement of cash flows under IAS 7?
The cash outflow for interest must be classified consistently in either operating or financing activities and must not be included twice.
-
Which two accounts are compared to calculate the proceeds from a share issue?
- Share capital
- Share premium
-
How should a bonus issue made during the year be treated when calculating cash flows from a share issue?
It should be excluded as it does not result in a cash inflow, but must be included in the workings to ensure share capital movements are correctly stated.
-
How is the cash flow from loan proceeds or repayments derived?
By comparing the brought forward balance of the loan with the balance carried forward.
-
If there is a fall in the loan balance outstanding, it indicates that the loan has been repaid.
-
If there is an increase in the loan balance outstanding, it indicates that a further loan was received during the year.
-
How is the amount of dividends paid usually identified in financial statements?
By reconciling the opening and closing balances of retained earnings to identify the dividend paid as a balancing figure.
-
Under IAS 7, how can dividends paid be classified in the statement of cash flows?
They can be classified as either an operating cash flow or a financing cash flow.
-
Which classification is most commonly used for dividends paid in the statement of cash flows?
It is more usual to classify dividends paid as a financing cash flow.
-
What is the requirement for 'Test your understanding 6' regarding Geronimo's statement of cash flows?
Identify and calculate each of the amounts to be shown under the heading 'Cash flows from financing activities'.
-
What are the three main categories typically included in a statement of cash flows?
- Cash flows from operating activities
- Cash flows from investing activities
- Cash flows from financing activities
-
What items are typically included under 'Cash flows from operating activities' in a statement of cash flows?
- Cash generated from operations
- Interest paid
- Tax paid
-
What items are typically included under 'Cash flows from investing activities' in a statement of cash flows?
- Proceeds of sale of equipment
- Purchase of property, plant and equipment
- Interest received
- Dividends received
-
What items are typically included under 'Cash flows from financing activities' in a statement of cash flows?
- Proceeds of issue of shares
- Repayment of loans
- Dividends paid
-
The net increase in cash and cash equivalents is calculated by summing the net cash flows from operating, investing, and financing activities.
-
The cash and cash equivalents at the end of the period is calculated as the sum of the net increase in cash and cash equivalents and the cash and cash equivalents at the beginning of the period.
-
What is the total carrying amount (CA) of Plant and Buildings for Algernon as of 31 December 20X7?
The total carrying amount is $85,000, calculated as $6,000 for Plant and $79,000 for Buildings.
-
What was the total value of Investments at cost for Algernon on 31 December 20X7?
$80,000.
-
What was the total value of land held by Algernon on 31 December 20X7?
$63,000.
-
What was the Revaluation surplus (land) reported by Algernon on 31 December 20X7?
$20,000.
-
What was the value of 10% Loan notes for Algernon on 31 December 20X7?
$150,000.
-
The carrying amount for buildings in 20X6 was \(40,000, while in 20X7 it increased to \)79,000.
-
The ordinary shares for Algernon were valued at $50,000 on 31 December 20X7.
-
Payables for Algernon increased from \(40,000 in 20X6 to \)60,000 in 20X7.
-
What is the total balance sheet footing for Algernon for both 20X7 and 20X6?
- 20X7: $343,000
- 20X6: $237,000
-
What was the Cash at bank value for Algernon on 31 December 20X6?
$3,000.
-
What is the net profit for Algernon for the year ended 31 December 20X6?
$20,000
-
What is the net profit for Algernon for the year ended 31 December 20X7?
$40,000
-
How much was the dividend paid by Algernon in 20X7?
$20,000
-
For the year ended 31 December 20X6, Algernon's sales were $200,000 and cost of sales was $120,000.
-
For the year ended 31 December 20X7, Algernon's sales were $200,000 and cost of sales was $100,000.
-
The expenses reported for Algernon in 20X6 were $47,000 and in 20X7 were $50,000.
-
The interest paid by Algernon was $13,000 in 20X6 and $10,000 in 20X7.
-
When preparing a statement of cash flows, which specific method is required by the problem for Algernon?
The direct method.
-
In a statement of cash flows, how should a loss on disposal be treated relative to profit before tax?
It should be added back to profit before tax, because it is a non-cash expense that was previously deducted.
-
In a statement of cash flows, how is an increase in receivables treated?
It is deducted from profit, as it represents cash tied up in working capital that has not yet been received.
-
In a statement of cash flows, how is an increase in payables treated?
It is added to profit, as it represents a source of cash through deferred payment to suppliers.
-
Which of the following items can appear in an entity's statement of cash flows: 1. Proposed dividend, 2. Dividends received, 3. Bonus issue of shares, 4. Surplus on revaluation of non-current assets?
Only item 2 (Dividends received). Proposed dividends, bonus issues, and revaluation surpluses are non-cash items and do not appear in the statement of cash flows.
-
What is the formula to calculate cash generated from operations when starting from profit before tax?
Profit before tax + Depreciation + Finance costs + Decrease in inventory - Increase in prepayments - Decrease in trade payables + Decrease in trade receivables (if applicable).
-
Calculate the cash generated from operations for Caddyshack Co. based on the following: Profit before tax $434,850, Depreciation $37,400, Finance costs $35,000, decrease in inventory $22,000, decrease in trade receivables $1,000, increase in prepayments $11,000, decrease in trade payables $16,000, decrease in interest payable $22,000.
Cash generated from operations = $434,850 + $37,400 + $35,000 + $22,000 + $1,000 - $11,000 - $16,000 = $503,250. Note: Interest payable is not included in cash generated from operations.
-
When calculating cash generated from operations, depreciation and finance costs are added back to the profit before tax because they are non-cash or financing activities.
-
For Caddyshack Co, the change in inventory from 20X5 to 20X6 is a decrease of $22,000, which acts as a cash inflow in the statement of cash flows.
-
The change in trade payables for Caddyshack Co. from 20X5 to 20X6 resulted in a cash outflow of $16,000 because the liability decreased.
-
What is the primary benefit of a statement of cash flows regarding business liquidity?
It helps to assess the liquidity of a company.
-
A statement of cash flows helps to assess future cash flows and allows users to see cash flows in and out of the business.
-
According to IAS 7, what are the three required headings in a statement of cash flows?
- Operating activities
- Investing activities
- Financing activities
-
How is cash movement calculated when preparing a statement of cash flows?
It is the movement between the current and previous year's balance in the statement of financial position.
-
When preparing a statement of cash flows, one must be careful with trickier areas such as taxation and non-current assets where a working will need to be done.
-
What kind of information can be derived from interpreting a statement of cash flows?
- How a business spends and receives cash
- Whether operating activities yield a positive cash flow
- Whether the business has the ability to generate cash in the future
-
What is the total cash inflow from operations in 'Test your understanding 1'?
$215,173
-
How is the net cash inflow from operating activities calculated from cash inflow from operations?
Net cash inflow from operating activities = Cash inflow from operations - Interest paid - Income tax paid
-
In the provided receivables ledger (W1), how is the cash received from customers calculated?
Cash receipts (\(?eta\)) = Balance b/f + Sales revenue - Contra with payables - Balance c/f
-
In the receivables ledger, the balance c/f is calculated as 31,250 - 230 which equals 31,020.
-
In the provided payables ledger (W2), how is the cash paid to suppliers calculated?
Cash paid (\(?eta\)) = Balance b/f + Purchases - Contra with receivables - Balance c/f
-
The net cash inflow from operating activities shown in the statement is $213,558.
-
What is the impact of a 'contra with payables' on the cash received from customers ledger?
It acts as a deduction from the total receivables before arriving at the cash receipt amount.
-
Based on the statement, interest paid is $(275) and income tax paid is $(1,340).
-
What is the accounting effect of accounting for a contra as described in the note?
It reduces the balance outstanding at the year-end of both trade receivables and trade payables.
-
In the Wages (W3) account, the total value credited to the Profit or Loss account is $52,750.
-
The Interest payable (W4) account shows a balance brought forward of $300 and a closing balance (c/f) of $350.
-
For the Income tax (W5) account, the total amount charged to Profit or Loss is $1,515.
-
How much was paid in net wages as shown in account (W3)?
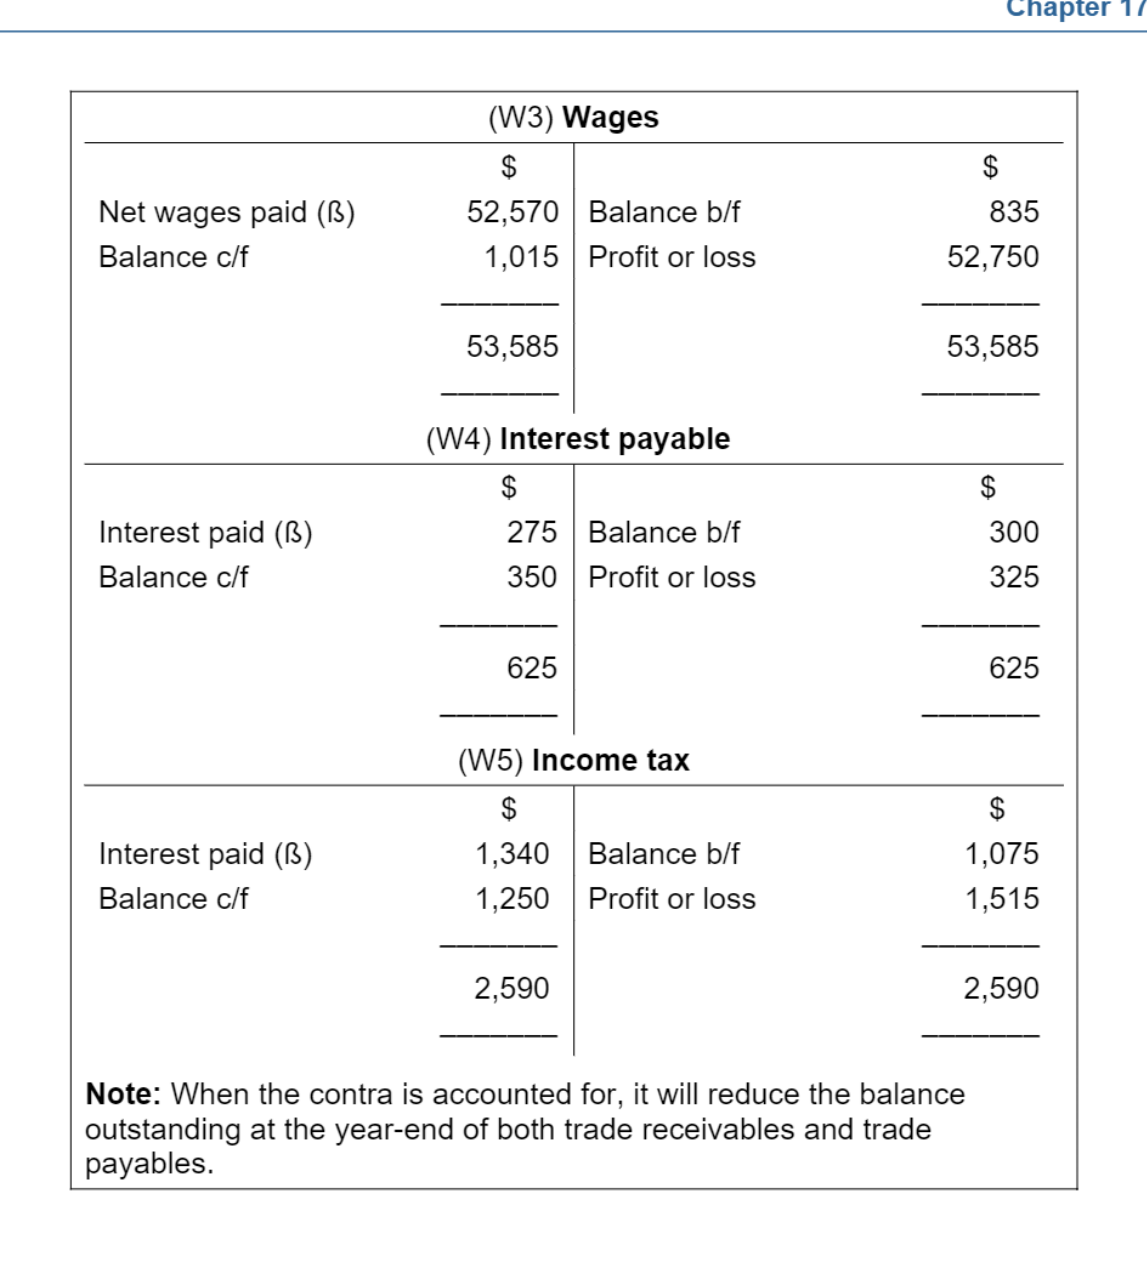 $52,570
-
What is the total value of interest paid as per the (W4) Interest payable account?
$275 -
What is the starting figure used to calculate 'Cash flow generated from operations' in the provided example?
Profit before tax of $163,000.
-
When calculating 'Cash flow generated from operations', how are finance charges treated in the statement?
They are added back to the profit before tax ($22,000).
-
When calculating 'Cash flow generated from operations', how is investment income treated in the statement?
It is subtracted from the profit ($72,000).
-
What is the effect of an increase in trade receivables on cash flow from operations?
It results in a cash outflow of $16,000.
-
What is the effect of a decrease in trade payables on cash flow from operations?
It results in a cash outflow of $2,000.
-
What additional items must be deducted from 'Cash flow generated from operations' to arrive at 'Net cash flow from operations'?
Interest paid and income tax paid.
-
In the accumulated depreciation account, what is the opening balance (balance b/f)?
$120,000.
-
What is the depreciation charge for the period as shown in the accumulated depreciation account (W1)?
$85,000.
-
The total cash flow generated from operations calculated in the example is \(\)192,000.
-
In the accumulated depreciation account, the depreciation charge of \(\)85,000 is used to reconcile the closing balance.
-
Explain the calculation of the depreciation charge shown in the cash flow statement using the accumulated depreciation account.
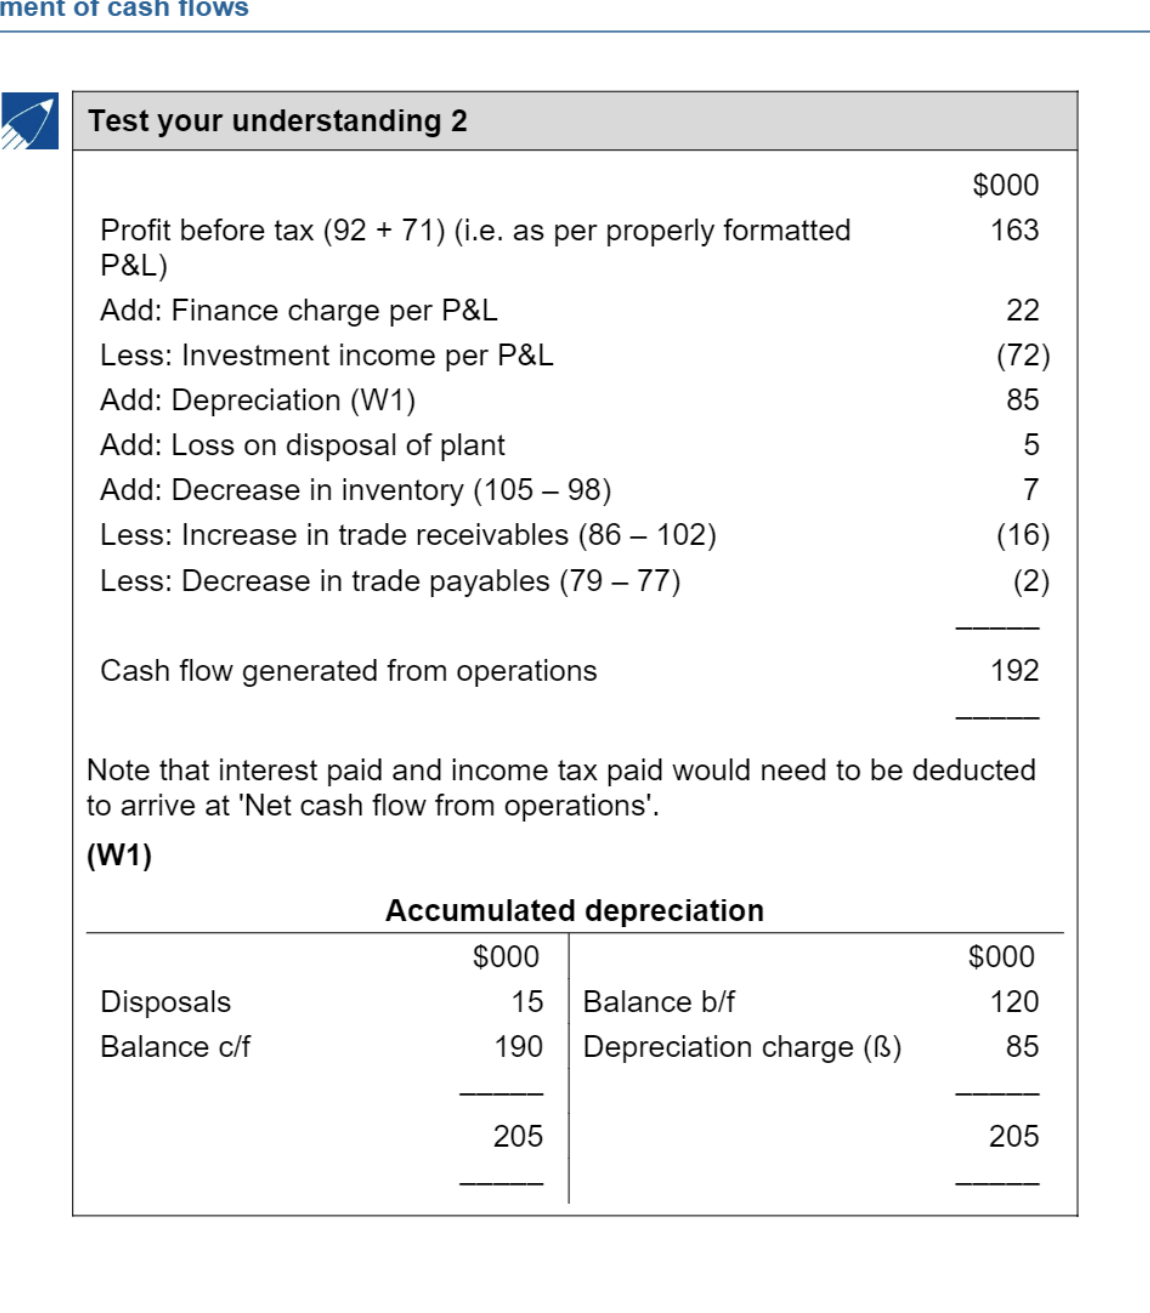
The depreciation charge for the period is calculated as the balancing figure: ($190,000 + $15,000) - $120,000 = $85,000.
-
Based on the ledger for Interest payable, what was the amount of interest paid in cash?
The interest paid in cash was $24,000.
-
What was the total P/L finance charge shown in the Interest payable account?
The P/L finance charge was $22,000.
-
Calculate the cash paid for income tax using the Income tax payable ledger provided.
Cash paid for income tax was $62,000.
Workings: (Opening balance $67k + P/L charge $71k) - Closing balance $76k = $62k.
-
For the Dividends receivable ledger, the opening balance was \(50,000 and the P/L dividends receivable was \)57,000.
-
How much cash was received for dividends based on the provided ledger?
The cash received for dividends was $50,000.
-
The Interest payable account shows an opening interest accrual (b/f) of $5,000.
-
In the PPE cost account, what does the amount of $178 represents?
It represents additions, which is the cash paid to purchase PPE.
-
How is the revaluation amount in the PPE cost account calculated?
\(212 - 12 = 200\)
-
The closing balance (Balance c/f) for the PPE cost account is \(1,048\) thousand dollars.
-
What is the total cost of the items disposed of, based on the Disposals account?
$80,000
-
How is the Loss on disposal calculated within the Disposals account?
It is the difference between the Cost (\(80) and the sum of Accumulated depreciation (\)15) and Proceeds ($60). \(80 - (15 + 60) = 5\).
-
The proceeds from the disposal of PPE amounted to \(60\) thousand dollars.
-
What are the components that make up the total value of the items disposed of in the Disposals account?
- Accumulated depreciation: $15,000
- Loss on disposal: $5,000
- Proceeds: $60,000
-
The Accumulated depreciation of the disposed PPE is $15,000.
-
What is the formula to calculate the loan repayment amount given a balance of $300,000 in 20X5 and $200,000 in 20X6?
$300,000 - $200,000 = $100,000
-
Based on the provided Retained earnings account, what is the calculation to find the dividends paid?
Dividends paid = (Opening Balance + Profit for the year) - Closing Balance. Calculation: ($226,000 + $92,000) - $283,000 = $35,000
-
The proceeds of a share issue can be calculated by adding the change in Share capital and the change in Share premium.
-
Using the Retained earnings account as a reference, identify the opening balance, profit, and closing balance.
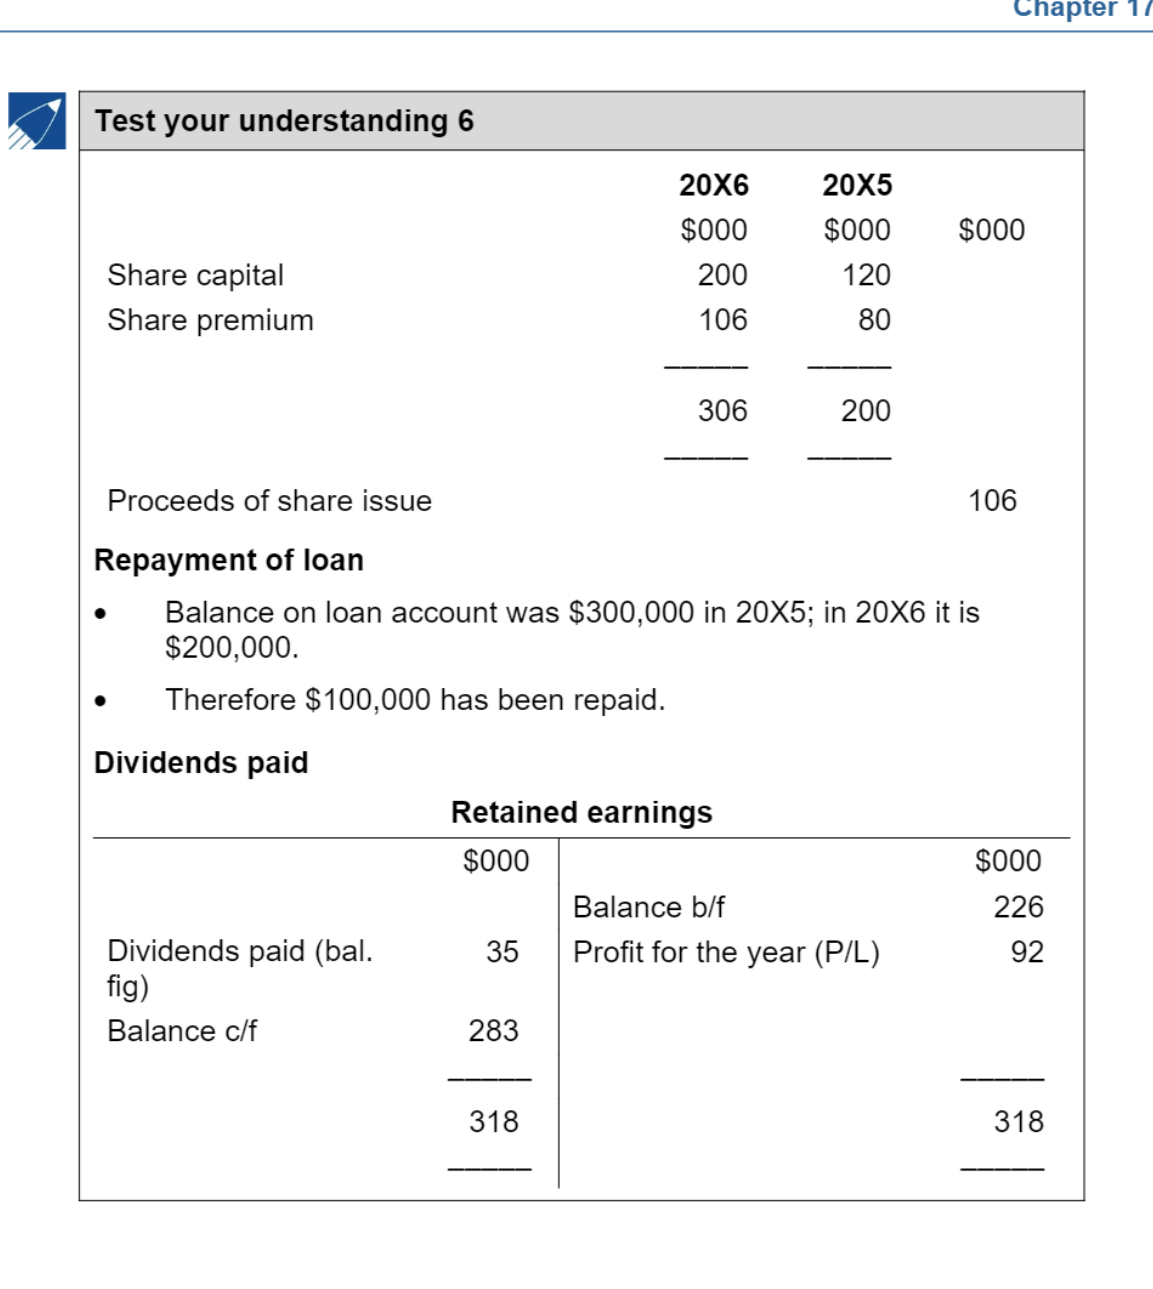 - Balance b/f: $226,000
- Profit for the year: $92,000
- Balance c/f: $283,000
-
To determine the dividends paid from the Retained earnings account, one must account for the opening balance and the profit for the year against the closing balance.
-
What is the calculation for 'Net cash generated from operating activities' for Geronimo in 20X6?
\(192 - 24 - 62 = 106\) ($000).
-
What is the calculation for 'Net cash used in investing activities' for Geronimo in 20X6?
\(60 - 178 + 15 + 50 = (53)\) ($000).
-
What is the calculation for 'Net cash generated from financing activities' for Geronimo in 20X6?
\(106 - 100 - 35 = (29)\) ($000).
-
For the year 20X6, Geronimo experienced a net increase in cash and cash equivalents of 24 ($000).
-
How are 'Cash and cash equivalents at end of period' calculated for Geronimo?
Add the 'Net increase in cash and cash equivalents' (\(24k) to the 'Cash and cash equivalents at beginning of period' (\)18k) to get $42k.
-
The main categories of a statement of cash flows are: - Cash flows from operating activities - Cash flows from investing activities - Cash flows from financing activities
-
Looking at the statement of cash flows for Geronimo, which items fall under investing activities?
- Proceeds of sale of equipment
- Purchase of property, plant and equipment
- Interest received
- Dividends received
-
Looking at the statement of cash flows for Geronimo, which items fall under financing activities?
- Proceeds of issue of shares
- Repayment of loans
- Dividends paid
-
The statement of cash flows for Geronimo for the year ended 31 December 20X6 shows that interest paid (\(24k) and tax paid (\)62k) are classified as operating activities.
-
In the statement of cash flows, the beginning cash balance of $18k plus the net increase of \(24k results in an ending cash balance of 42 (\)000).
-
What are the three main categories of cash flows presented in a Statement of Cash Flows?
- Operating activities
- Investing activities
- Financing activities
-
What is the net cash from operating activities for Algernon for the year ended 31 December 20X6?
$22,000
-
Which items are included in 'Cash flows from investing activities' in the provided Statement of Cash Flows?
- Purchase of tangible non-current assets
- Purchase of investments
-
What is the net cash used for investing activities for Algernon?
$(71,000)
-
Which items are classified under 'Cash flows from financing activities'?
- Issue of shares
- Loan notes
- Dividends paid
-
What was the total net cash from financing activities for Algernon?
$42,000
-
The net decrease in cash and cash equivalents for Algernon was $(7,000).
-
The cash and cash equivalents at 31 December 20X7 were $(4,000).
-
What is the balance at bank as of 31 December 20X7?
$(4,000)
-
What was the balance at bank on 31 December 20X6?
$3,000
-
Cash generated from operations is calculated by adding cash receipts from customers and subtracting cash paid to suppliers and employees.
-
Interest paid is categorized under operating activities in the statement of cash flows.
-
What is the formula for calculating receipts from sales in a Receivables account?
Opening Balance + Sales Revenue - Closing Balance = Cash Receipts Calculation: \(40,000 + 200,000 - 50,000 = 190,000\)
-
What is the formula to calculate cash paid, as shown in the Payables and wages account?
Opening Balance + Purchases (Cost of sales) + Expenses - Depreciation - Closing Balance = Cash paid Calculation: \(40,000 + 130,000 + 47,000 - 2,000 - 60,000 = 155,000\)
-
What is the relationship between Cost of sales, opening/closing inventory, and purchases?
Opening Inventory + Purchases = Cost of Sales + Closing Inventory Calculation: \(55,000 + 130,000 = 120,000 + 65,000 = 185,000\)
-
In the Receivables account, the Sales revenue of $200,000 is added to the opening balance, while the Cash receipts of $190,000 represents the outflow of cash.
-
Depreciation is recorded in the Payables and wages account as a credit adjustment of $2,000.
-
The calculation for purchases in the Cost of sales account is derived as: Cost of sales + Closing inventory - Opening inventory = $130,000.
-
What is the amount for Cash receipts in the Receivables account?
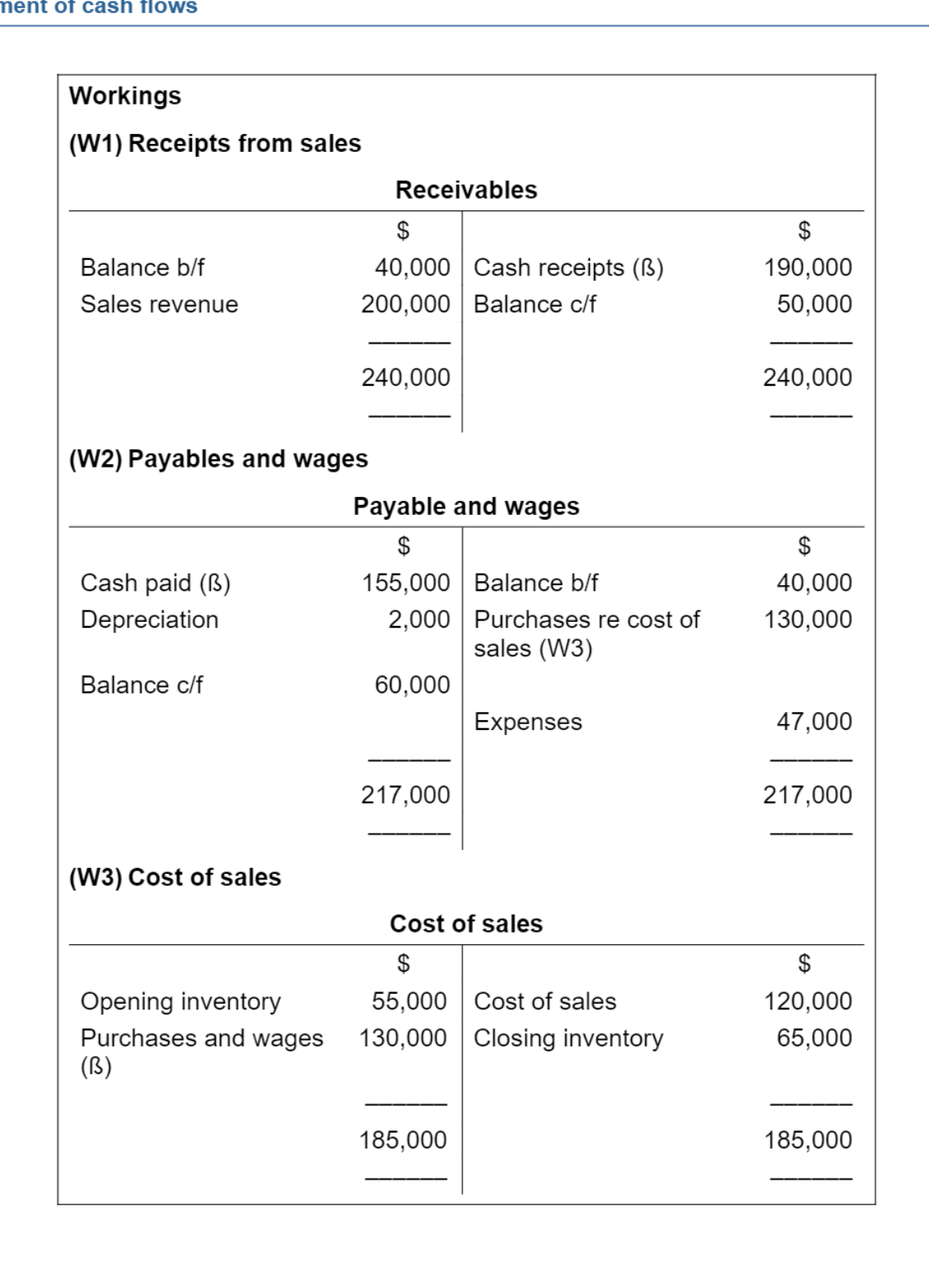 \(190,000\)
-
What is the total for Cash paid in the Payables and wages account?
\(155,000\) -
What is the value of purchases for cost of sales?
\(130,000\) -
When calculating cash generated from operations, should a loss on disposal be added back to profit?
Yes, a loss on disposal should be added back to profit because it is a non-cash expense.
-
Why are dividends received relevant to cash flow?
Dividends received are included in cash flow calculations because they involve a cash receipt.
-
When calculating cash generated from operations, the finance costs charged in the statement of profit or loss are included in the reconciliation, but the cash paid in the year relating to those costs is only relevant when calculating the net cash flow from operations.
-
What is the cash generated from operations based on the following: Profit before tax $434,850; Depreciation and loss $37,400; Decrease in inventory $22,000; Decrease in trade receivables $1,000; Increase in prepayments $(11,000); Decrease in trade payables $(16,000); Finance costs $35,000?
The cash generated from operations is $503,250.
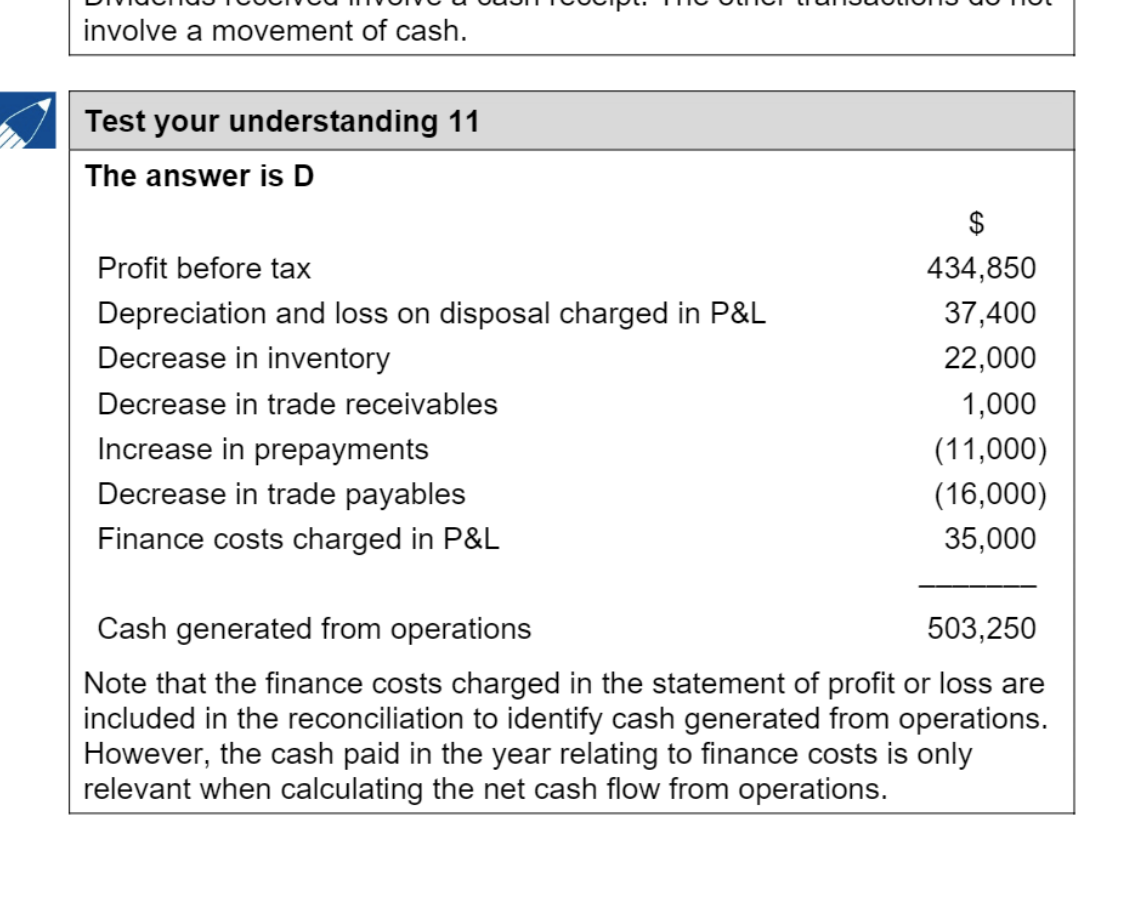
-
For the entity Algernon, the equity to assets ratio has decreased due to financing expansion through new share capital and loans.
-
Algernon has financed its working capital requirements through an increase in trade payables.